


Canadian National Railway (TSX:CNR) has raised its 2026 outlook after reporting higher freight volumes, double-digit revenue and adjusted earnings growth, and a continued dividend track record that now spans 30 consecutive years.
The upgraded 2026 outlook and stronger freight volumes have landed against a share price that has climbed 27.02% year to date. The 1-year total shareholder return of 33.48% and 3-year total shareholder return of 29.53% point to momentum that has cooled slightly after a recent 90-day share price return decline of 4.32%, but remains positive over a longer stretch.
Scan the rail momentum story beyond Canadian National Railway and evaluate hand picked transport and infrastructure plays with resilient balance sheets and cash flows using our 3 high quality undervalued stocks
Canadian National Railway now trades about 8% below average analyst targets while sitting roughly 19% above one intrinsic value estimate. Is that a reasonable safety margin or a warning that expectations ran too far ahead of fundamentals?
Most Popular Narrative: 8% Undervalued
Canadian National Railway's most followed narrative pegs fair value at about CA$189.32, above the last close of CA$175.01, which places the current share price at a discount according to that framework.
The Fast Track efficiency program, which has already delivered about US$100m of realized savings in the first half of 2026, together with record fuel efficiency and better locomotive and crew productivity, creates room for Canadian National Railway to lower unit costs and support net margins and earnings power.
See why 127 investors see Canadian National Railway as 8% undervalued.
Result: Fair Value of CA$189.32 (UNDERVALUED)
Still, if lumber and overseas intermodal demand stay weak or grain remains the main growth engine, the bullish Canadian National Railway thesis could prove too optimistic.
Find out about the key risks to this Canadian National Railway narrative.
Another View: Canadian National Railway Through A Cash Flow Lens
While the popular fair value narrative for Canadian National Railway leans on analyst targets and earnings assumptions, the Simply Wall St DCF model paints a different picture. On that measure, CNR at CA$175.01 screens as overvalued versus an intrinsic value estimate of CA$147.10. That gap points to a simple question: Are analyst growth assumptions generous compared with what long term cash generation might actually support?
To understand how this cash flow view is built and what would need to change for the two valuations to line up, take a closer look at the Look into how the SWS DCF model arrives at its fair value.
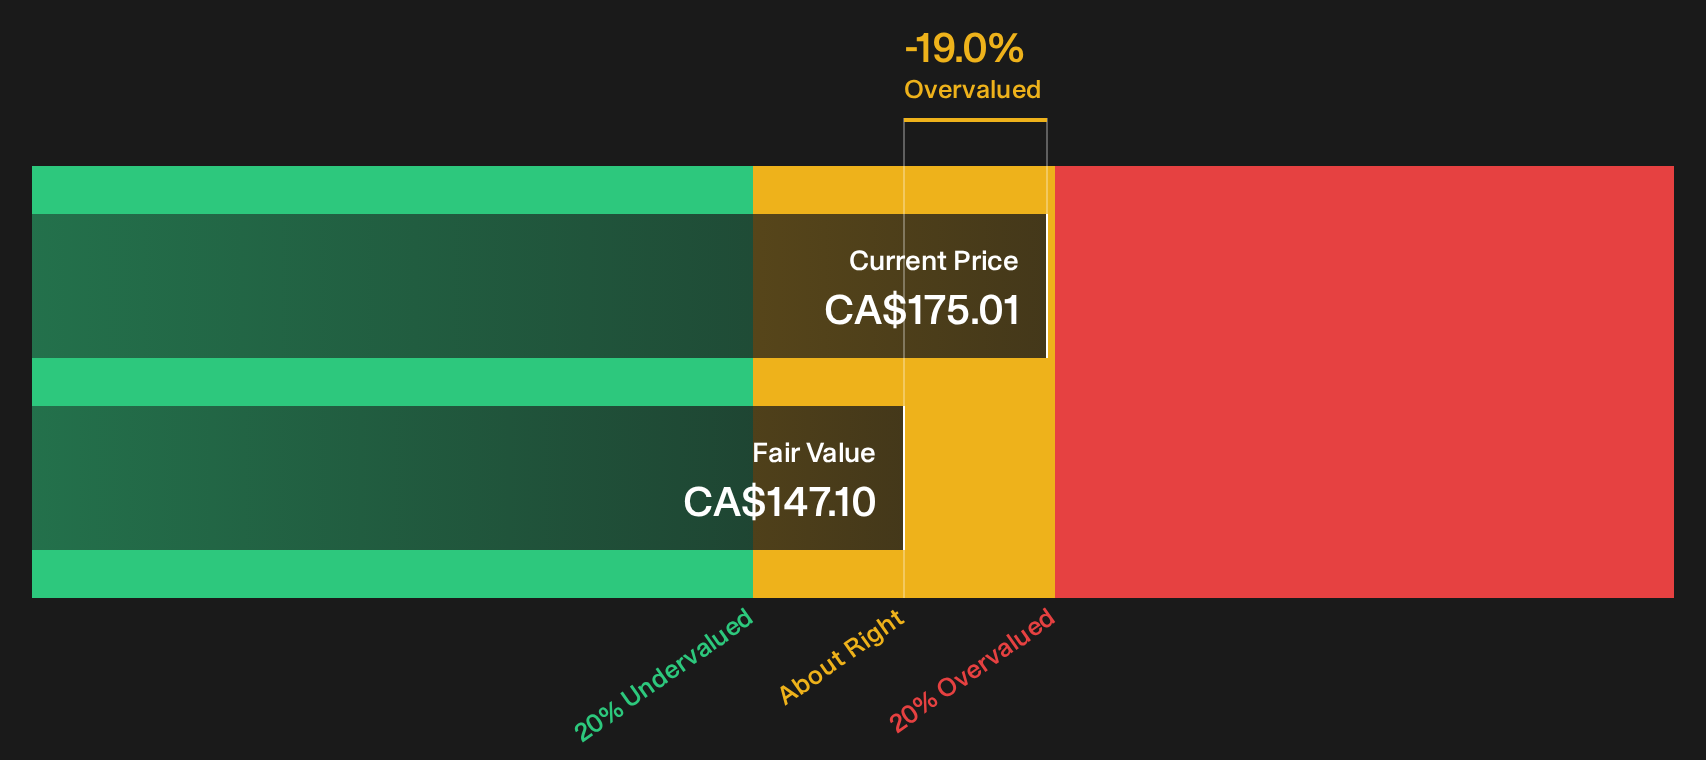
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Canadian National Railway for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 3 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Canadian National Railway's value case and risk profile are clear. Move quickly, review the underlying data, and weigh both the positives and pressure points using the 5 key rewards and 1 important warning sign
Looking for more investment ideas beyond Canadian National Railway?
If you only stop at Canadian National Railway, you risk missing other opportunities that might fit your goals, risk appetite, and income needs even better.
- Target resilient compounding potential by tracking companies that blend quality fundamentals with attractive pricing through our 3 high quality undervalued stocks.
- Build a steadier income stream by reviewing businesses with strong payout potential and higher yields using our 3 dividend fortresses.
- Dial down portfolio stress by focusing on companies flagged for balance sheet strength and durable fundamentals with our list of solid balance sheet and fundamentals (7 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com