


Why Getlink’s latest revenue update matters for shareholders
Getlink (ENXTPA:GET) just posted a 10% rise in third quarter group revenue to €521 million, helped by Shuttle services and a 41% jump at ElecLink, while reaffirming its 2026 EBITDA target.
Traffic trends were mixed in the period. Passenger vehicle volumes declined 2% to 782,846 units, yet truck shuttles increased 5% and high speed passenger train traffic edged higher, with management pointing to temporary EES related uncertainty as a drag on car flows.
Getlink’s latest revenue update lands with the share price at €19.54, after a 5.51% 1 month share price return and a 22.82% year to date share price gain. The 1 year total shareholder return of 28.79% points to momentum that has been building over several years, supported by 3 year and 5 year total shareholder returns of 48.37% and 69.14% respectively.
Scan how Getlink’s recent momentum compares with other transport and infrastructure plays by running them through our curated 222 resilient stocks with low risk scores filter for resilient balance sheets and steadier risk profiles.
Bulls point to Getlink’s ElecLink growth and reaffirmed 2026 EBITDA target, while bears focus on softer passenger traffic and the recent share price run. Which side does current valuation really support?
Price-to-Earnings of 32.6x: Is it justified?
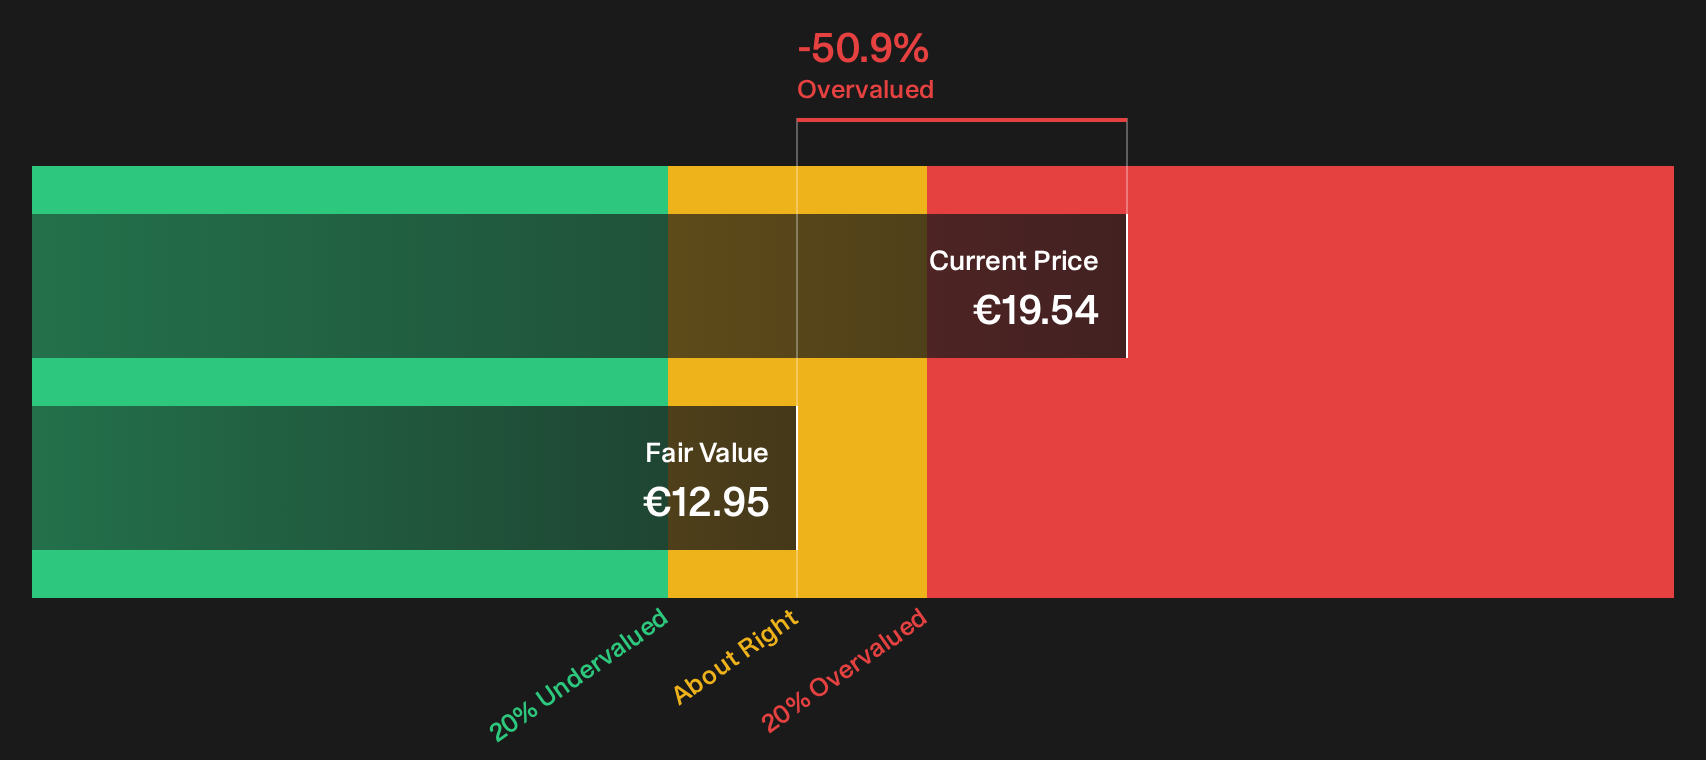
On the latest numbers, Getlink trades on a P/E of 32.6x, while our DCF work flags a future cash flow value of €12.95 versus the current €19.54 share price. This points to a rich valuation against both earnings and cash flow gauges.
The P/E ratio compares the share price with annual earnings per share. For a transport infrastructure operator like Getlink, it effectively shows how much investors are willing to pay today for each euro of current profit from assets such as the Eurotunnel, Europorte freight and ElecLink.
Against peers, that 32.6x earnings multiple is described as expensive versus both the European Infrastructure group on 17.5x and the company’s own estimated fair P/E of 14.1x. The gap is wide. This suggests the market is assigning a premium that goes well beyond the level the fair ratio implies the valuation could move toward if expectations normalise.
Explore the SWS fair ratio for Getlink.
Result: Price-to-Earnings of 32.6x (OVERVALUED)
Still, the Getlink story could be knocked off course if weaker passenger trends persist or if ElecLink volumes fail to match current optimism.
Find out about the key risks to this Getlink narrative.
Another view on Getlink’s valuation
The P/E screen paints Getlink as expensive, and the SWS DCF model also points to a premium. At €19.54, the share price sits well above the €12.95 future cash flow value. That double signal raises a simple question for investors: What is the market paying up for?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Getlink for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on valuation and operating trends can make Getlink tricky to read, so move quickly and stress test the thesis against the data yourself. To see both sides of the story in one place, start with the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Getlink?
If Getlink has you thinking more broadly about opportunities, do not stop here. Fresh ideas now can make a big difference to future results.
- Target stronger quality at fair prices by scanning a curated pool of companies using the 191 high quality undervalued stocks.
- Strengthen your income stream by reviewing a focused set of higher yield opportunities through the 224 dividend fortresses.
- Prioritise resilience by filtering for sturdier balance sheets and cleaner fundamentals in the list of solid balance sheet and fundamentals (204 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com