


Global tech stocks have come under pressure as investors question how much debt fueled AI infrastructure spending can continue, which puts more attention on the raw materials that make electrification and battery storage possible. That is where Australian lithium miners and processors enter the picture. This article walks through three stocks from a targeted lithium mining screener that could help you understand different ways to get exposure to this theme.
The three lithium stocks covered below are only a sample, and the full screen surfaced 28 more producers and processors with equally compelling narratives that are not discussed in this article. To identify your own highest conviction ideas across that wider set, head straight into the Lithium Mining screener
Liontown (ASX:LTR)
Overview: Liontown is an Australian minerals developer focused on the Kathleen Valley hard rock lithium project, while also exploring gold and nickel.
Operations: Liontown reports A$639 million from exploration and development of minerals, all tied to Australian projects across its portfolio.
Market Cap: A$2.19b
Liontown matters for this lithium mining theme because Kathleen Valley is a direct lever on future supply of spodumene concentrate for global battery makers.
"The company has initiated trials with higher contamination ore, achieving higher lithium recovery rates while maintaining strong recovery even with lower-grade material. This could improve net margins by optimizing processing costs over time."
What ultimately happens to Liontown’s earnings power will depend on how one unseen cost pressure plays out at full production scale.
That hidden pressure is exactly where the full narrative for Liontown shows how processing gains, capital intensity and pricing risk could be decoupling more than the headline story suggests.

IGO (ASX:IGO)
Overview: IGO is an Australian miner that produces battery minerals, with a dedicated Lithium Business supplying spodumene concentrate into the lithium-ion supply chain.
Operations: IGO generated A$448.9 million from the Nova Operation and A$14 million of interest revenue, all from customers in Australia.
Market Cap: A$3.89b
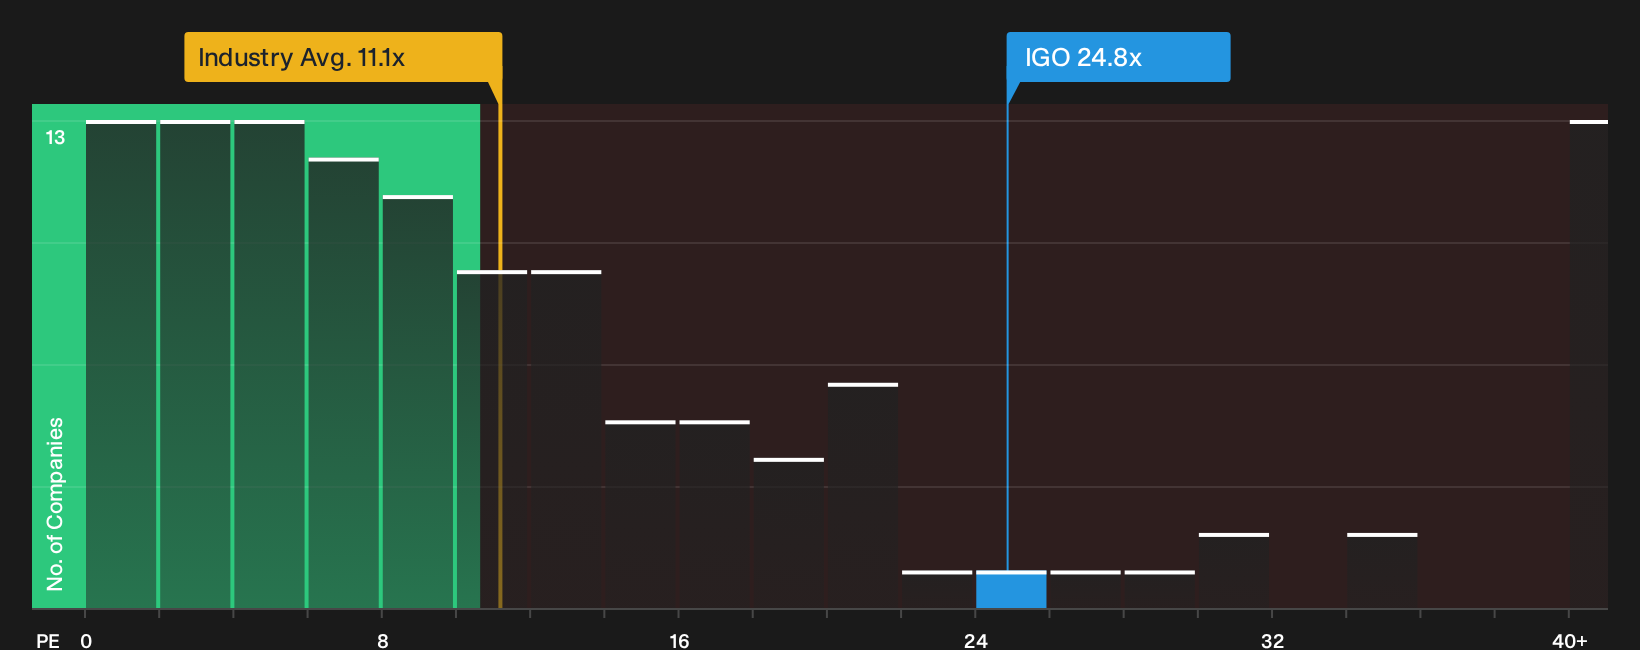
IGO provides direct exposure to lithium mining and processing through its Lithium Business, while also earning income from nickel and other metals. The group reported A$145.3 million of net income in the year to 30 June 2026 and has a P/E ratio of about 24.8x.
That mix of earnings and valuation is only the starting point for IGO, so step into the analysis report for IGO to see what might be getting mispriced.
PLS Group (ASX:PLS)
Overview: PLS Group is an Australian miner focused on its 100% owned Pilgangoora hard rock lithium project in Western Australia.
Operations: PLS Group reports A$1.93b from exploration, development and mining of minerals, largely sold into China and other foreign markets.
Market Cap: A$9.19b
PLS Group matters for this lithium mining theme because Pilgangoora feeds directly into global battery supply chains as a large scale spodumene source.
"PLS Group continues to build out Pilgangoora as a large scale, low cost hub, with record FY26 production of 880,000 tonnes, higher guided output of 1.03 to 1.10 million tonnes in FY27 and ongoing recovery gains, which together point to further operating leverage that can support revenue and earnings."
What investors will watch most closely is how one quiet shift in project economics ultimately shapes margins across the next lithium cycle.
That shift is where the full narrative for PLS Group pulls together how Pilgangoora’s scale, pricing risk and capital spend could be quietly reshaping PLS Group’s earnings trajectory.

Seeking Alternatives Before The Crowd
Fresh opportunities move fast. Breakout stories gain momentum, laggards keep dropping and quiet winners slip away under the radar for now. Scan what others miss and get in early.
- Spot strong payouts that could steady your portfolio while growth stories churn by scanning the 6 dividend fortresses before yields are chased more aggressively by the crowd.
- Track early movers tied to crypto infrastructure and payment rails using the curated 18 cryptocurrency and blockchain stocks while these stories are still flying under most radars.
- Target metal producers positioned for grid upgrades and electrification by filtering through the 16 top copper producer stocks before momentum buyers respond later in the cycle.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com