


European defense electronics just received a powerful reality check, as Saab’s Q3 beat and a surge in fresh orders pulled investor attention back to radar, sensors, and mission systems across the region. The news has put a fresh spotlight on stocks that may be tied, directly or indirectly, to similar demand trends, and no one wants to miss a potential rerating story. This article unpacks three stocks that appear positively exposed to these catalysts and explains what that could mean for your portfolio.
The three stocks below are just a starting sample. The wider screen surfaced 25 more European defense subsystems and electronics suppliers with equally strong storylines that are not covered here but could matter just as much for your watchlist. If you want to identify and analyze the higher conviction angles across this space, head straight into the European Defense Subsystems & Electronics Suppliers screener
Addtech AB (publ.) (OM:ADDT B)
Addtech AB (publ.) plugs into the screener theme through its industrial electronics and sensor offerings that can feed into defense subsystem supply chains, while its broader role is supplying technical products and integrated solutions across manufacturing, infrastructure, energy and safety markets.
"The focus on products for electrical transmission, distribution and related energy infrastructure is supported by a very strong quotation backlog and high order intake in Energy. This can feed into sales, margins around 19% and earnings as grid and power projects move from order to delivery."
What happens if one quiet shift in demand across those longer dated projects tilts the balance between comfortable margins and a tighter squeeze.
That margin tipping point is exactly where the risk and opportunity start to separate, which is why the full narrative for Addtech AB (publ.) maps out how grid exposure could be quietly accelerating or masking pressure.

Ependion (OM:EPEN)
Ependion supplies secure digital control, visualization and data communication systems that can be applied to mission and avionics style control and communications subsystems. The Westermo division generates about SEK1.5 billion, Beijer Electronics about SEK0.9 billion, with a market value near SEK5 billion anchoring it in the mid cap industrial tech bracket.
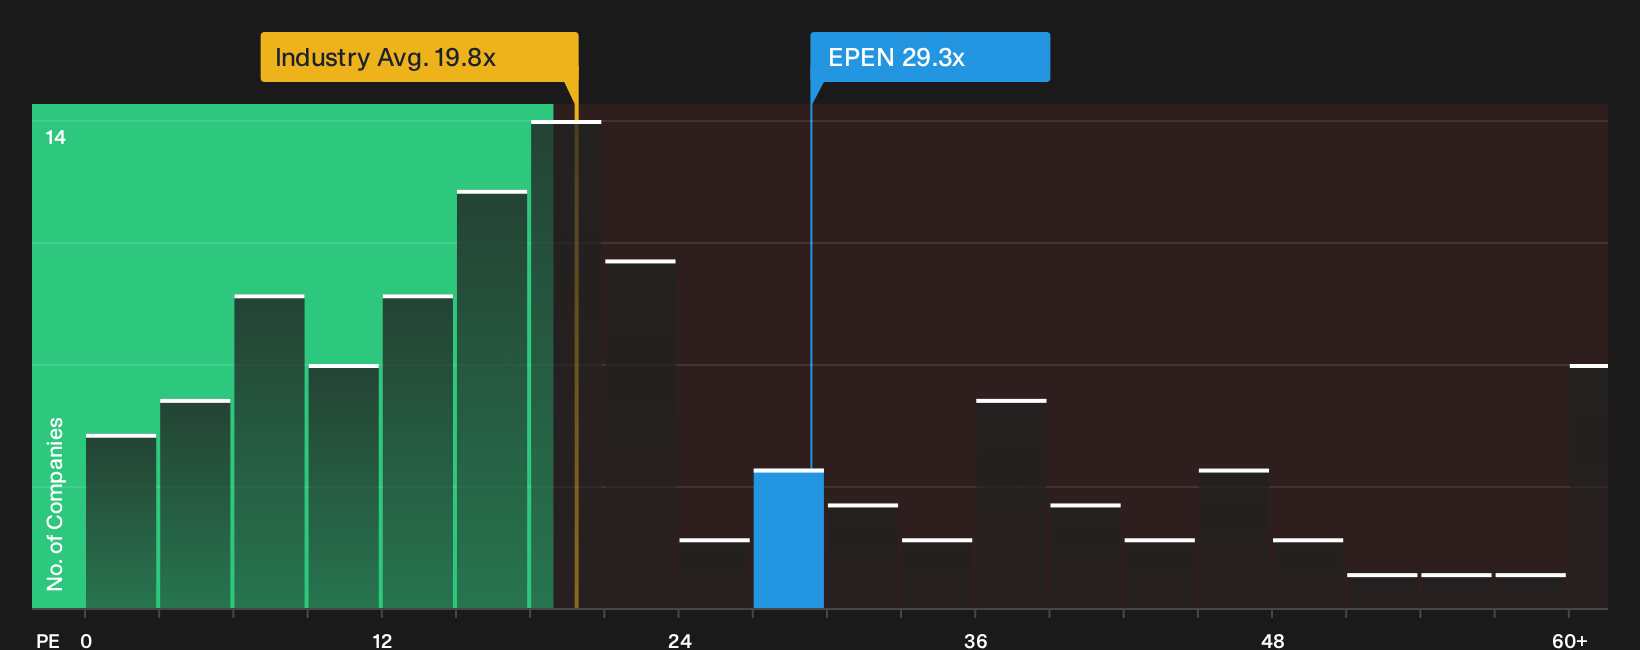
Ependion links directly to the screener theme through hardened networking gear and control systems that can support mission critical rail and industrial infrastructure. This is the same type of secure connectivity and data handling that defense platforms require. Investors get earnings growth forecasts and high quality profits, yet the forecast revenue decline and premium P/E mean a shift in contract visibility or capital costs could matter more than it first appears.
That inflection risk is exactly why the analysis report for Ependion could be worth your time if you want to see where Ependion’s premium starts to look stretched or resilient.
NOTE (OM:NOTE)
NOTE AB plugs directly into the screener theme as a Western European electronics manufacturer that can assemble complex radar, avionics and mission system hardware for larger defense contractors, while still serving medtech, greentech, industrial and communications customers.
Western Europe generates about SEK3.1 billion of NOTE’s SEK4 billion business revenue, with the rest of world contributing roughly SEK1 billion, and the stock carries a market value of about SEK4.9 billion.
For investors following Saab’s order boom into the supply chain, NOTE offers a way to track how that demand filters into printed circuit board assemblies, subassemblies and full box builds for security and defence electronics.
"Although Security & Defence at NOTE is currently described as the strongest area for organic growth with a larger share of sales and a defence order book that extends into 2027, the same component shortages in PCBs and complex semiconductors that are already pushing deliveries into later quarters could delay conversion of that pipeline into recognised revenue and limit the uplift to earnings."
The real swing factor now is whether a subtle shift in how quickly high value orders turn into shipped hardware reshapes margins and cash generation.
When that conversion speed starts to shift, the full narrative for NOTE shows where NOTE’s defence backlog could be quietly accelerating earnings power or masking brewing pressure.

Seeking Alternatives Before Momentum Flies Past
Fresh breakouts and early momentum often get caught quickly once the crowd arrives. Scan under the radar for now, before prices start flying and the edge drops. Consider moving early, before broader interest builds.
- Target high-yield stability while income hunters hesitate and lock in a shortlist of 224 dividend fortresses before the market focuses more closely on their payout resilience.
- Identify early AI momentum that has not yet been fully reflected in prices and use the 38 profitable AI stocks that aren't just burning cash to focus on businesses already funding growth from real earnings.
- Follow the build-out of next generation infrastructure and track potential beneficiaries through the 42 power grid technology and infrastructure stocks while these grid upgrades remain relatively under the radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com