


- Takeda Pharmaceutical released detailed clinical data across three key franchises, including Phase 4 VERDICT results for ENTYVIO in ulcerative colitis, commercial availability of orexin agonist ORZEYFUL for narcolepsy type 1 in Japan and China, and Phase 2/3 IgGNITE findings for investigational TAK-881 in primary immunodeficiency disease.
- The cluster of late stage readouts and launches shows Takeda Pharmaceutical scaling a mix of gut focused biologics, orexin based sleep therapies and subcutaneous immunoglobulin candidates that collectively broaden its specialty portfolio across immunology and neuroscience.
- We will now see how Takeda Pharmaceutical's investment narrative could be influenced by ENTYVIO's VERDICT data on ulcerative colitis complications.
Scan Takeda Pharmaceutical’s peers that are building out immunology and neuroscience pipelines and see which ones made the cut in our curated list of list of solid balance sheet and fundamentals (23 results).
Takeda Pharmaceutical Investment Narrative Recap
Takeda Pharmaceutical’s story hinges on whether newer therapies can gradually reshape a portfolio that still carries loss of exclusivity and debt concerns. The central belief is that orexin, TYK2 and GI assets eventually do more of the heavy lifting as older products fade. The recent ENTYVIO, ORZEYFUL and TAK-881 data points support that pipeline depth, but they do not change the near term balance sheet or cash flow picture.
Over the next year or two, the key swing factor is execution on launches and label expansions while keeping margins under control as Takeda Pharmaceutical remains loss making. The biggest risk is that generic and biosimilar pressure on ENTYVIO and VYVANSE is stronger or earlier than expected, before the newer products reach meaningful scale, which would make the existing growth and earnings path harder to achieve.
The VERDICT readout on ENTYVIO looks particularly relevant to the current narrative. It offers detailed, prospective evidence that treating to corticosteroid free disease clearance in ulcerative colitis can be a clinically meaningful goal. For an investor, this reinforces the clinical backbone of a core GI franchise at the same time as vedolizumab faces the prospect of biosimilar competition in coming years.
Better defined treatment targets and long duration safety data can help physicians keep ENTYVIO central in treatment algorithms, which matters as Takeda Pharmaceutical seeks to support revenue while newer launches scale. The risk is that strong data does not fully offset pricing pressure or future copycat products, so the real test remains whether ENTYVIO’s differentiated profile, together with orexin and immunology assets, is sufficient to stabilise the overall portfolio mix.
Takeda Pharmaceutical is underpinned by analyst assumptions that revenues reach ¥4,989.8b and earnings reach ¥401.8b by 2029, based on yearly revenue growth of 2.6% and an earnings swing of roughly ¥565.2b from a current loss of ¥163.4b to the forecast profit level.
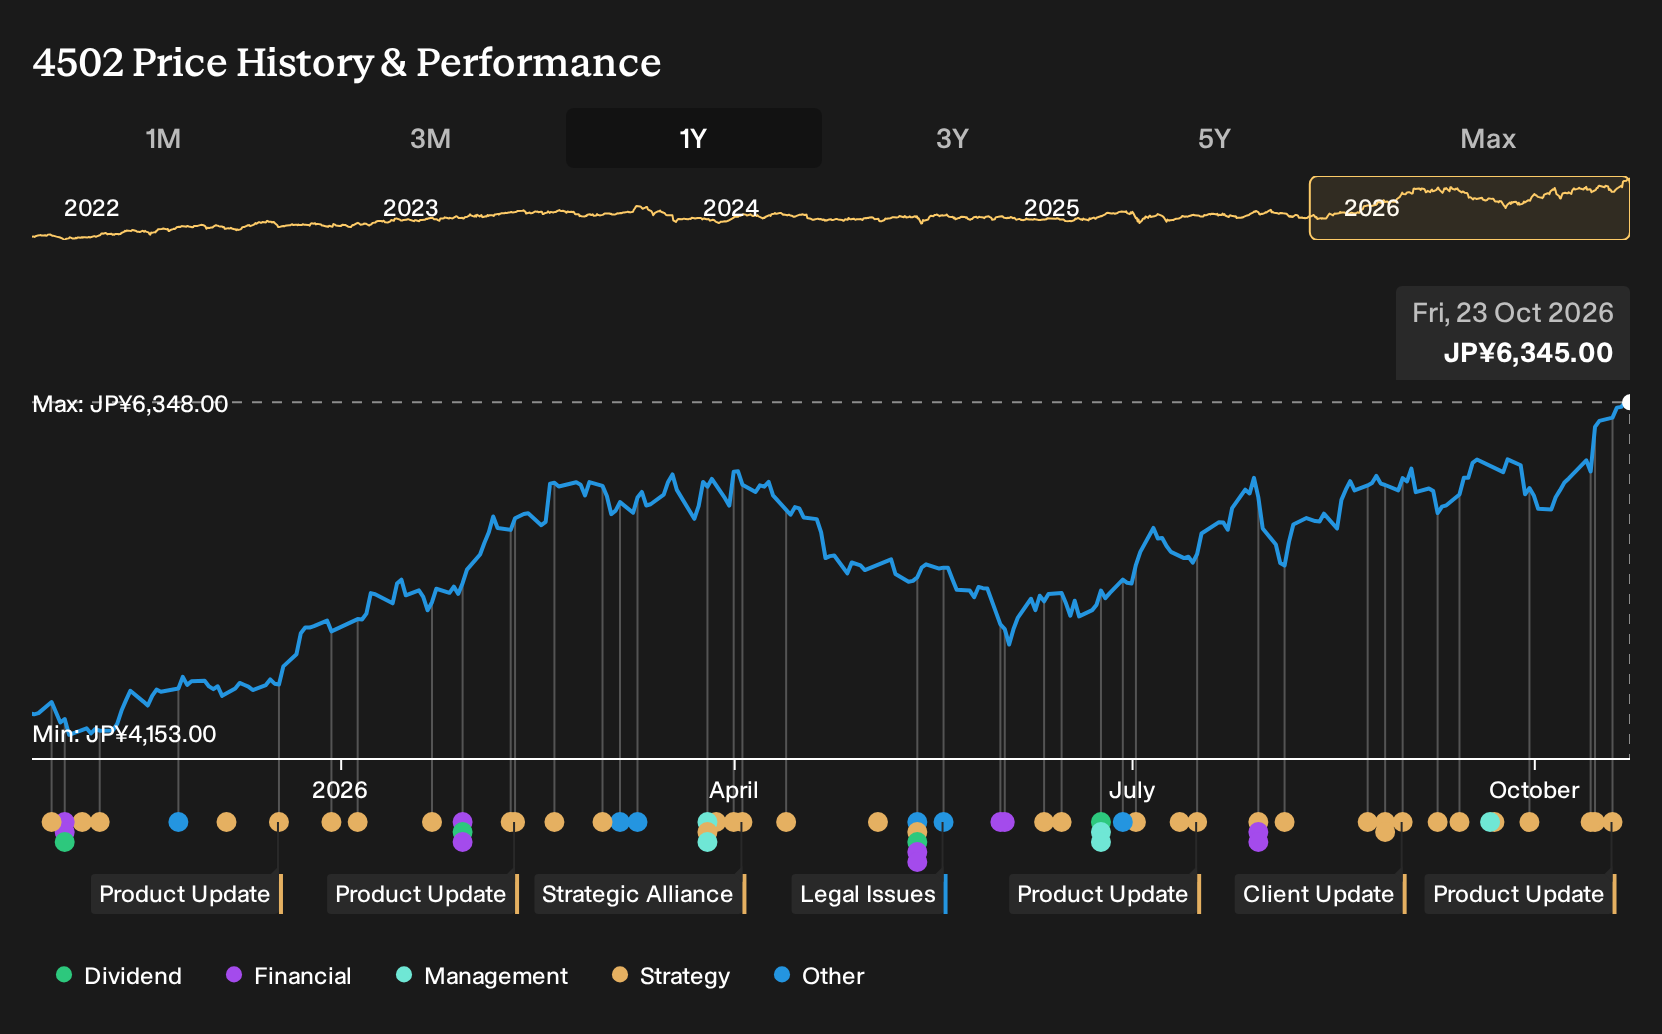
Uncover why Takeda Pharmaceutical's fair value indicates a 4% potential upside to its current price, a discount that could narrow quickly as sentiment adjusts.
Exploring Other Perspectives
Some analysts focus on a different risk for Takeda Pharmaceutical. They worry that orexin and TYK2 launches could demand heavy spending, while ENTYVIO and VYVANSE face pressure. The most cautious forecasters had pencilled in roughly ¥4,750.4b of revenue and ¥274.4b of earnings by 2029. That is far below consensus, and the new VERDICT data may prompt you to revisit both stories.
Explore 2 other Takeda Pharmaceutical fair value estimates, including one that suggests it could be worth just ¥6622.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Takeda Pharmaceutical research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Takeda Pharmaceutical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Takeda Pharmaceutical's overall financial health at a glance.
Looking for more Takeda Pharmaceutical style ideas?
Once you have a handle on Takeda Pharmaceutical, it often helps to compare it with other businesses that have different risk profiles and balance sheet setups.
- If you want potential upside with tighter budgets, look at smaller companies that still clear quality hurdles using our 1 elite penny stocks with strong financials.
- For investors who care most about resilient finances and steady execution, filter for businesses with strong cash positions and low leverage through the list of solid balance sheet and fundamentals (23 results).
- To widen your watchlist with lesser known opportunities that still pass fundamental checks, build a shortlist using the 72 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com