


- Recent UK economic data has improved, and investors now link that brighter backdrop to Sage Group's ability to support future cash generation.
- The discussion has shifted to how Sage Group's discounted cash flow valuation compares with its expected free cash flows under healthier UK conditions.
- This raises the question of how Sage Group's investment narrative might be reshaped by stronger UK economic data supporting its future cash flow outlook.
Compare Sage Group's cash flow story with a curated set of financially disciplined peers by scanning the 7 high quality undervalued stocks, which screens for quality and valuation support in one place.
Sage Group Investment Narrative Recap
To own Sage Group, you need to be comfortable with a story built around cloud subscription growth, deeper adoption of Sage Business Cloud and a gradual shift to AI enabled workflows. The recent UK data improves the backdrop but does not change the core near term catalyst, which is whether cloud native and AI tools can keep customer retention and new wins healthy.
The biggest near term risk still sits in execution. Monetising AI products such as Sage Copilot beyond modest contributions, holding growth against tough second half comparators and supporting buybacks while carrying higher debt levels all need to line up. Stronger macro data alone does not resolve those pressures.
Without fresh company specific announcements tied directly to this move, the most relevant reference point remains Sage Group's own cash flow and valuation work. The DCF based intrinsic value estimate of about £14.05 against a share price near £11.91 frames how much of the long term cash generation story the market is currently pricing in.
For you as an investor, that gap only matters if Sage Group continues to turn AI integration, international expansion of Intacct and X3 and regulatory pushes like Making Tax Digital into durable free cash flows. Any stumble in growth against those tougher upcoming comparators or a rethink of capital returns at around 2x leverage would quickly become the key catalyst instead.
What The Sage Group Cash Flow Path Implies
Sage Group's narrative projects £3.4b revenue and £584.6m earnings by 2029. This is based on an assumption of 9.0% yearly revenue growth and an earnings increase of about £199.6m from £385.0m today.
Uncover why Sage Group's fair value indicates a 4% potential downside to its current price, leaving little room for error.
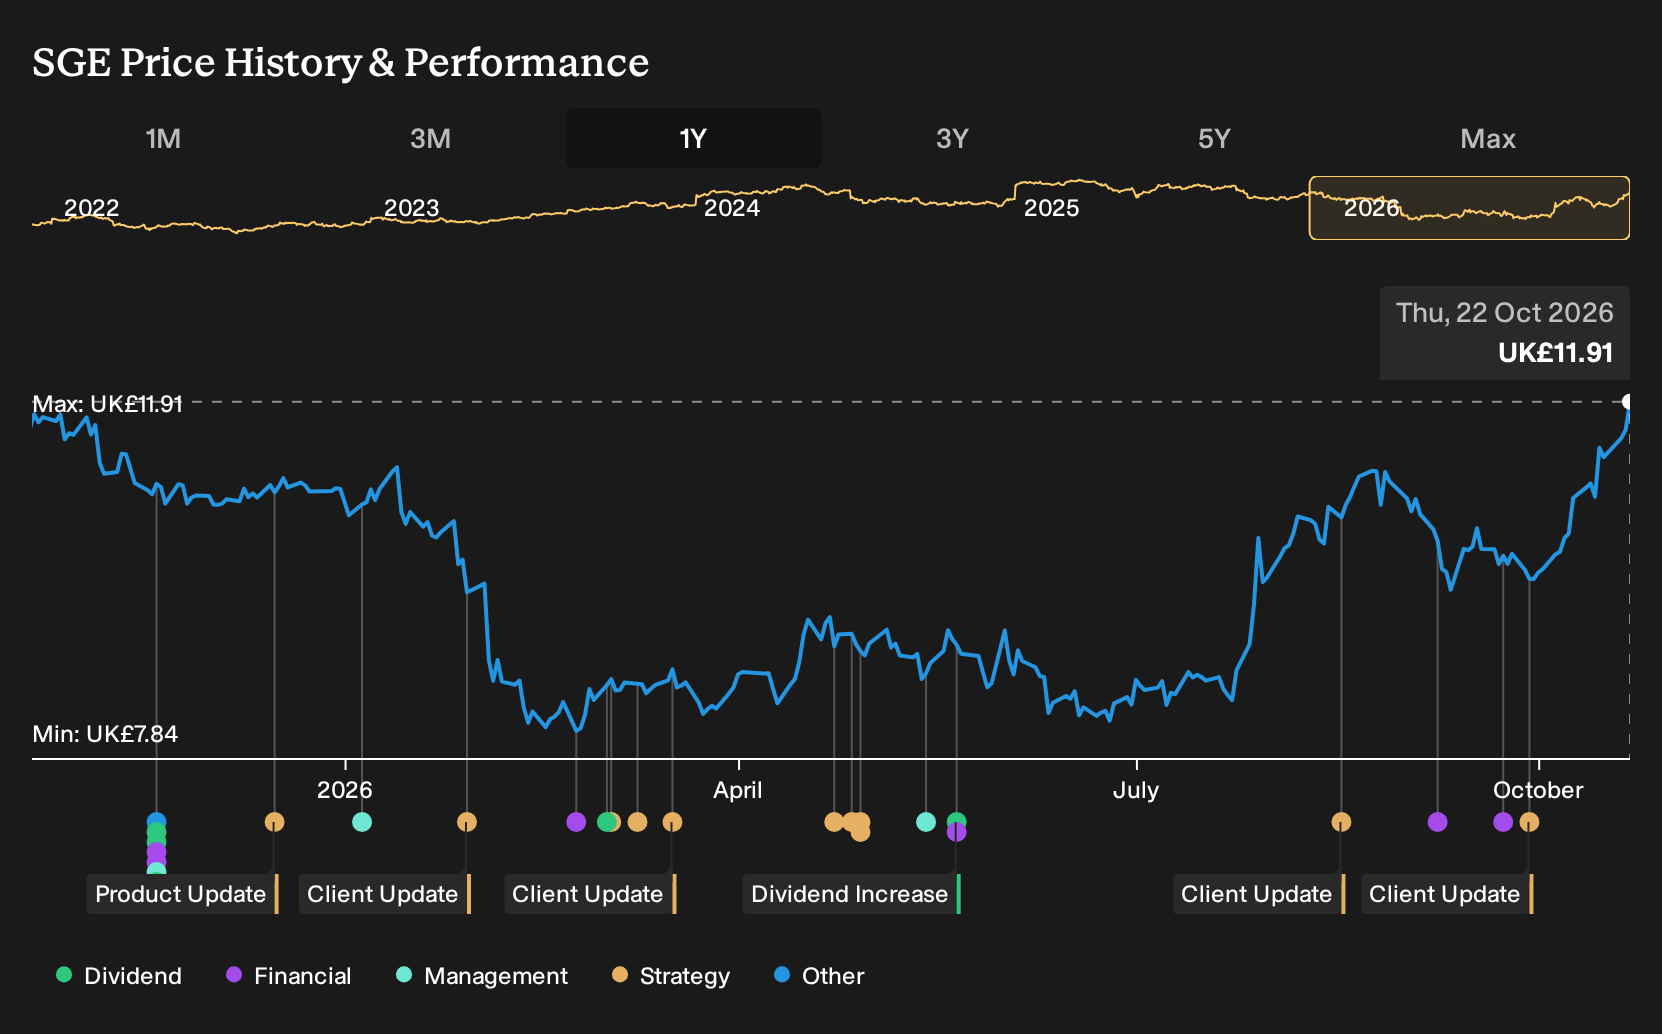
Exploring Other Perspectives
One alternate view puts Sage Group’s AI agent rollout at the centre of the story. Bullish analysts saw room for revenue to reach about £3.7b and earnings of £615.0m by 2029, compared with consensus at £3.4b and £584.6m. Those projections predate the latest UK data, so readers should expect opinions to shift and should explore several angles independently.
Explore 4 other Sage Group fair value estimates, including one that suggests as much as 18% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Sage Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sage Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sage Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sage Group?
Once you have a view on Sage Group, it can help to compare that thesis against a wider watchlist. The Simply Wall St Screener lets you filter for the traits you actually care about, whether that is balance sheet strength, income potential or valuation support.
- If you care most about downside protection and capital resilience, start with a 4 resilient stocks with low risk scores that score well on stability and risk controls.
- For investors who want income to play a bigger role in total returns, consider a 4 dividend fortresses that combine yield with business durability.
- If your priority is financial strength backing up the equity story, review a list of solid balance sheet and fundamentals (9 results) so you can focus on companies with room to absorb shocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com