


Merck (MRK) is back in the spotlight after detailed Phase 3 INTerpath-001 data showed its personalized melanoma vaccine intismeran, combined with Keytruda, cut recurrence or death risk compared with Keytruda alone.
For context, Merck shares now trade at US$147.24, after a 1-day share price return that declined 1.76%, while the 90-day share price return of 12.34% and year-to-date gain of 38.32% point to momentum that has been building over 2026. Total shareholder return tells an even richer story, with a 1-year outcome of 73.85% and a 5-year figure of 98.24%. The recent vaccine data leak, European Commission approval for additional Keytruda uses, and upcoming earnings have all contributed to shifting expectations around Merck’s future cancer portfolio and risk profile.
Scan how Merck’s cancer catalyst compares with other potential breakout healthcare plays on the 36 healthcare AI stocks list.
Merck now has a high profile cancer franchise, a fresh melanoma readout and a US$369.8b market value moving in tandem. The next step is harder. Does that package actually justify today’s valuation?
Most Popular Narrative: 5% Undervalued
Merck’s most followed valuation narrative pegs fair value at $155.68, a touch above the last close at $147.24. This frames today’s melanoma news against a pipeline that many investors already see as cushioning the eventual Keytruda patent cliff.
Merck plans to bring over 20 new growth drivers to market in the coming years, and management now points to more than US$70b in non risk adjusted mid 2030s revenue potential from this next generation portfolio. This could support revenue and earnings resilience through and after the KEYTRUDA loss of exclusivity. The expanding oncology franchise that now includes sac TMT across 17 Phase III trials, the growing WELIREG plus LENVIMA combination, and the planned broadening of the intismeran mRNA cancer vaccine beyond melanoma introduces multiple potential new treatment options that could help offset future KEYTRUDA revenue pressure and support long term revenue growth.
See why 418 investors see Merck as 5% undervalued.
Result: Fair Value of $155.68 (UNDERVALUED)
Still, the Merck story can shift quickly if the wider oncology pipeline stumbles in late stage trials or if fresh business development deals weigh more heavily on earnings than planned.
Find out about the key risks to this Merck narrative.
Another View: Merck Through The P/E Lens
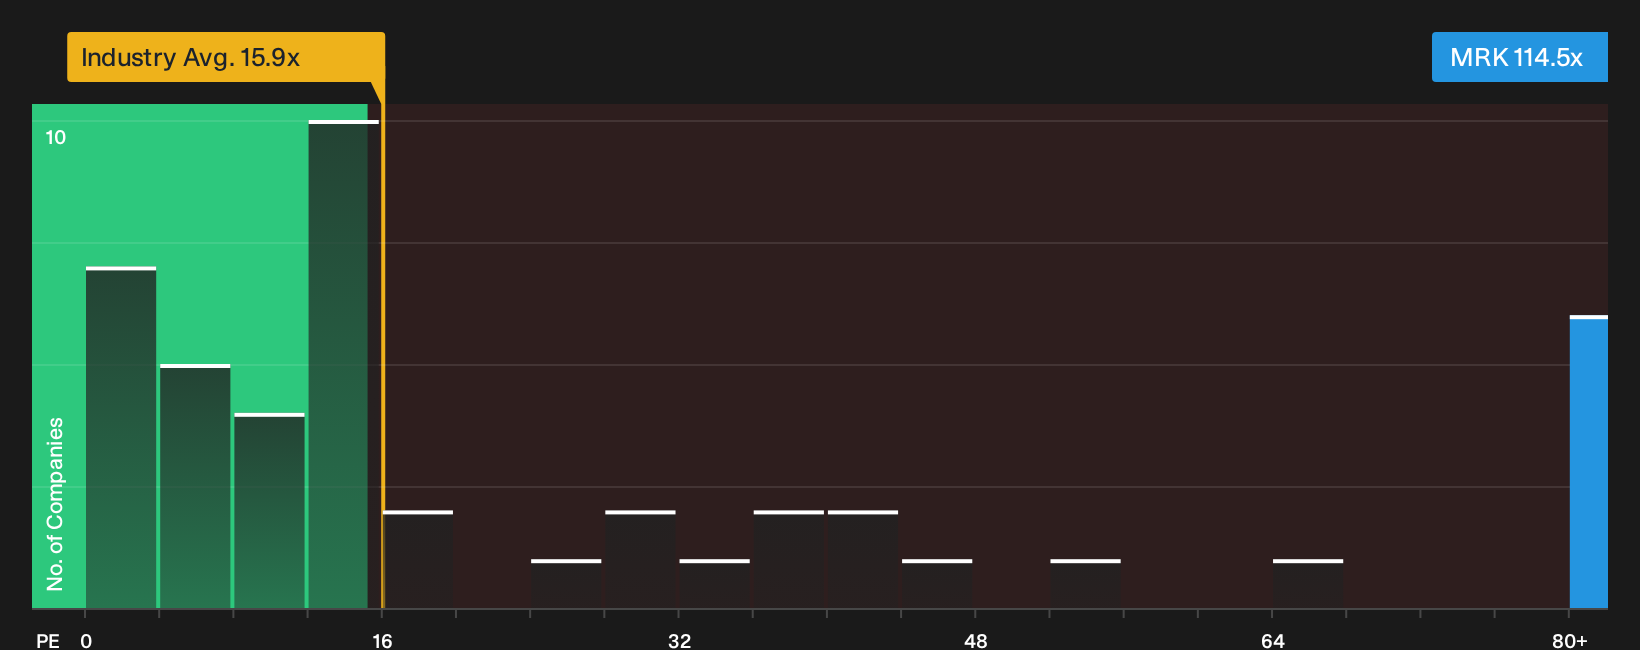
Merck screens very differently when you stop looking at fair value models and focus on its P/E ratio. The stock trades on 114.5x earnings, compared with 34.4x for peers and a fair ratio estimate of 50.7x. That is a rich premium. Is the melanoma vaccine and broader pipeline enough to justify paying up this far for growth that is still playing out in the lab rather than the income statement?
Investors weighing these conflicting signals may want to see what the numbers imply when that rich earnings multiple is pulled apart in more detail and then stacked against both peers and the fair ratio the market could eventually move toward, in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Merck’s valuation and cancer pipeline can feel like a lot to process. Move quickly to review the underlying metrics, stress test the risks and rewards for yourself, and then weigh the balance using the 2 key rewards and 5 important warning signs.
Looking for more Merck investment ideas?
If Merck has your attention, do not stop here. Use the Simply Wall Street Screener to quickly surface fresh opportunities that match your risk and return preferences.
- Hunt for mispriced quality by zeroing in on companies that pass strict valuation and fundamentals filters through the 29 high quality undervalued stocks.
- Identify potential income ideas by scanning for companies with consistent payments and higher yields in the 6 dividend fortresses.
- Prioritize resilience by focusing on businesses with robust finances using the list of solid balance sheet and fundamentals (26 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com