


- Columbia Banking System reported third quarter 2026 net income of US$220 million on net interest income of US$615 million, with basic and diluted EPS from continuing operations of US$0.78 and total net charge offs of US$28 million.
- The board approved a new US$1.2b share repurchase plan. The company also reported that earlier buybacks had already retired 8.02% of shares, which directly affects per share metrics and capital management flexibility.
- The next area of focus will be how Columbia Banking System’s investment narrative is shaped by this quarter and the new buyback authorization.
Columbia Banking System Investment Narrative Recap
To own Columbia Banking System, you need to be comfortable with a regional bank that leans heavily into Western U.S. markets, relationship commercial lending, and steady balance sheet reshaping. The short term swing factor is whether it can keep earning assets tilted toward higher yielding relationship loans while holding funding costs in check after this quarter’s strong net interest income.
The key risk right now sits on the credit and regional side. Columbia Banking System reported higher total net charge offs of US$28 million, and any pressure in its Western footprint could lift that further. If credit costs rise or deposit growth slows, the current operating momentum and capital return plans would feel less powerful.
The fresh US$1.2b share repurchase authorization is the announcement that ties this quarter together. Management has already retired 8.02% of shares under the prior plan, which directly affects per share figures and leaves more of Columbia Banking System’s earnings and dividend stream spread over a smaller base.
For you, the key question is whether the bank can keep funding that buyback from a healthy core business while staying ahead of regional and credit risk. If earnings, capital ratios and deposit trends hold up against those pressures, the repurchase program can remain a meaningful catalyst alongside ongoing loan remixing and fee income build out.
Columbia Banking System's analyst narrative points to revenue of US$3.0b and earnings of US$948.5 million by 2029, based on an assumed 6.0% yearly revenue growth rate and an earnings increase of about US$239.5 million from the current US$709.0 million base.
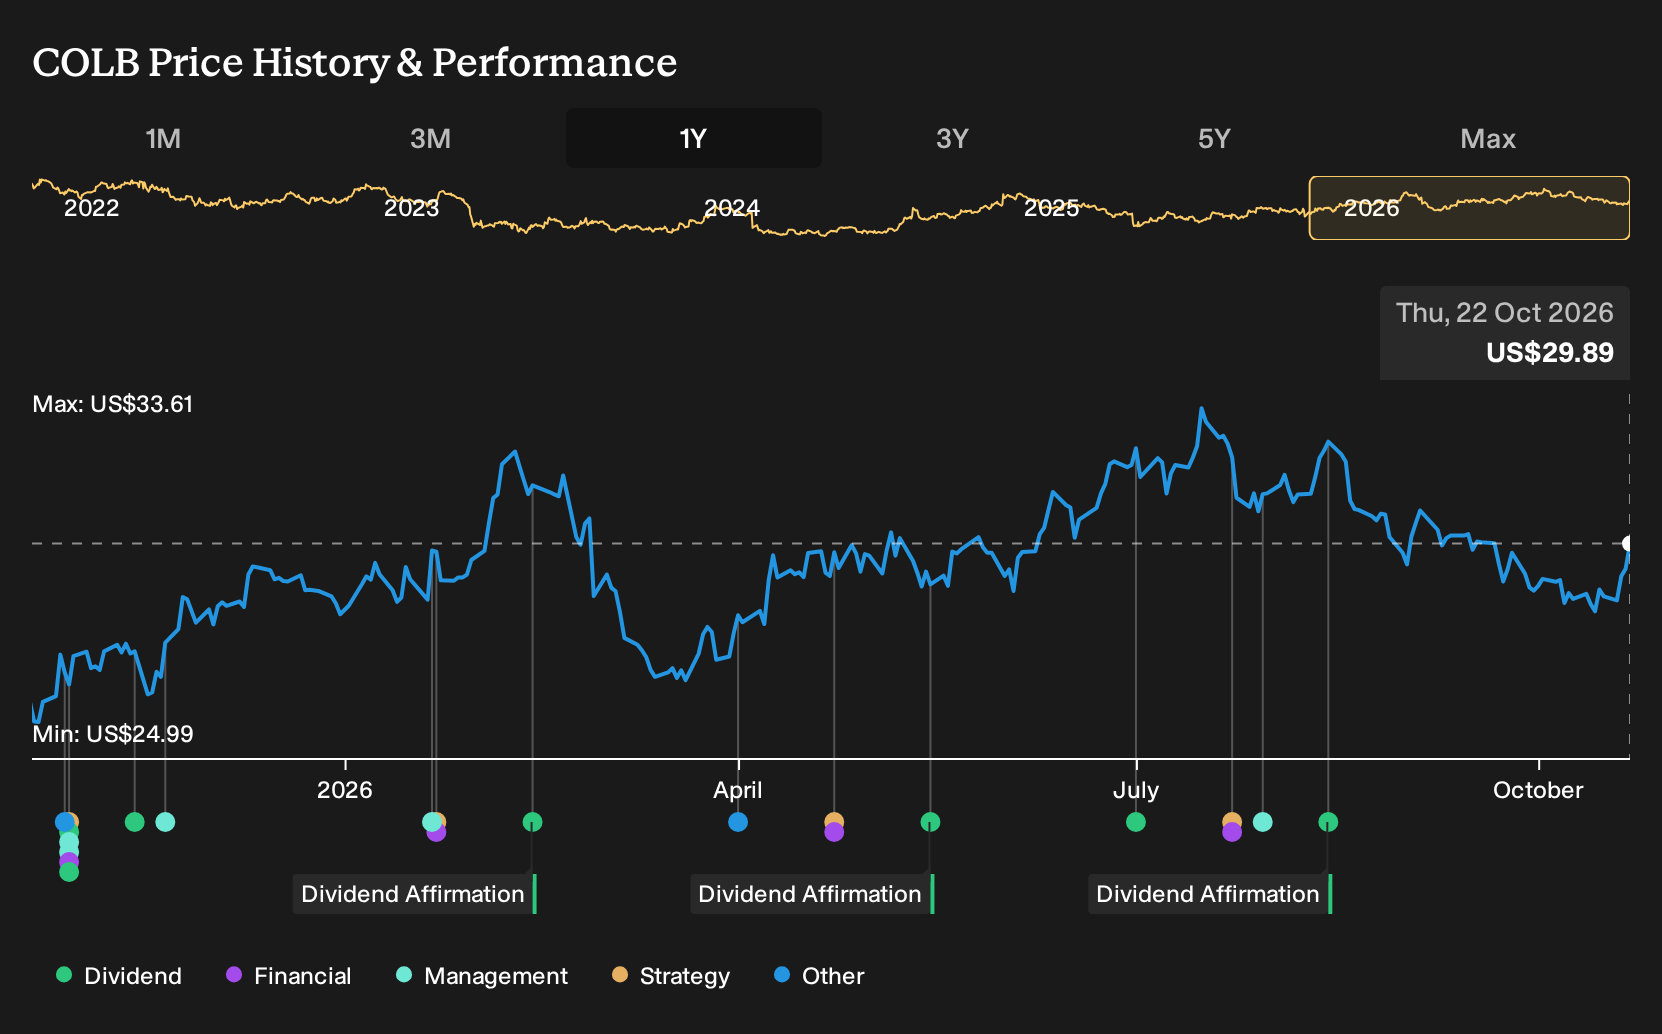
Discover why Columbia Banking System's fair value points to a 13% potential upside to its current price before that discount begins to close.
Exploring Other Perspectives
The three fair value estimates from the Simply Wall St Community cluster between US$33.33 and US$50.37, which already shows how far apart retail views on Columbia Banking System can run. When you set that beside rising net charge offs and a large, open ended buyback, you get real debate about earnings resilience. Explore more of those viewpoints before deciding how this story fits in your portfolio.
Explore 2 other Columbia Banking System fair value estimates, including one that suggests as much as 69% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Columbia Banking System research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Columbia Banking System. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Columbia Banking System's overall financial health at a glance.
Looking for more investment ideas beyond Columbia Banking System?
Once you are comfortable with how Columbia Banking System fits your portfolio, it can be useful to line it up against other listed businesses with very different risk and return profiles. A broad watchlist can help you avoid anchoring too heavily on a single story and gives you fresh benchmarks for quality, balance sheet strength, and income potential.
- If you are hunting for resilient balance sheets and clear fundamentals, you can start with a list of solid balance sheet and fundamentals (26 results) that helps you compare Columbia Banking System to peers with similar financial discipline.
- Income focused investors who want yield alongside durability can review a curated set of 6 dividend fortresses that may complement or contrast Columbia Banking System's payout profile.
- For those who like exploring earlier stage opportunities before they become widely followed, you can sift through a 20 high quality undiscovered gems and see how these prospects line up against what you see in Columbia Banking System.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com