


Archer-Daniels-Midland (ADM) has become more interesting for investors after a fresh mix of cost discipline and policy support. The company is cutting expenses through efficiency projects, and biofuel tax credits offer clearer revenue visibility.
Recent price action has been choppy, with Archer-Daniels-Midland’s share price return down 7.1% over the past 90 days, even after a 0.6% gain in the last session. However, the year-to-date share price return of 35.2% and 1-year total shareholder return of 31.5% suggest that longer term momentum has been much stronger than the latest pullback.
Scan for other agriculture and biofuel players pursuing similar cost discipline and policy tailwinds with our curated 29 high quality undervalued stocks, which may offer a mix of quality and value.
Archer-Daniels-Midland now trades only slightly below analyst targets yet at a sizeable intrinsic discount, after a sharp run and recent wobble. Is that a sensible safety margin, or is the market flagging real risks?
Most Popular Narrative: 30% Undervalued
On the most followed view, Archer-Daniels-Midland screens as undervalued, with a fair value of $80.10 against a last close of $79.84. This leaves only a slim gap between narrative fair value and the market price but still leans to a discount when paired with an intrinsic value estimate that is materially higher.
Enterprise-wide productivity and cost simplification initiatives, including the 3 to 5 year program targeting US$500 million to US$750 million of cumulative savings and early progress such as a roughly 25% reduction in accounts payable cost per transaction, are aimed at structurally lowering Archer-Daniels-Midland’s cost base and supporting operating earnings and return on invested capital.
See why 101 investors see Archer-Daniels-Midland as 0% undervalued.
Result: Fair Value of $80.10 (UNDERVALUED)
Still, the Archer-Daniels-Midland story could be knocked off course if sweetener margins stay weak, or if governance and litigation costs keep dragging on sentiment.
Find out about the key risks to this Archer-Daniels-Midland narrative.
Another View: Archer-Daniels-Midland On Earnings Ratios
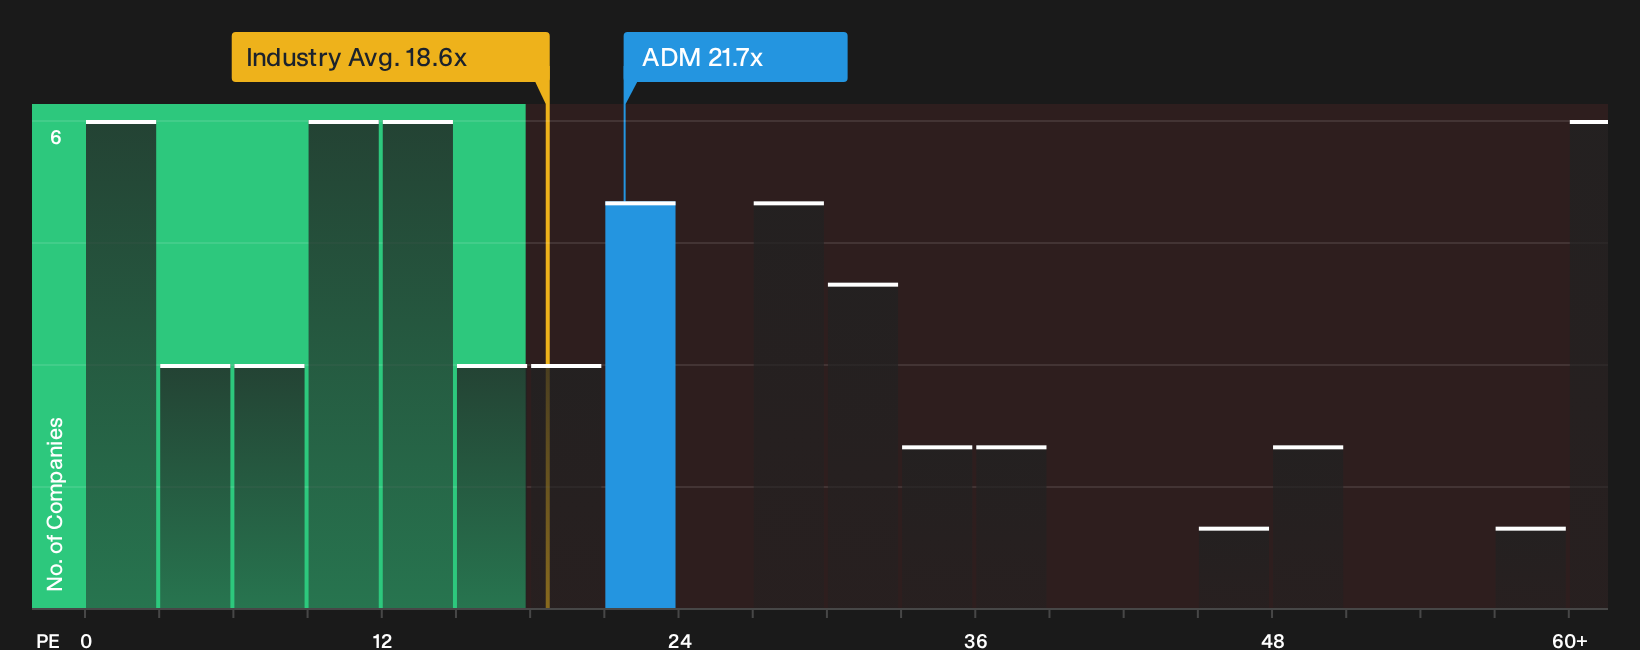
The SWS DCF workup points to Archer-Daniels-Midland trading well below an estimated future cash flow value of $116.09, which aligns with the undervalued story. On earnings ratios though, ADM changes shape, with a current P/E of 21.7x that raises a different kind of question for investors.
That 21.7x multiple sits above both the US Food sector at 18.6x and an estimated fair ratio of 17.5x, while only slightly under the 22.1x peer average. The gap suggests the market already pays up for ADM’s earnings stream, which leads to the question of how much room is really left if sentiment or cash flow assumptions shift.
To unpack what this P/E premium might mean for upside, downside and patience, take a closer look at the valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Archer-Daniels-Midland is mixed, so it makes sense to move fast, check the underlying data, and decide where you stand. To see what the optimism is about and which potential upsides analysts are flagging, review the 3 key rewards.
Looking for more Archer-Daniels-Midland investment ideas?
If Archer-Daniels-Midland has your attention, do not stop at one ticker. Use focused screeners to surface opportunities you would not usually spot on a watchlist.
- Target resilience by filtering companies with robust finances and conservative leverage through the 30 resilient stocks with low risk scores.
- Spot potential mispricings early by scanning for quality businesses trading below implied value using the 20 high quality undiscovered gems.
- Zero in on financial strength by hunting for companies with sturdy balance sheets and sound fundamentals via the list of solid balance sheet and fundamentals (26 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com