


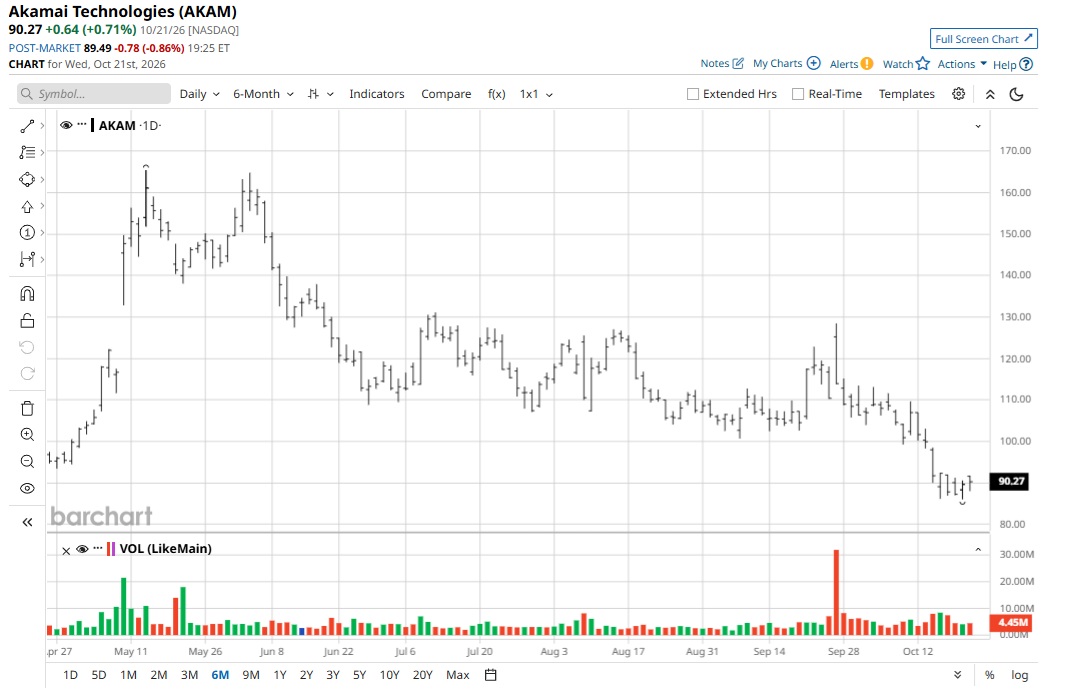
Akamai Technologies (AKAM) stock traded at a 52-week high of $165.45 in the first quarter of the year, but entered a downtrend on the back of growth concerns. However, this was alleviated when the company announced a massive deal with Anthropic on Sept. 24.
According to Akamai, the “deal is worth $11.6B over seven years and could be worth as much as $20B if certain conditions are met.” As part of the deal, Akamai “gave warrants to Anthropic that represent 7.7M shares of its Series B preferred stock.”
The initial rally on the back of this deal fizzled out with the technology sector witnessing some correction. As AKAM stock trended lower again, Raymond James analyst Frank Louthan upgraded the share to “Strong Buy” with a price target of $170.
According to Frank, the 'AI is Dead' trade was fueled by credit risks and fears of higher rates. The renewed correction provides a “compelling long-term opportunity.” This positive outlook is backed by the big contract from “Anthropic—a high-profile AI frontier model company.”
While the macroeconomic risk persists, coupled with higher interest rates, a significant correction from highs makes AKAM stock attractive.
About Akamai Stock
Headquartered in Cambridge, Akamai Technologies is a developer and provider of solutions for global enterprises to build, secure, and accelerate their applications and digital experiences.
The company provides solutions in three core offerings: Security, Cloud Computing, and Delivery. For the first half of FY26, Akamai reported 55% of revenue from security, 36.1% from cloud computing, and 8.9% from the delivery segment.
Further, for the same period, 50.3% of revenue was from the United States and 49.7% from international markets. This is indicative of well-diversified revenue from a geographic perspective. In the last three financial years, Akamai’s investment in R&D has averaged almost 12% of revenue. A strong focus on R&D is likely to support growth.
However, for the first half of FY26, Akamai reported muted revenue growth of 5% on a year-on-year basis to $1.1 billion. It’s therefore not surprising that AKAM stock has declined by 8% in the last six months.
Muted Growth, but Strong Fundamentals
Akamai has reported muted top-line growth in the first half of 2026. With the Anthropic contract, growth will likely accelerate in the coming years. Further, in the first half of FY26, the company has signed contracts worth $2.8 billion. These contracts increasingly position Akamai as an important AI infrastructure provider.
It’s also worth noting that the company has robust fundamentals. As of Q2, Akamai reported a cash buffer of $4.6 billion. The company’s operating cash flow for Q2 was $326 million, which implies an annualized cash flow potential of $1.3 billion.
Therefore, strong order intake, coupled with healthy credit metrics, positions Akamai for growth acceleration. Another important point to note is that the company derives almost 50% of revenue from international markets. There is ample headroom for growth outside the United States as AI infrastructure buildout accelerates outside North America.
From the perspective of shareholder value creation, Akamai purchased $410 million in common stock in Q2. Aggressive share purchases will likely continue as cash flows swell.
What Do Analysts Say About AKAM Stock?
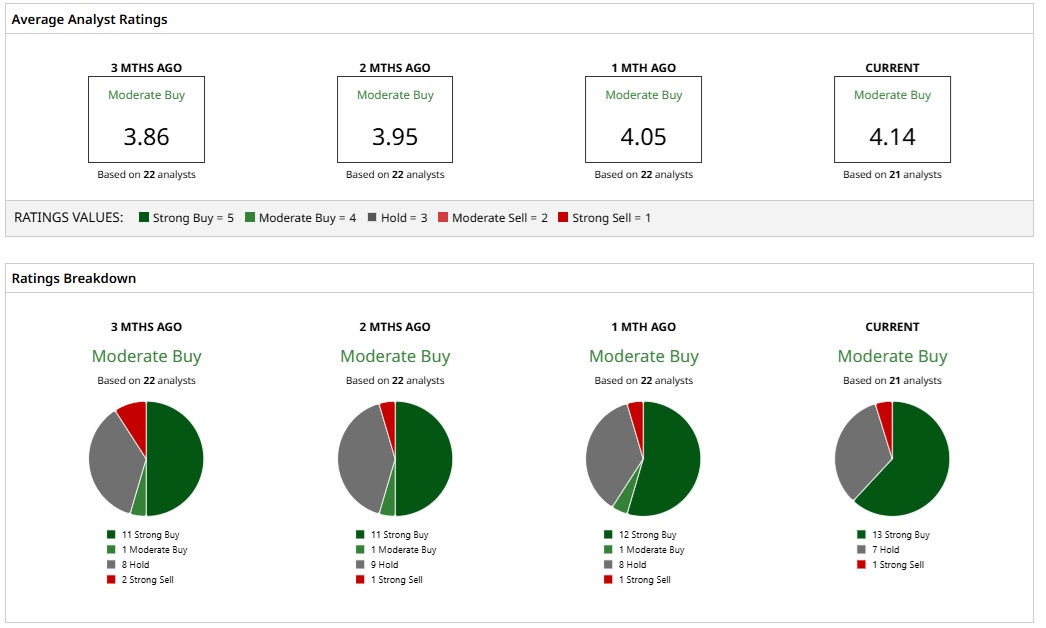
Based on 21 analysts with coverage, AKAM stock has a consensus “Moderate Buy” rating. While 13 analysts have a “Strong Buy” rating for the stock, seven have a “Hold,” and one analyst has a “Strong Sell” rating.
The mean price target of $159.85 represents potential upside of 77% from current levels. Further, the most bullish price target of $225 suggests that AKAM stock could climb as much as 149.3% from here.
On the date of publication, Faisal Humayun Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.