


San Diego, California-based Sempra (SRE), with a market capitalization of approximately $54.6 billion, is an energy infrastructure holding company that owns regulated utilities in California and Texas, including Oncor, San Diego Gas & Electric, and Southern California Gas Company. It also holds an ownership interest in liquefied natural gas (LNG) export infrastructure, supporting reliable energy delivery and long-term growth.
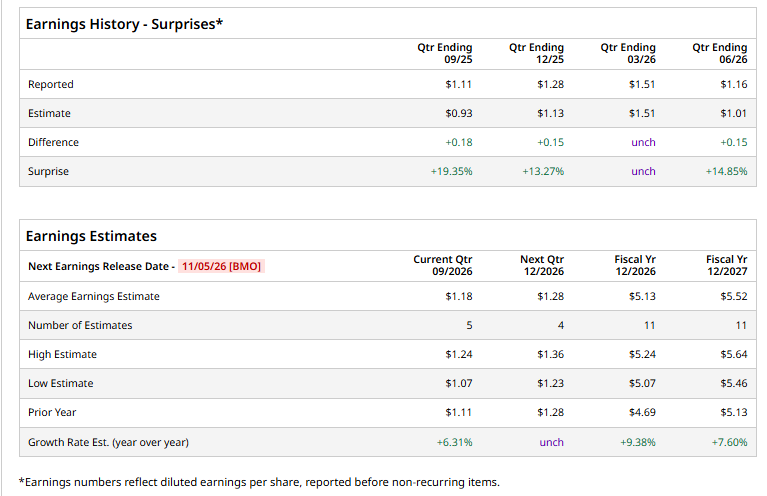
SRE is scheduled to report its Q3 fiscal 2026 earnings on Thursday, November 5, 2026, before the market opens. Ahead of the release, analysts expect diluted EPS of $1.18, up 6.3% from $1.11 in the year-ago quarter. Notably, SRE has met or exceeded Wall Street’s EPS estimates in each of the past four quarters.
For fiscal 2026, analysts expect SRE to report EPS of $5.13, representing a 9.4% increase from $4.69 in fiscal 2025. Furthermore, EPS is projected to rise another 7.6% year over year to $5.52 in fiscal 2027.
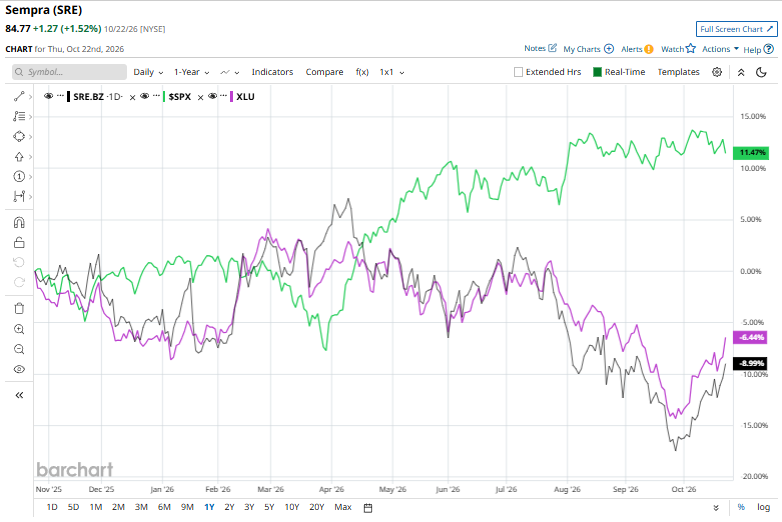
Over the past 52 weeks, SRE stock has climbed 7.9%, lagging the S&P 500 Index ($SPX), which returned 14.4%. However, SRE outperformed the State Street Utilities Select Sector SPDR ETF (XLU), which declined 5.2% over the same period.
Sempra’s mixed second-quarter results offer context for its stock’s relative underperformance. In its Aug. 6 report, the company posted adjusted earnings of $1.16 per share, exceeding analysts’ expectations of $1.01. However, revenue totaled $3 billion, falling short of the $3.22 billion forecast. Sempra also projected full-year earnings of $4.80 to $5.30 per share.
On a more positive note, Sempra’s subsidiary, Sempra Infrastructure, signed a 20-year LNG supply agreement with Petróleo Brasileiro S.A. - Petrobras (PBR) on September 14, 2026. Under the agreement, Sempra Infrastructure will supply approximately 0.8 million tonnes of LNG annually from the Port Arthur LNG Phase 2 project. The deal expands Sempra Infrastructure’s global customer base and may improve long-term revenue visibility, with the project’s third and fourth trains expected to begin commercial operations in 2030 and 2031, respectively.
Analysts remain somewhat bullish on SRE, with a consensus "Moderate Buy" rating. Of the 21 analysts covering the stock, 14 recommend a "Strong Buy," one rates it a "Moderate Buy," and six recommend a "Hold." SRE’s average price target of $97.66 implies a 15.2% premium over the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.