


As the Canadian market navigates a landscape marked by fluctuating interest rates and economic uncertainties, investors are increasingly focused on growth opportunities that demonstrate resilience and potential for substantial earnings expansion. In this context, stocks with high insider ownership can be particularly appealing, as they often indicate management’s confidence in the company’s future performance.
Top 10 Growth Companies With High Insider Ownership In Canada
| Name | Insider Ownership | Earnings Growth |
| ROK Resources (TSXV:ROK) | 16.9% | 128.9% |
| Propel Holdings (TSX:PRL) | 25.7% | 33.7% |
| LSL Pharma Group (TSXV:LSL) | 24.5% | 57.0% |
| Hammond Power Solutions (TSX:HPS.A) | 27.1% | 32.1% |
| Electrovaya (TSX:ELVA) | 34.9% | 41.2% |
| Cizzle Brands (NEOE:CZZL) | 13.2% | 90.4% |
| CHAR Technologies (TSXV:YES) | 21.1% | 83.5% |
| CEMATRIX (TSX:CEMX) | 10.7% | 28.6% |
| Cambria Gold Mines (TSXV:CAMB) | 12% | 85.3% |
| Abcourt Mines (TSXV:ABI) | 33.2% | 46.5% |
We're going to check out a few of the best picks from our screener tool.
Colliers International Group (TSX:CIGI)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Colliers International Group Inc. is a global provider of commercial real estate, engineering, and investment management solutions, with a market cap of CA$6.67 billion.
Operations: The company's revenue is primarily derived from its Commercial Real Estate segment at $3.49 billion, followed by Engineering at $1.90 billion, and Investment Management contributing $562 million.
Insider Ownership: 14.7%
Earnings Growth Forecast: 17% p.a.
Colliers International Group is positioned for growth, with earnings projected to rise 17% annually, outpacing the Canadian market. Revenue growth is also expected to exceed market rates at 8.3% per year. Despite not having recent insider trading activity, Colliers trades at a significant discount to its estimated fair value and has a robust forecasted return on equity of 23.4%. Recent executive appointments aim to enhance strategic leadership and operational performance across key regions.
- Take a closer look at Colliers International Group's potential here in our earnings growth report.
- Our valuation report unveils the possibility Colliers International Group's shares may be trading at a premium.
Firan Technology Group (TSX:FTG)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Firan Technology Group Corporation manufactures and sells aerospace and defense electronic products and subsystems across Canada, the United States, Asia, Europe, China, and internationally with a market cap of CA$873.52 million.
Operations: The company generates revenue from its Circuits segment, which accounts for CA$141.41 million, and its Aerospace segment, contributing CA$77.64 million.
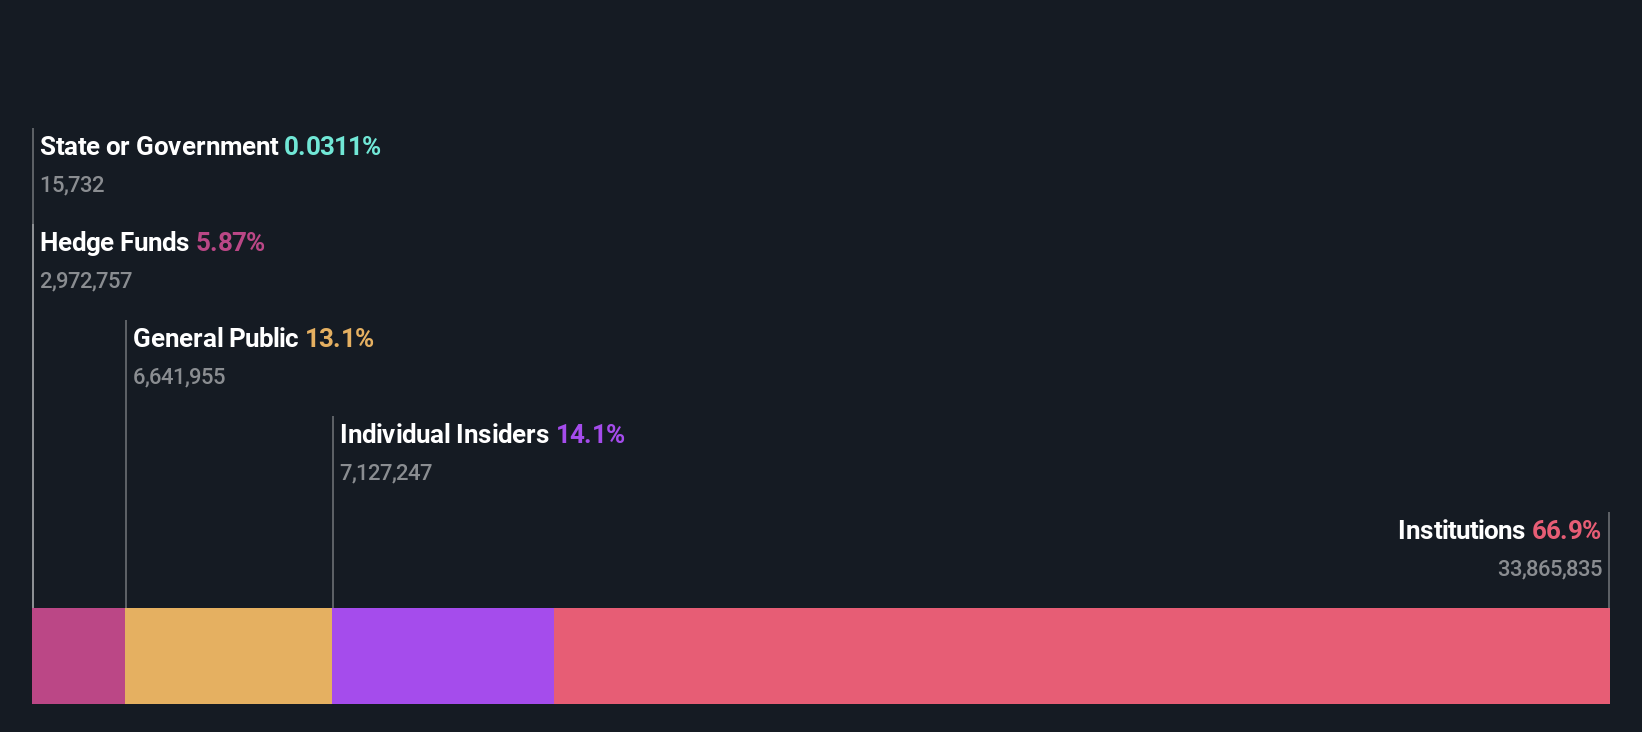
Insider Ownership: 12.9%
Earnings Growth Forecast: 16.8% p.a.
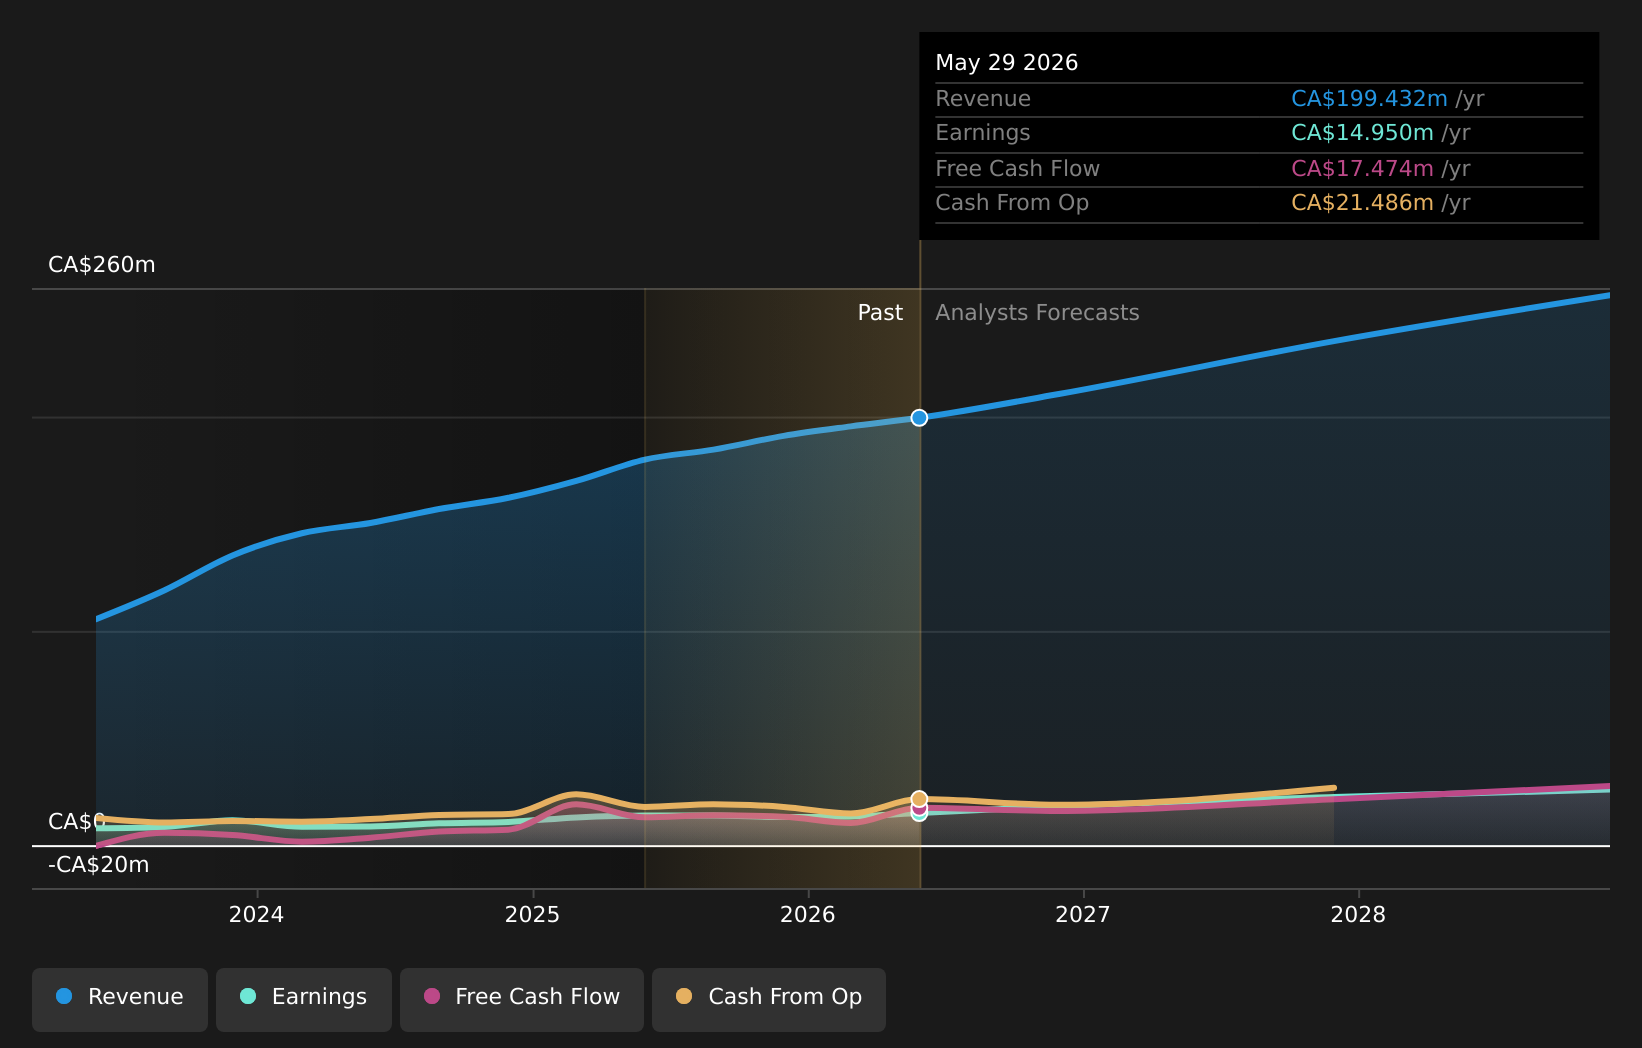
Firan Technology Group exhibits promising growth potential, with earnings having surged 60% over the past year and forecasts indicating a continued annual increase of 16.8%, surpassing the Canadian market average. The company's revenue is also expected to grow at a rate of 12.3% per year, faster than the broader market's 4.5%. Recent earnings results showed significant improvement, with Q3 sales reaching C$64.1 million and net income rising to C$10 million from C$2.77 million last year.
- Delve into the full analysis future growth report here for a deeper understanding of Firan Technology Group.
- Upon reviewing our latest valuation report, Firan Technology Group's share price might be too optimistic.
Kits Eyecare (TSX:KITS)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Kits Eyecare Ltd. operates a digital eyecare platform in the United States and Canada, with a market capitalization of CA$580.83 million.
Operations: The company's revenue from the sale of eyewear products is CA$222.18 million.
Insider Ownership: 26.7%
Earnings Growth Forecast: 40.8% p.a.
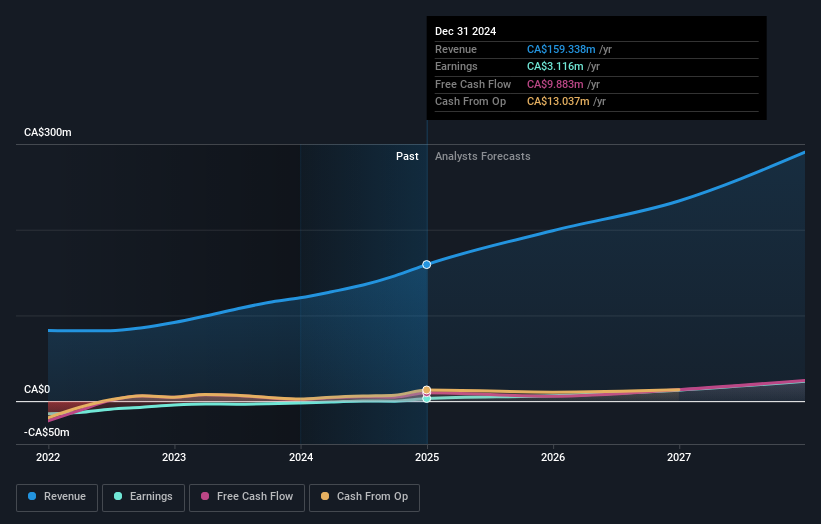
Kits Eyecare demonstrates strong growth potential with earnings projected to rise significantly at 40.81% annually, outpacing the Canadian market's 10.9%. Revenue is expected to grow at 14.6% per year, exceeding the market average of 4.5%. Recent insider activity shows substantial buying over selling in the past three months, indicating confidence in its trajectory. The company reported improved Q2 results with sales of C$58.43 million and net income of C$1.46 million compared to a loss last year.
- Dive into the specifics of Kits Eyecare here with our thorough growth forecast report.
- Our valuation report here indicates Kits Eyecare may be overvalued.
Where To Now?
- Discover the full array of 53 Fast Growing TSX Companies With High Insider Ownership right here.
- Searching for a Fresh Perspective? Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com