


- bioMérieux reported that its BIOFIRE SPOTFIRE Vaginitis Panel received both FDA 510(k) clearance and a CLIA waiver, enabling rapid multiplex PCR testing for eight vaginitis pathogens at the point of care using self collected or clinician collected swabs.
- This first rapid molecular vaginitis test extends bioMérieux’s SPOTFIRE menu beyond respiratory and sore throat panels and is intended to deepen reagent usage on an existing modular installed base across family practices, urgent care clinics, and OB/GYN offices.
- The next step is to examine how bioMérieux’s new CLIA waived, rapid vaginitis panel could reshape the investment narrative around SPOTFIRE utilization.
bioMérieux Investment Narrative Recap
For bioMérieux, the core belief is that BIOFIRE and SPOTFIRE reagent usage, industrial applications, and GO•28 efficiency gains can keep offsetting weaker instrument demand, softer respiratory testing and pressure in China. The new CLIA waived SPOTFIRE vaginitis panel fits cleanly into that story by adding another non respiratory assay that can run on an already large installed base.
The key near term swing factor is how consistently SPOTFIRE reagent volumes build, given prior concern around volatility in placements and expiring pandemic era contracts. The biggest risk remains a mix of weaker instruments, ongoing China softness and higher U.S. tariffs, and this new panel on its own does not remove those pressures.
The dual FDA 510(k) clearance and CLIA waiver for the BIOFIRE SPOTFIRE Vaginitis Panel looks most relevant because it speaks directly to syndromic growth and reagent intensity. A CLIA waiver allows non lab clinicians to run the test in family practices, urgent care and OB/GYN offices, which ties neatly into the push for broader point of care usage on SPOTFIRE.
For catalysts, the key question is whether more non respiratory cartridges like this can keep reagent growth closer to the roughly 40% SPOTFIRE reagent increase reported in the second quarter of 2026, even if instruments stay weaker. Execution risk sits in training non lab staff, managing turnaround times at scale, and making sure pricing still supports GO•28 margin ambitions in the face of higher U.S. tariffs and a slower China business.
How the SPOTFIRE Vaginitis Panel Fits Into bioMérieux’s Consensus Story
Analysts looking at bioMérieux are effectively asking whether products like the BIOFIRE SPOTFIRE Vaginitis Panel can support steady expansion in testing volume while headwinds in instruments and China continue. The consensus currently assumes revenue increases of 5.4% per year for the next three years, which implies a measured build rather than a sprint, with syndromic and point of care menus expected to carry more of the load.
Earnings expectations already bake in higher profitability. Forecasts point to earnings of €586.7 million by 2029, compared with €462.6 million today, which is an increase of about €124 million. That move is paired with an assumed margin shift from 11.6% to 12.5% over three years, so every extra test on SPOTFIRE, including the vaginitis panel, matters more to the bottom line than it would have a few years ago.
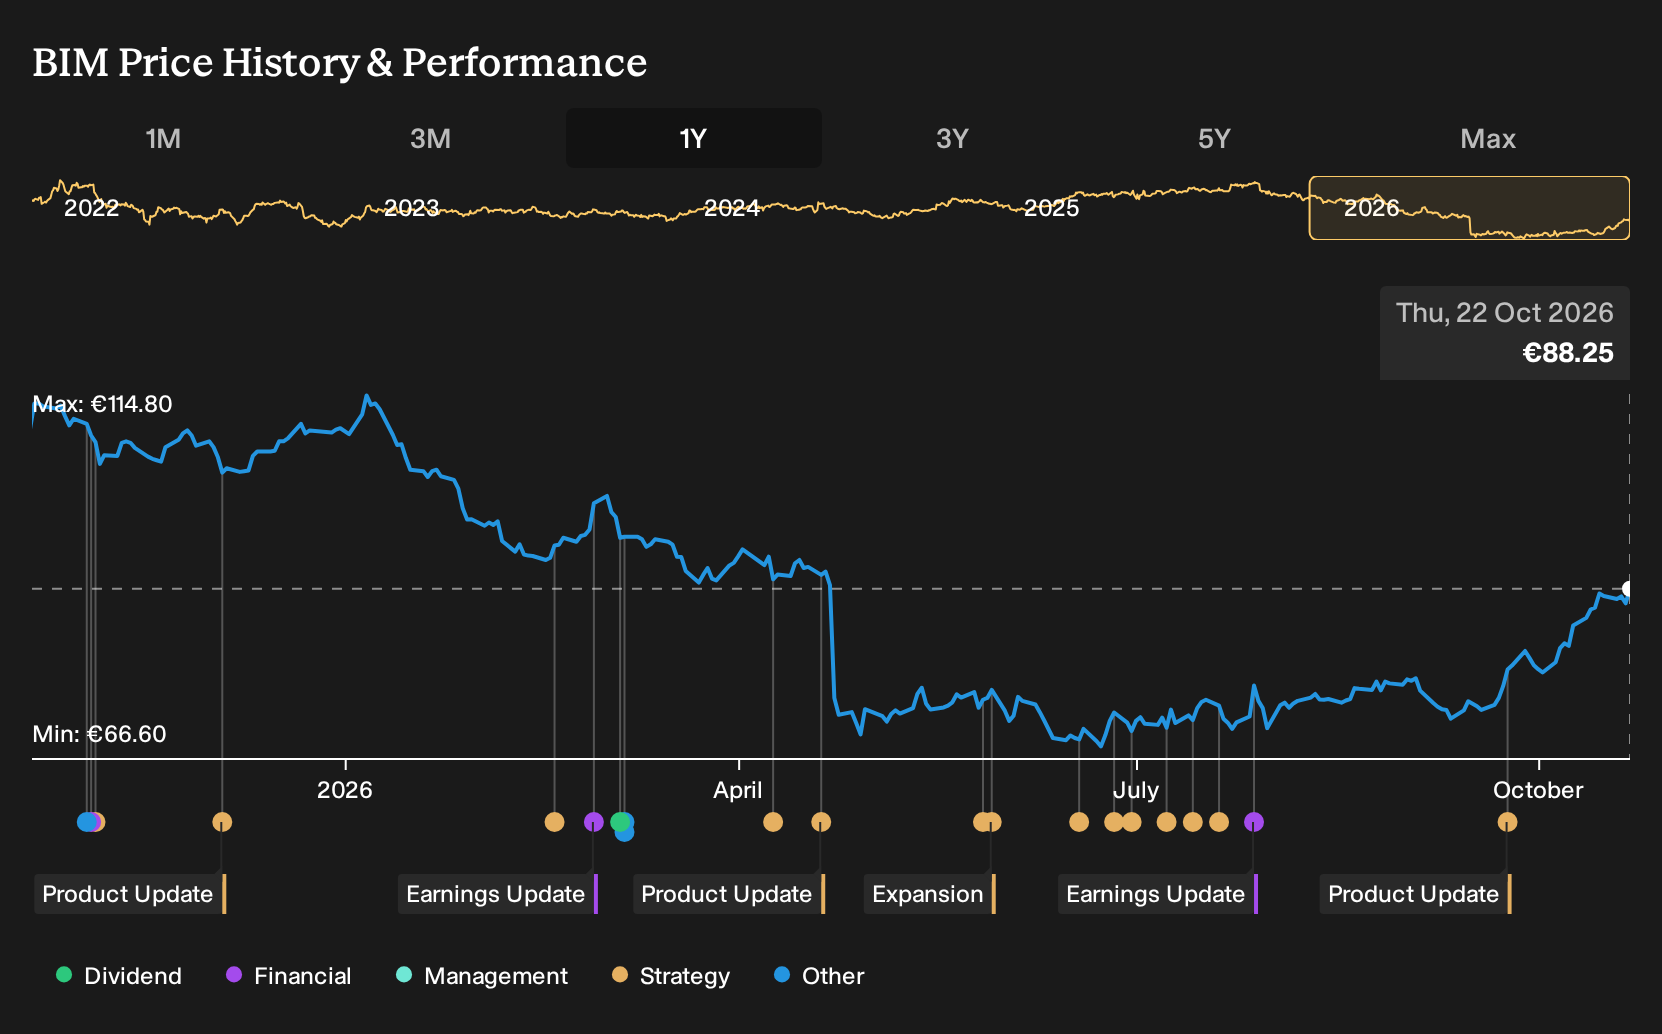
Valuation assumptions also lean on this earnings trajectory. On the numbers published, bioMérieux would need to reach €4.7b of revenue and €586.7 million of earnings in 2029 while trading on a P/E of 19.5x, compared with 22.2x today. The current analyst consensus price target of €79.9 sits about 9.2% below the recent share price of €87.25, which suggests the market is already giving the group credit for a fair portion of that execution.
For the SPOTFIRE Vaginitis Panel specifically, the CLIA waiver is what ties the clinical story to this financial framework. By allowing non lab clinicians in family medicine, urgent care and OB/GYN settings to run a multiplex vaginitis PCR, the test is designed to support exactly the kind of reagent intensity that underpins those margin and earnings expectations, without needing a comparable lift in instrument placements.
There is still tension between the upside and the risks. The same consensus that embeds growth from non respiratory testing also highlights double digit instrument declines in recent quarters, China revenue pressure in 2025 and early 2026, and higher U.S. tariffs adding €20 million to €24 million of extra cost this year. To see meaningful benefit from the new panel, usage has to scale fast enough and at pricing that offsets these known drags.
Investors watching bioMérieux may want to track a few concrete datapoints over the next couple of years. These include the mix of respiratory versus non respiratory SPOTFIRE cartridges, adoption of the vaginitis panel across primary care and OB/GYN clinics, how often clinicians use self collected versus clinician collected swabs in real practice, and whether training demands slow uptake. Each of those elements feeds back into the same question that runs through the analyst models: Can BIOFIRE and SPOTFIRE keep reagent growth and margins on the consensus path even if instruments and China stay under pressure?
bioMérieux’s current analyst narrative points to €4.7b in revenue and €586.7 million in earnings by 2029, based on revenue growing 5.4% per year and an earnings increase of about €124 million from €462.6 million today.
Uncover why bioMérieux's fair value indicates a 9% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate view on bioMérieux focuses on slower SPOTFIRE and BIOFIRE test volume growth as competition in multiplex PCR ramps up. The most cautious analysts were only pencilling in revenue rising about 4.1% a year and earnings reaching €551.0 million by 2029. You can now ask whether this new CLIA waived vaginitis launch nudges those more pessimistic assumptions higher or keeps them intact.
Explore 2 other bioMérieux fair value estimates, including one that suggests as much as 9% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your bioMérieux research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for bioMérieux. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate bioMérieux's overall financial health at a glance.
Looking For More Investment Ideas Beyond bioMérieux?
If you want to pressure test your view on bioMérieux against other opportunities, the Simply Wall St Screener can help you line up a broader watchlist that fits your risk tolerance and income needs.
- For investors who care most about resilience, consider reviewing a 222 resilient stocks with low risk scores that can help you focus on businesses with steadier risk profiles.
- If you are hunting for value backed by balance sheet strength, scan the list of solid balance sheet and fundamentals (205 results) to find companies with fundamentals that may better match your criteria.
- For those aiming to build a portfolio around income, shortlist ideas from a 224 dividend fortresses that concentrates on higher yielding dividend payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com