


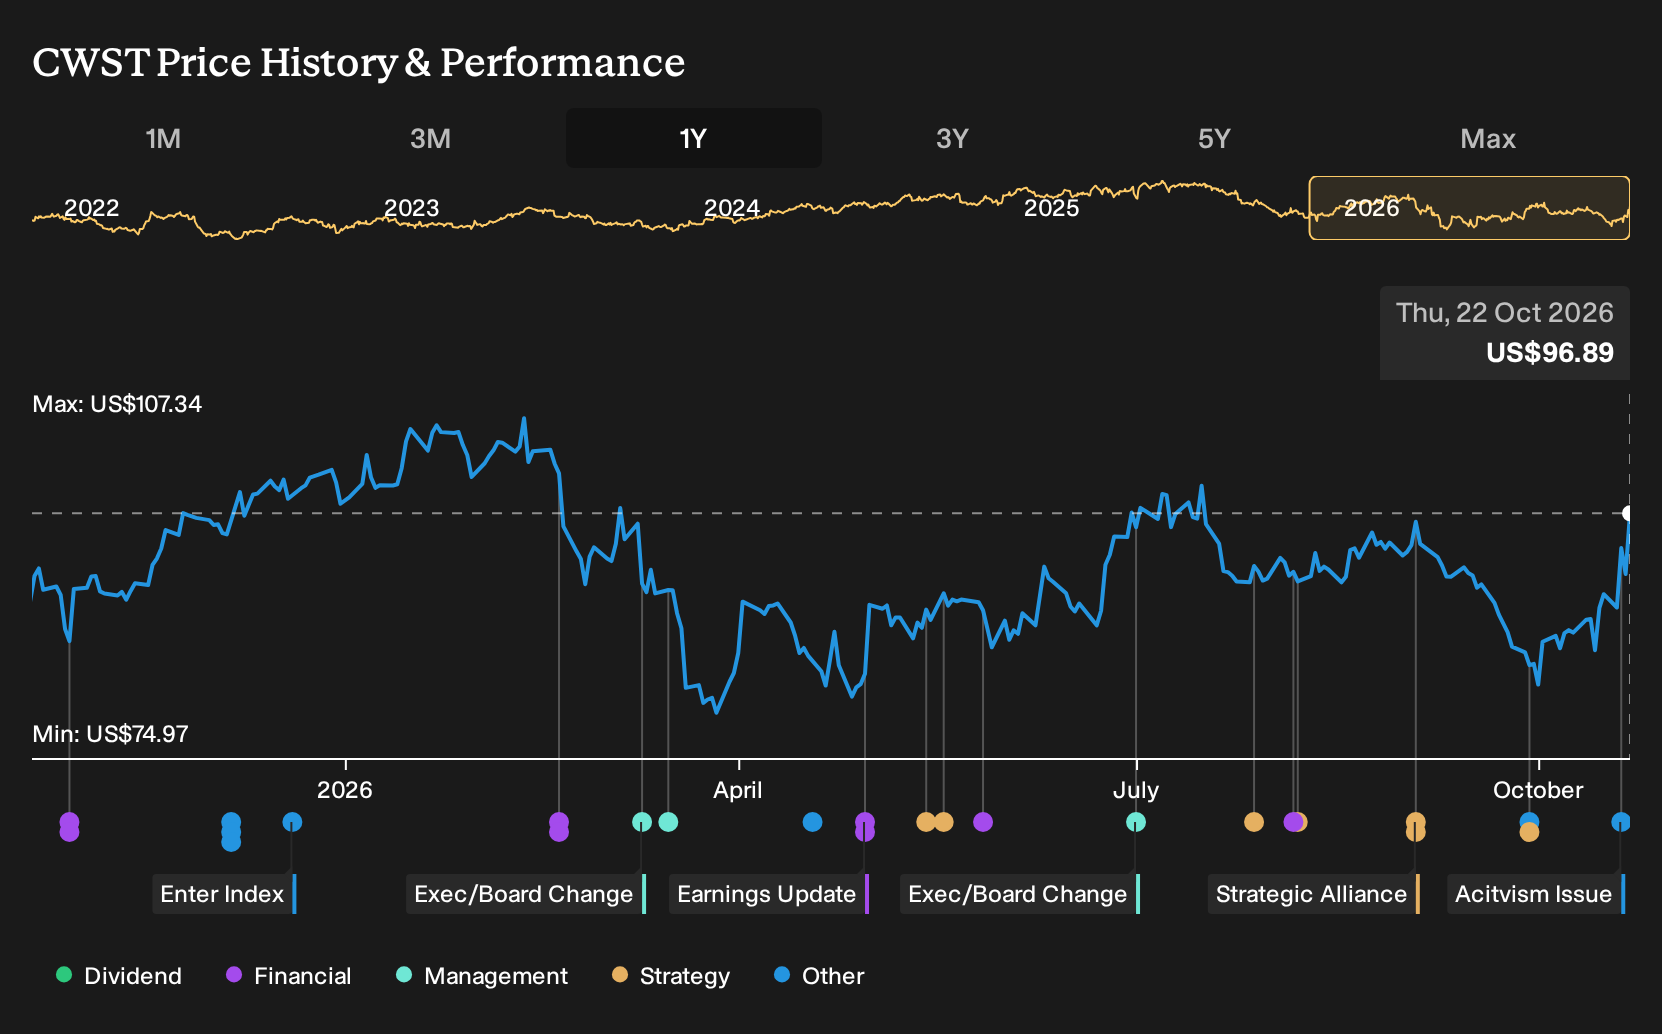
- In October 2026, Jana Partners LLC disclosed an activist stake in Casella Waste Systems and called for higher EBITDA margins, better capital efficiency, external performance consultants, and pay structures tied more tightly to shareholder outcomes by 2029.
- The push for an EBITDA margin near 27% directly challenges how Casella Waste Systems balances acquisition driven expansion, capital spending, and returns on invested capital over the next few years.
- We will now look at how Casella Waste Systems' investment narrative could shift as Jana presses for a 27% EBITDA margin target.
Casella Waste Systems Investment Narrative Recap
To own Casella Waste Systems, you need to be comfortable with a story built around dense regional markets, heavy capital needs, and a long build of earnings power from landfills, recycling, and resource solutions. The near term catalyst is whether infrastructure spending, automation projects, and Mid Atlantic integration translate into cleaner EBITDA and better free cash generation.
The biggest risk today is that margin pressure, one off items, and acquisition integration keep squeezing already thin 0.3% net profit margins while interest costs remain a burden. Jana Partners' push for a roughly 27% EBITDA margin by 2029 increases the focus on execution, but it does not by itself change those underlying operational risks.
The most relevant update is Jana Partners' October 2026 disclosure that it has built a new position in Casella Waste Systems and laid out a profitability and capital efficiency agenda. That request for a roughly 27% EBITDA margin by 2029 puts a hard marker against a business that has seen operating margin compress by 5.2 percentage points over five years.
This activism directly connects to existing catalysts around landfill internalization, automation savings, and tuck in acquisitions. If Casella Waste Systems executes on routing more tonnage into company owned disposal, delivers the planned savings from 40 automated trucks in 2026, and tightens returns on invested capital, then Jana's margin focus becomes a measuring stick for whether those projects are truly paying off.
What Jana’s Push Meets in Current Analyst Expectations
Casella Waste Systems now has two loud reference points on the table. Jana Partners is talking about EBITDA margin targets, while the analyst group is working off detailed revenue and earnings projections through 2029. Taken together, those views frame how much financial heavy lifting investors are implicitly assuming over the next few years.
Analysts currently build their models on 8.4% annual revenue expansion over the next three years, starting from a business that is earning about US$5.7 million today at a 0.3% net margin. Their base case points to profit margins of 2.8% in roughly three years and consensus earnings of US$70.5 million by 2029. That path would require earnings to rise by about US$64.8 million from current levels, which is a very large step up in absolute profit dollars even before layering on any extra uplift Jana wants from higher EBITDA.
Those same forecasts imply that by 2029, Casella Waste Systems could be generating about US$2.5b of revenue and US$70.5 million of net income, all in analyst models that already assume higher profitability and capital discipline. The debate for investors is whether that revenue trajectory, the implied jump in earnings, and a projected P/E of 119.5x on those 2029 numbers line up with the pressure Jana is applying for a leaner cost base and stronger returns on invested capital.
Casella Waste Systems' narrative projects US$2.5b revenue and US$70.5 million earnings by 2029. This requires 8.4% yearly revenue growth and an earnings increase of about US$64.8 million from US$5.7 million today.
Uncover why Casella Waste Systems' fair value indicates a 10% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The Simply Wall St Community has only two fair value estimates for Casella Waste Systems so far, stretched between about US$106.50 and US$158.56 per share. That sparse but wide band shows how far opinions can diverge before factoring in Jana’s margin campaign, acquisition integration risk, or landfill automation as potential earnings swing factors. Readers should treat these as starting points and compare several contrasting views.
Explore another Casella Waste Systems fair value estimate, including one that suggests it could be worth just $106.50.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Casella Waste Systems research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Casella Waste Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Casella Waste Systems' overall financial health at a glance.
Looking for more Casella Waste Systems style investment ideas?
If the Casella Waste Systems story has you thinking about where else capital efficiency and better execution could matter, it helps to scan a wider field of opportunities using the Simply Wall St Screener.
- Prefer businesses where valuation and quality both matter? Start with a curated set of 29 high quality undervalued stocks that combine fundamental strength with discounted pricing.
- If balance sheet strength is your first filter, focus on a list of solid balance sheet and fundamentals (26 results) so you can concentrate on companies that already have financial resilience in place.
- Want ideas that aim for steadier returns? Shortlist income candidates from a hand picked 6 dividend fortresses and then compare their fundamentals side by side.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com