


Interparfums (IPAR) has just reported third quarter 2026 sales that were essentially unchanged at US$430 million, with European growth offsetting weaker reported figures in the U.S. tied to delayed giftset shipments.
Interparfums shares trade at US$116.07 after a 2.54% one-day share price gain, with short-term momentum softer given a 30-day share price return that declined 1.88% and a 90-day move that fell 5.29%. However, the year-to-date share price return of 35.85% and 1-year total shareholder return of 22.45% point to a stock that has broadly trended higher as investors weigh flat reported sales against steady demand, recent shipment timing issues, and expectations around upcoming launches.
Spot opportunities with a similar mix of brand strength and earnings quality by scanning our hand picked 20 high quality undiscovered gems alongside Interparfums.Interparfums now trades below both analyst targets and an estimated fair value after a strong year and a flat quarter driven by shipment timing. Is that discount caution well placed or overly harsh on a timing issue?
Most Popular Narrative: 8% Undervalued
Interparfums now trades at $116.07 against a most-followed fair value estimate of about $126.67. This frames a modest discount that depends on how effectively management turns today's heavier investment into tomorrow's earnings power.
The decision to make 2026 an off cycle year focused on line extensions while preparing a concentrated wave of new blockbuster pillars for brands already above US$100m of sales in 2027 and further launches in 2028, supported by higher advertising and promotion spending that reached 18.8% of sales in the first half of 2026 and is guided toward about 21% for the full year, sets up a product cycle that can support higher revenue, operating margin and earnings power.
See why 8 investors see Interparfums as 8% undervalued.
Result: Fair Value of $126.67 (UNDERVALUED)
Still, the Interparfums narrative can break if higher SG&A and heavier advertising fail to lift demand, or if key fragrance licenses are lost or underperform.
Find out about the key risks to this Interparfums narrative.
Another View: Interparfums Through The P/E Lens
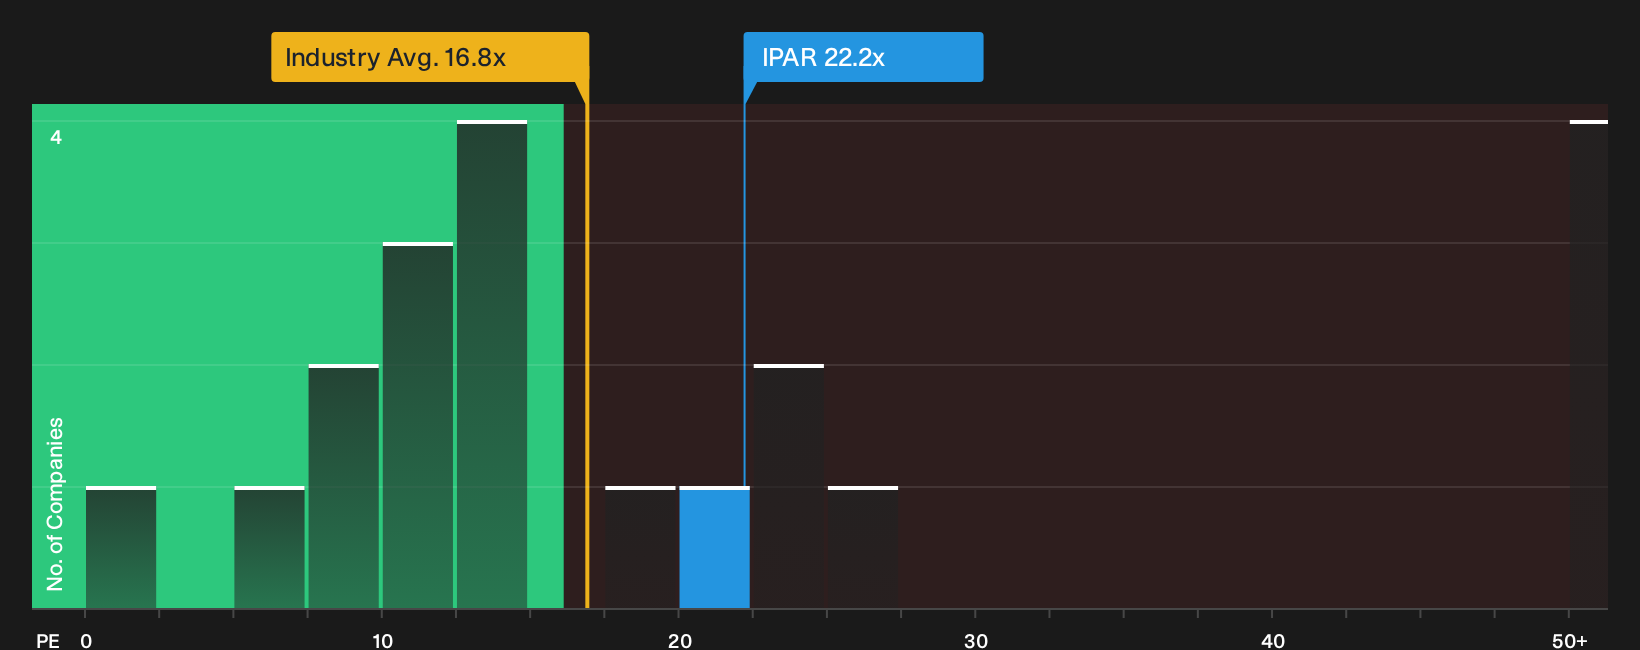
On the flip side of the fair value narrative, Interparfums trades on a P/E of 22.2x, which is richer than both the estimated fair ratio of 15.2x and the global Personal Products average of 17x. That gap points to valuation risk if growth or margins do not match expectations.
For a closer look at how that premium lines up with the earnings profile, have a look at See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Interparfums so far. If you want to move fast and anchor your own view in the numbers, weigh up the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Interparfums?
If Interparfums has you thinking more carefully about price, quality and risk, do not stop here. Broaden your opportunity set with focused screens built for exactly that.
- Target stronger balance sheets by reviewing the list of solid balance sheet and fundamentals (26 results) that can better absorb shocks and still fund growth.
- Hunt for underappreciated quality using the 29 high quality undervalued stocks to spot businesses where fundamentals and current pricing look out of sync.
- Prioritise resilience and capital protection with the 30 resilient stocks with low risk scores before markets move and those quieter opportunities get crowded.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com