


- PTC recently launched PTC Jetstream, a cloud and AI native collaboration platform that connects people, product data, and decisions through secure rooms, browser based 2D and 3D reviews, contextual feedback, and AI room summaries integrated with Windchill PLM.
- The product directly targets long running friction in product development by keeping comments, decisions, and product context in a single governed workspace, which can influence how efficiently PTC customers manage complexity and execution risk across engineering teams and suppliers.
- We will look at how PTC's investment narrative around AI monetisation and product data platforms is affected by Jetstream's AI collaboration focus.
PTC Investment Narrative Recap
For you to own PTC, you need to believe in its pitch as an AI driven product data platform where recurring software contracts and embedded price escalators matter more than short term swings in demand. The key near term catalyst still sits in execution on AI monetisation across tools like Creo AI, ServiceMax AI, Orbit and now Jetstream. This launch helps reinforce that theme but does not radically change the story on its own.
The biggest operational risk remains weaker retention and upsell in ServiceMax, which could drag on ARR and earnings even if newer AI products gain traction. Another watchpoint is that consensus expects earnings to decline over the next three years, so any delay in translating AI usage into higher contract values would make that earnings profile harder to improve.
The recent extension of the United States Air Force relationship around Servigistics is the clearest operational anchor next to Jetstream. It shows PTC still has embedded positions in complex service and supply chain environments where AI and exception based management features can matter for large customers.
For investors, that Air Force extension helps support the catalyst that PTC can cross sell more AI centric workflows into an existing installed base, not just chase new clients. It also highlights an execution risk. Big reference accounts set expectations for how well PTC keeps modernising its service and supply chain stack relative to competitors, and investors will likely watch this closely as AI products roll out.
What Jetstream Means Against PTC's Analyst Baseline
PTC's narrative projects US$3.3b revenue and US$907.5 million earnings by 2029. Analysts are building that on 4.1% yearly top line growth and an earnings decline of about US$292.5 million from US$1.2b today.
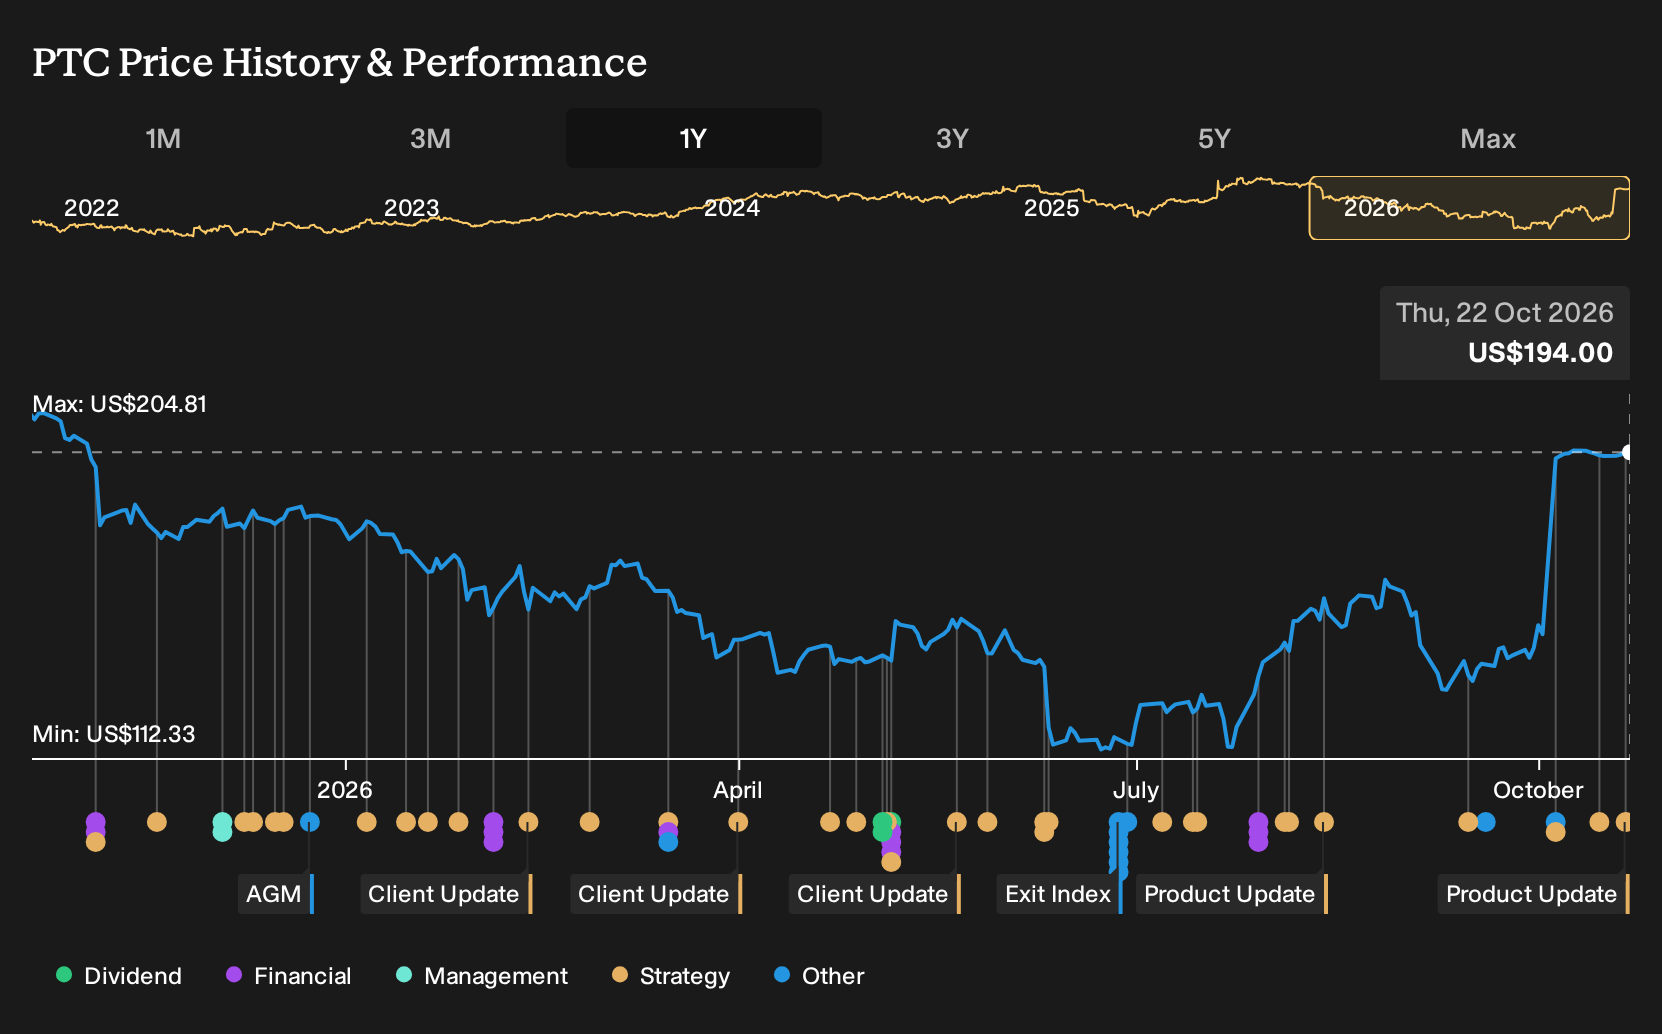
Discover how PTC's fair value indicates a 4% potential upside to its current price that could close faster than many investors expect.
Exploring Other Perspectives
One bullish twist on the Jetstream news is the Schneider Electric deal that optimistic analysts were already baking in. They were working off revenue of about US$3.4b and earnings of roughly US$936.2 million by 2029, which is higher than the baseline. That group sees much more upside from AI and product data integration than consensus. You can use those numbers as a reference point and decide whether Jetstream and the Air Force renewal could push expectations closer to that upper range or prompt fresh revisions.
Explore 6 other PTC fair value estimates, including one that suggests as much as 104% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your PTC research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for PTC. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PTC's overall financial health at a glance.
Looking For More Ideas Beyond PTC?
Once you have formed a view on PTC, it often helps to compare it against a wider watchlist so you can judge risk, income potential, and valuation across different businesses.
The Simply Wall St Screener can surface very different types of opportunities, depending on what you want your portfolio to do next.
- If you care most about resilient balance sheets and steady fundamentals, start with our list of solid balance sheet and fundamentals (26 results) to see which businesses currently meet that standard.
- For investors focusing on quality at a reasonable price, scan our 29 high quality undervalued stocks and see which stocks the data currently flags as potentially mispriced.
- If you are hunting for under the radar stories with stronger financial profiles, our 20 high quality undiscovered gems can help you quickly spot candidates for deeper research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com