


Europe is quietly redrawing its trade map as Brussels weighs tougher limits on Chinese imports and trims hybrid vehicle inflows, and that shift could reshape where capital flows next. Policy risk is turning into policy action, which means some companies may gain fresh protection while others lose an important sales channel. This article walks through three stocks exposed to these EU China trade moves and explains why each could matter for your portfolio.
The three stocks that follow are a quick sampler, and the full screen surfaced 59 more European industrial reshoring candidates with equally compelling stories that are not covered here. To go straight to the full universe and begin identifying and analyzing your own highest conviction ideas, head to the European Industrial Reshoring and Onshore Manufacturing Beneficiaries screener
Continental (XTRA:CON)
Overview: Continental is a Hanover based tire and automotive materials group that supplies EU carmakers, linking directly into reshoring and onshore manufacturing.
Operations: Continental generates about €13.6b from Tires and €5.2b from ContiTech, with roughly €9.3b coming from Germany and wider European markets.
Market Cap: €13.4b
Continental matters for this reshoring theme because it sits inside the EU auto supply web, where any shift in local production or trade rules can change how much cash it sends back to shareholders and how easily it funds future factories and tooling.
"The planned return of about €2.5b of ContiTech sale proceeds to shareholders, together with roughly €600m earmarked for deleveraging toward a leverage ratio near 1x by 2029, outlines a path for higher cash returns and lower financing costs that may support future earnings per share."
What happens when one pressure on Continental’s regional profitability breaks in its favor could be the real swing factor for investors.
If that swing factor matters to you, read the full narrative for Continental to see how Continental’s reshoring exposure, capital returns, and risk profile fit together.
Arkema (ENXTPA:AKE)
Overview: Arkema is a France headquartered specialty materials group supplying adhesives, advanced polymers and coating solutions to European and global industrial customers.
Operations: Arkema generates about €3.4b from Advanced Materials, €2.7b from Adhesive Solutions and €2.2b from Coating Solutions, with smaller corporate items and adjustments.
Market Cap: €4.1b
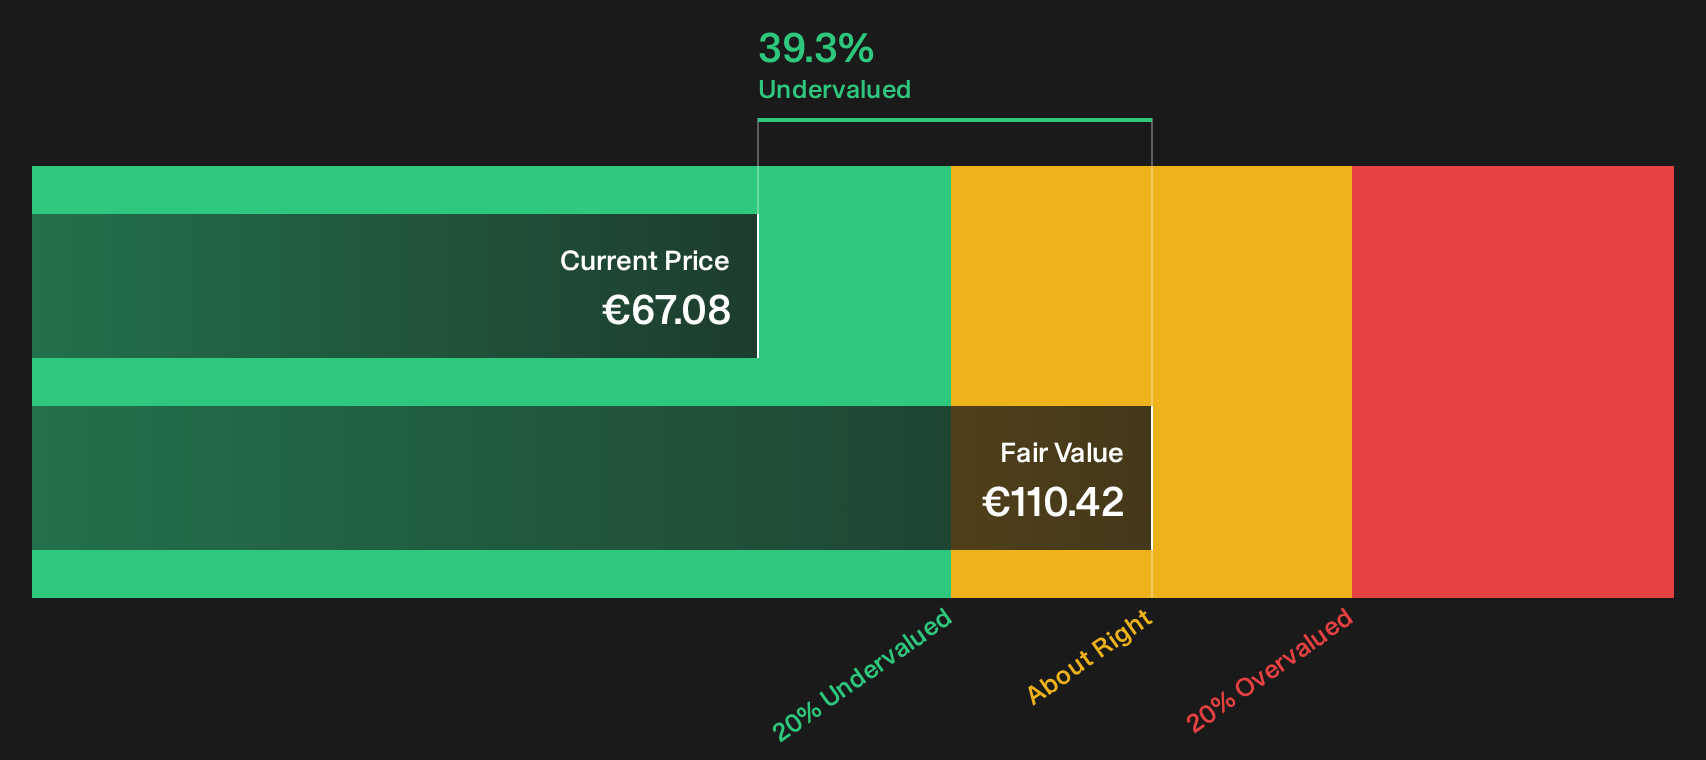
Arkema plugs directly into the reshoring story because many of its high performance materials feed European autos, construction and energy projects that policymakers are keen to keep on home turf.
"Significant investments in new production capacity, including the Singapore biobased polyamide plant, the U.S. PVDF expansion and additives facilities targeting refining and biofuel markets, remain in ramp up and are now contributing incremental EBITDA of around €60m in 2025 and a guided €50m in 2026. These investments can continue to support revenue and earnings as utilization improves."
How a single shift in pricing pressure affecting Arkema’s pricing power develops could be critical for the overall margin story.
That margin question is just the start, and the full narrative for Arkema shows how Arkema’s reshoring exposure, capital plan and risk skew could be quietly resetting its earnings mix.

ArcelorMittal (ENXTAM:MT)
Overview: ArcelorMittal is a Luxembourg based integrated steel and mining group supplying European autos, machinery and construction with essential steel products.
Operations: ArcelorMittal earns most of its revenue from Europe at about $29.2b, alongside Brazil at $11.7b and North America at $13.3b.
Market Cap: €40.7b
For a theme built around reshoring and onshore manufacturing, ArcelorMittal matters because it provides the basic steel that European automakers and equipment makers need if capacity shifts back toward local mills.
"Strategic investments in green steel production (EAFs, DRI technology, renewable-backed projects) and early execution of decarbonization projects position ArcelorMittal to capture premium, higher-margin demand from eco-conscious customers, driving margin expansion and supporting long-term earnings."
What happens if a single pressure on European steel trade rules or capacity utilization breaks in ArcelorMittal’s favor could reshape that earnings path.
If that inflection point interests you, read the full narrative for ArcelorMittal to see how ArcelorMittal’s decarbonization push and trade exposure could be quietly reshaping its earnings potential.

Seeking Fresh Alternatives Before They Fly
Fresh breakout ideas rarely stay under the radar for long. Once momentum builds, entry points move fast and information decays quickly. Scan new candidates before the crowd and act now.
- Spot cash generative compounders early by running the 195 high quality undervalued stocks while prices and expectations still feel out of sync with their balance sheets.
- Ride the next leg of the AI build out by tracking infrastructure enablers using the 55 AI infrastructure stocks before capital rotates their way in size.
- Target potential future hardware workhorses by filtering focused automation and machinery specialists through the 95 robotics and automation stocks while they are still priced for hesitation, not conviction.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com