


Investor interest in Trex Company builds after valuation debate
Trex Company (TREX) has drawn fresh attention after recent analyst commentary suggested its current share price may not fully reflect projected cash flows and potential free cash flow strength.
Recent interest has come on top of strong momentum in the Trex Company share price, with a 1-month share price return of 15.73% and a year-to-date share price return of 42.53%. However, the 5-year total shareholder return is down 51.46%, which hints that the latest move is more about shifting expectations and renewed focus on projected cash flows than a long, uninterrupted winning streak.
See how the renewed Trex Company debate fits into the broader hunt for potential mispriced cash flow stories by reviewing our hand picked 29 high quality undervalued stocks.
Trex Company has just made a sharp upward move on top of a weak 5-year record, which presents a practical fork in the road. Do you pay a higher price now for the projected cash flow story, or wait for a potentially cooler entry point?
Most Popular Narrative: 6.6% Undervalued
Trex Company closed at $51.07, while the most followed narrative pegs fair value at $54.67, so the current debate centers on whether the market is still underpricing its future cash flows and capacity led free cash flow story.
The step-down in capital expenditure following roughly US$500 million invested over five years, with capex moving from about US$250 million in 2024 to 2025 to guidance of US$100 to US$120 million in 2026 and an expected longer term level of 5 to 6% of sales, combined with plans for tuck-in M&A and up to US$150 million of additional share repurchases in 2026, sets up a period where free cash flow, earnings per share and return on capital can benefit from higher utilization of the existing asset base.
See why 6 investors see Trex Company as 7% undervalued.
Result: Fair Value of $54.67 (UNDERVALUED)
Still, the Trex Company thesis can be shaken if Little Rock inefficiencies keep margins under pressure or if higher marketing spend keeps SG&A around 18% of sales.
Find out about the key risks to this Trex Company narrative.
Another View: What Trex Company’s P/E Is Telling You
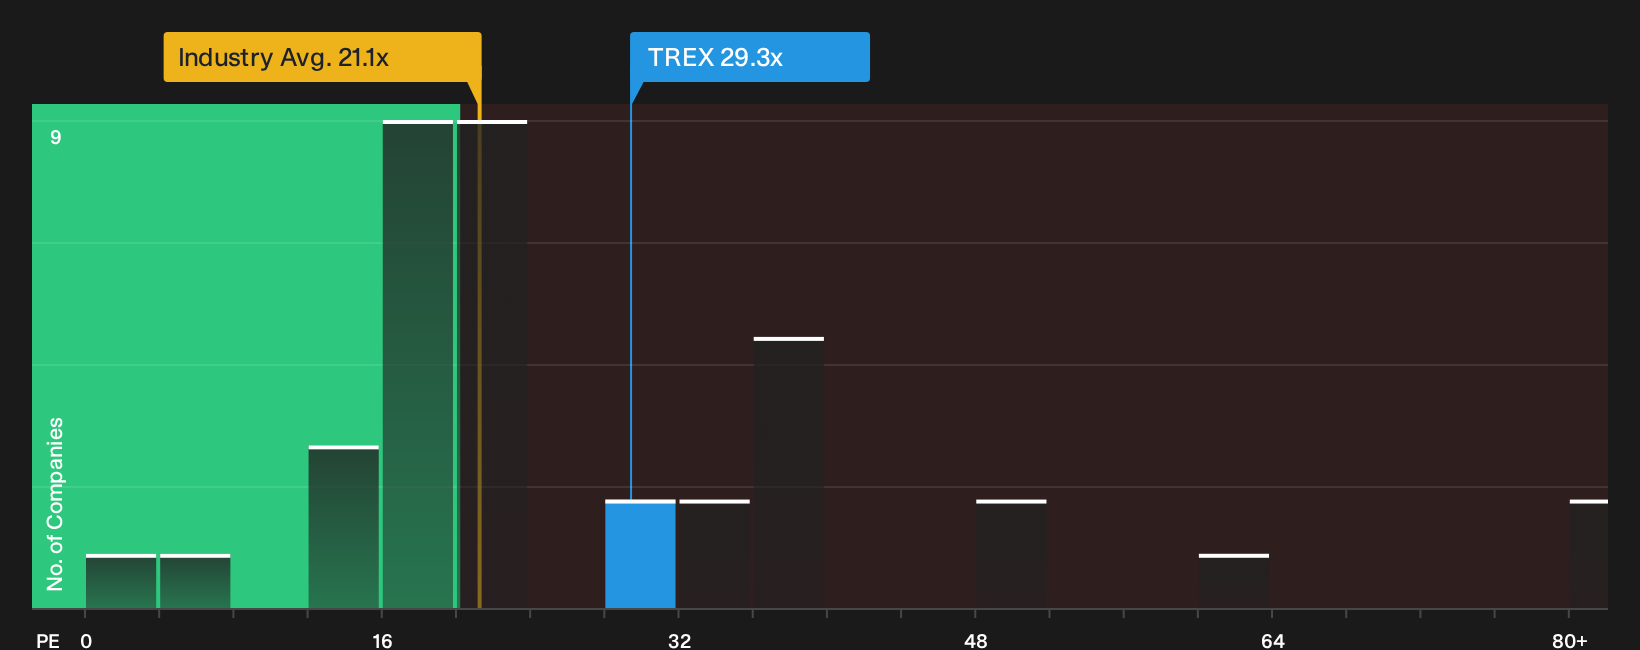
Trex Company screens as undervalued on cash flows, yet its 29.3x P/E is well above the US Building industry at 20.2x and higher than its own fair ratio of 22.1x. That gap points to valuation risk if growth or margins fall short. Which signal do you trust more, the cash flow model or the multiple?
To unpack what this richer earnings multiple could mean for upside or downside risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the optimism in Trex Company really stacks up for you personally? Act quickly and review the key upside factors in the 2 key rewards.
Looking for more Trex Company investment ideas?
If Trex Company has your attention, do not stop here. Use fresh data-driven lists to surface other opportunities that could fit your style before they move.
- Target resilient performers by reviewing a curated 30 resilient stocks with low risk scores that keeps overall risk in focus while you weigh potential returns.
- Hunt for mispriced potential and scan the 20 high quality undiscovered gems that the broader market may not be watching closely yet.
- Strengthen your core holdings by checking a list of solid balance sheet and fundamentals (26 results) that prioritises financial stability alongside fundamental quality.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com