


Q3 sales beat and outlook confirmation put SGS in focus
SGS (SWX:SGSN) moved into the spotlight after its Q3 2026 sales and trading statement call, where revenue topped analyst expectations and management reaffirmed guidance for 5 to 7 percent organic growth and continued acquisitions.
Recent trading has reflected that stronger backdrop. The share price is up 5.74% over the past month and 8.49% year to date, while total shareholder return of 15.81% over one year and 54.05% across three years suggests that momentum has been building rather than fading.
Compare how SGS stacks up against other testing and inspection specialists by scanning hand picked list of solid balance sheet and fundamentals (205 results) that could benefit from similar contract driven momentum.
SGS has just delivered record sales growth and confirmed guidance, yet still trades at a sizeable discount to one intrinsic value estimate, with only a small gap to analyst targets. Is the market’s caution misplaced or sensible here?
Most Popular Narrative: Fairly Valued
On the most followed view, SGS screens close to fairly priced, with the narrative fair value of CHF100.95 sitting almost on top of the last close at CHF100.90. This puts more weight on how the business mix and execution risks play out from here than on a simple price gap.
SGS's exposure to increasingly stringent global regulatory environments and its expanding sustainability and ESG services (which grew 19% in H1 2025) position the company to capitalize on the rising demand for compliance, traceability, and certification, supporting sustained revenue and margin growth.
See why 19 investors see SGS as 0% undervalued.
This central narrative uses a 4.67% discount rate and incorporates analyst forecasts for revenue growth of about 6.3% a year and earnings expansion of roughly 10% a year, along with a profit margin trajectory from 9.2% to 10.5%. It also assumes SGS trades on a future P/E multiple of 26.9x, which is above the current Professional Services industry level flagged in the narrative. The fair value therefore rests on the business sustaining that premium as cost savings, acquisitions and higher value services feed through.
Result: Fair Value of CHF100.95 (ABOUT RIGHT)
Still, this fair value story depends on cost savings and acquisitions bedding in smoothly. Any setback in Business Assurance or slower consulting demand could quickly test that optimism.
Find out about the key risks to this SGS narrative.
Another view on SGS valuation
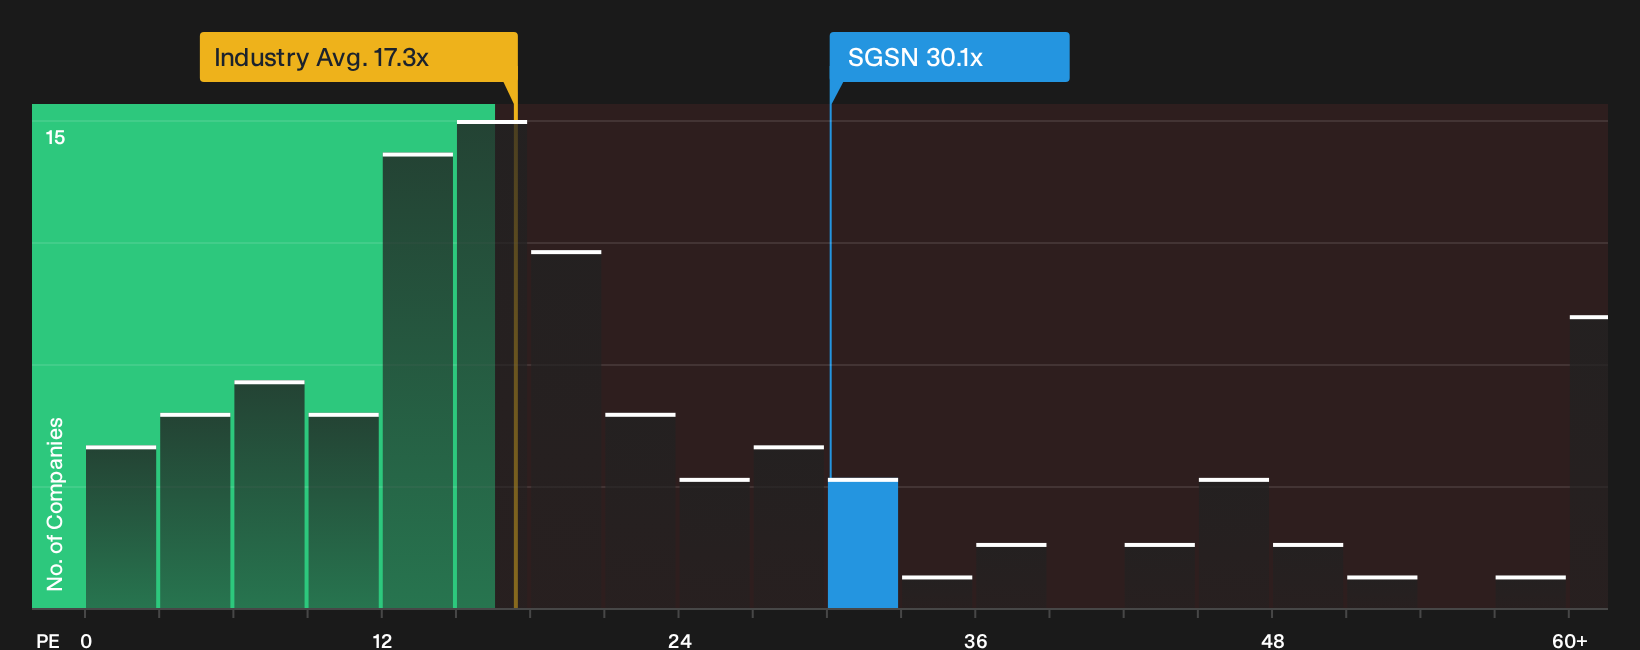
On a simple earnings multiple, SGS looks less forgiving. The stock trades on about 30.1x P/E, while the fair ratio sits at 24.3x and peers cluster closer to 22.1x and 17.6x in the wider Professional Services group. Is that premium a cushion or a source of downside if sentiment cools?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feel the mixed message in SGS so far, with record sales on one side and valuation questions on the other. Move quickly, review the full data set for yourself, and weigh both the upside potential and the issues flagged in the 3 key rewards and 2 important warning signs.
Looking for more SGS investment ideas beyond this story?
If SGS has sharpened your focus, do not stop here. Broaden your watchlist with other opportunities that match your risk, income, and value priorities.
- Target potential mispricing and hunt for quality on sale by scanning a curated set of 195 high quality undervalued stocks that already clear strict fundamental checks.
- Strengthen your income stream and stress test payout reliability by lining up a shortlist of 224 dividend fortresses built around robust balance sheets and cash coverage.
- Dial down portfolio stress and prioritise resilience by filtering for 222 resilient stocks with low risk scores that score well on financial health and volatility checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com