


Johnson Controls International plc (JCI), headquartered in Cork, Ireland, engineers, manufactures, commissions, and retrofits building products and systems. With a market cap of $86.6 billion, the company offers air systems, building management, HVAC controls, security, and fire safety solutions. The engineering giant is expected to announce its fiscal fourth-quarter earnings for 2026 before the market opens on Tuesday, Oct. 27.
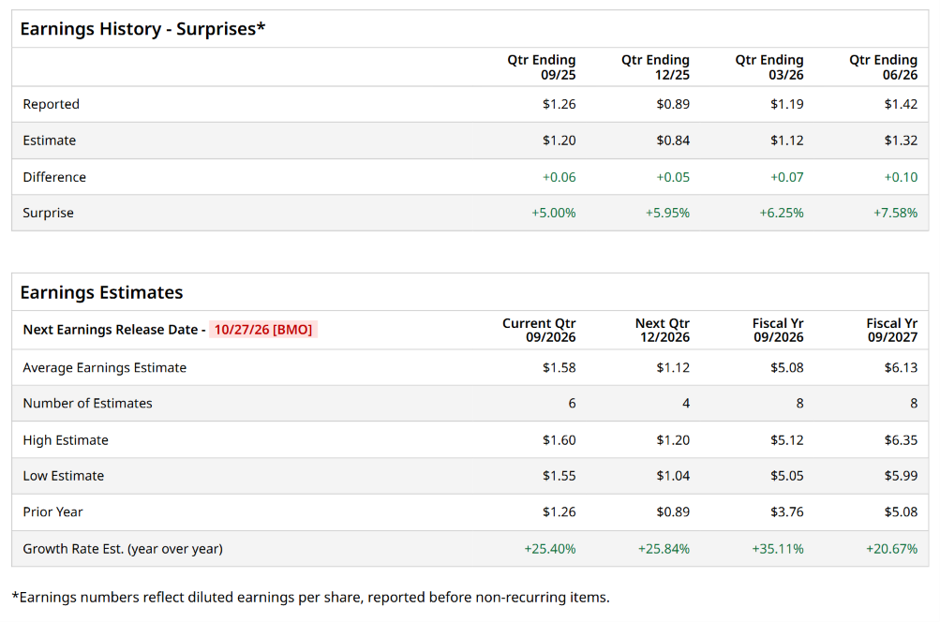
Ahead of the event, analysts expect Johnson Controls to report a profit of $1.58 per share on a diluted basis, up 25.4% from $1.26 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
For the full year, analysts expect Johnson Controls to report EPS of $5.08, up 35.1% from $3.76 in fiscal 2025. Its EPS is expected to rise 20.7% year over year to $6.13 in fiscal 2027.
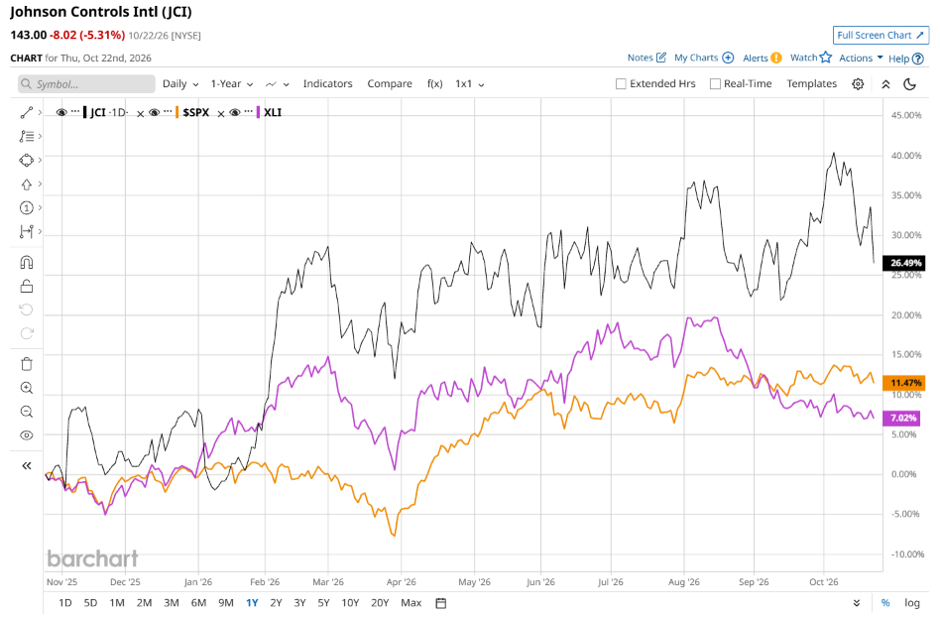
JCI stock has outperformed the S&P 500 Index’s ($SPX) 14.4% gains over the past 52 weeks, with shares up 31.8% during this period. Similarly, it outperformed the State Street Industrial Select Sector SPDR ETF’s (XLI) 6.8% rise over the same time frame.
JCI has outperformed primarily by capitalizing on the rapid expansion of AI-driven data centers and mission-critical infrastructure, which has triggered massive demand for its Applied HVAC cooling systems, building automation, and smart security solutions. This structural tailwind pushed organic order growth up nearly 30% year over year, driving a record backlog exceeding $21 billion. At the same time, strong execution on high-margin service contracts, pricing power, and operational productivity gains have steadily expanded EBITA margins and fueled double-digit adjusted EPS growth. This robust fundamental performance enabled management to repeatedly raise full-year guidance, solidifying investor confidence in JCI as a key industrial beneficiary of the AI infrastructure boom.
On Jul. 29, JCI shares closed down marginally after reporting its Q3 results. Its revenue was $6.6 billion, beating analyst estimates by 2.5%. The company’s adjusted EPS of $1.42 surpassed analyst estimates of $1.30.
Analysts’ consensus opinion on JCI stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 21 analysts covering the stock, 12 advise a “Strong Buy” rating, eight suggest a “Hold,” and one recommends a “Strong Sell.” JCI’s average analyst price target is $169.05, indicating a potential upside of 18.2% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.