


Super Micro Computer (SMCI) stock is back in focus after the artificial intelligence (AI) server maker delivered a major boost to its fiscal first-quarter revenue outlook, providing investors with a fresh reason to revisit the stock. Supermicro raised its Q1 fiscal 2027 revenue guidance to $18.5 billion-$19.5 billion from its previous forecast of $14.5 billion-$15.5 billion. At the midpoint, the new outlook is about $4 billion higher than the previous guidance, underscoring the strength of demand for AI infrastructure.
The upbeat preliminary update also included a significant improvement in the company’s gross margin outlook, which was raised to 12%-12.5% from 10.4%-10.8%, primarily due to a more favorable customer and product mix. The revenue outlook is also well above Wall Street’s average estimate of about $15 billion, highlighting the potential for another substantial upside when Supermicro reports its full Q1 results on Nov. 3.
With AI data center spending continuing to drive demand for servers and related infrastructure, Supermicro’s $4 billion guidance increase could be an important catalyst for SMCI stock and a compelling reason for investors to take another look at the shares.
About Supermicro Stock
Super Micro Computer is a San Jose, California-based technology company that designs, develops, and manufactures application-optimized server, storage, and networking solutions for AI, cloud computing, enterprise, and other demanding workloads. The company has built a broad portfolio spanning GPU-optimized servers, rack-scale systems, storage platforms, motherboards, and liquid-cooling technologies, positioning it as a key infrastructure supplier benefiting from growing AI data center spending. It has a market cap of $22 billion.
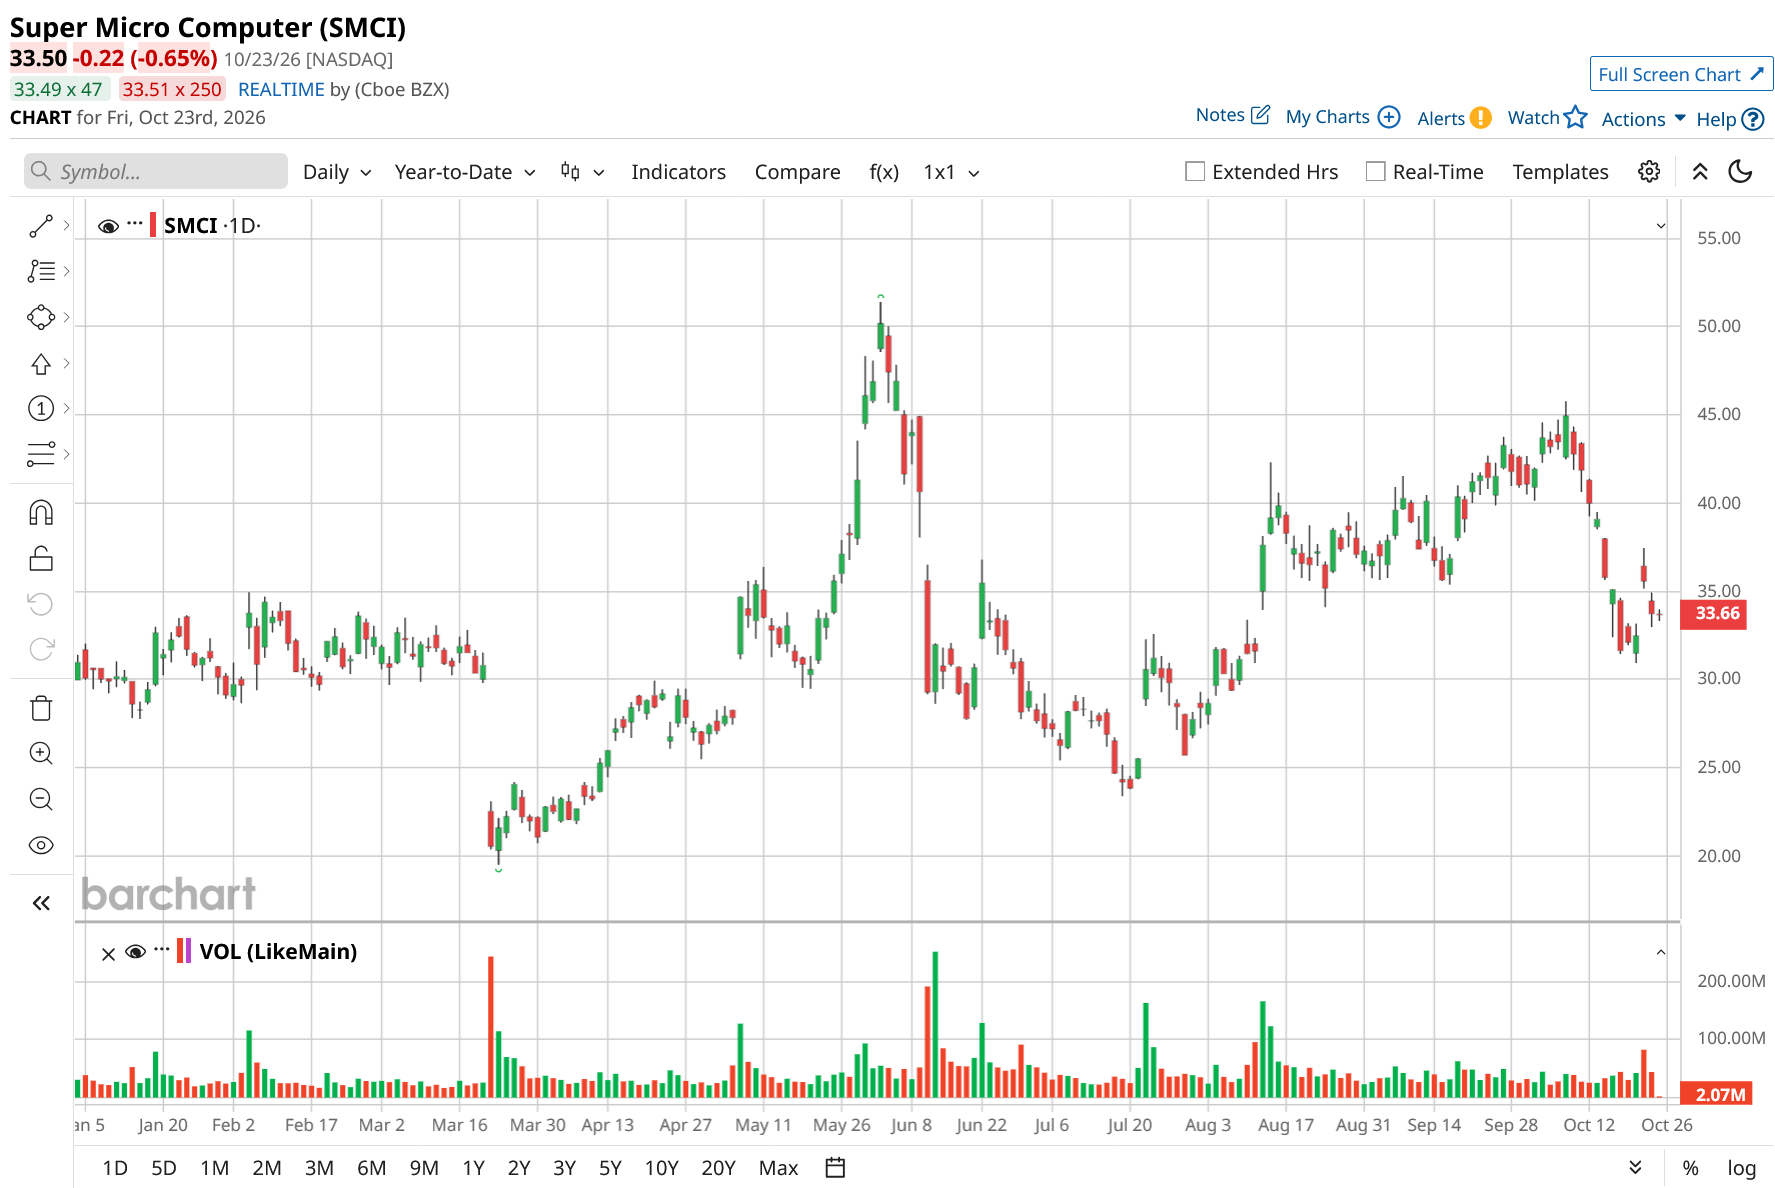
SMCI stock has remained under pressure over the past year despite an overall positive performance in 2026. Shares are down 29% over the past 52 weeks, reflecting earlier concerns around profitability, execution, and the sustainability of the AI infrastructure spending cycle. However, the stock has gained 15% year-to-date (YTD), as investors remain moderately optimistic about Supermicro’s position in the rapidly expanding AI server market.
The recent momentum has been particularly strong. Supermicro's stock jumped 9.5% during Wednesday's trading session, after the company unveiled preliminary fiscal first-quarter results that significantly exceeded its previous outlook. This suggests that demand for AI servers and data center infrastructure remains considerably stronger than previously anticipated and could help restore investor confidence in Supermicro’s growth trajectory. Full fiscal Q1 results are scheduled for Nov. 3, making the upcoming earnings report an important test of whether the latest rally can be sustained.
In terms of valuation, SMCI stock is priced at 8.24 times forward earnings and 0.55 times sales, trading at a discount compared to the sector peers.
Financial Performance Remains Encouraging
SMCI reported its fourth-quarter and full fiscal year 2026 financial results on Aug. 11, for the fiscal year ended June 30. The company delivered a major acceleration in its fourth-quarter performance, with net sales rising 91.4% year-over-year (YoY) to $11.1 billion.
Gross profit surged 257% to $1.9 billion, while gross margin expanded sharply to 17.5% from 9.5% in Q4 FY2025. Non-GAAP gross margin was 17.6%, versus 9.6% a year earlier. Operating income jumped 551.5% to $1.5 billion, while net income increased 503.7% to $1.2 billion. Its non-GAAP EPS increased to $1.70 from $0.41. The company also generated $747 million in operating cash flow during the quarter.
For the full fiscal year, Supermicro’s results also showed substantial growth. Fiscal 2026 net sales increased 77.7% to $39.1 billion. Gross profit climbed 74% YoY to $4.2 billion, although full-year gross margin slipped to 10.8% from 11.1%. Operating expenses increased 23.8% to $1.5 billion, while operating income more than doubled, rising 121.1% to $2.77 billion from $1.3 billion.
On a non-GAAP basis, net income attributable to common stockholders increased to $2.5 billion from $1.3 billion, and non-GAAP EPS rose 76.2% to $3.63.
Despite the strong earnings growth, cash flow remained an important concern. Supermicro’s rapid expansion required significant investment, resulting in substantial operating cash consumption earlier in the year. The company nevertheless ended fiscal 2026 with $7.5 billion of cash and cash equivalents, while total bank debt and convertible notes stood at $8.7 billion.
While the company has boosted Q1 results, for the full fiscal year 2027, management expects revenue of $65 billion to $72 billion. The outlook is supported by more than $60 billion in new orders generated during Q4 and a record backlog entering the new fiscal year.
Analysts project EPS to rise by 20.9% to around $3.94 for fiscal 2027, while the consensus estimate of $4.90 for fiscal 2028 indicates a rise by 24.4%. The consensus EPS estimate of $0.94 for the first quarter reflects a 261.5% rise YoY.
What Do Analysts Expect for SMCI Stock?
Recently, Bernstein reiterated a “Hold” rating on SMCI while maintaining a $42 price target, as Bernstein remains cautious on the stock’s risk-reward profile despite its significant AI infrastructure opportunity. Supermicro continues to benefit from strong demand for AI servers and data center infrastructure, while investors keep weighing execution, profitability, governance, and competitive risks.
Furthermore, Citigroup maintained its “Neutral” rating on SMCI but raised its price target to $45 from $39.
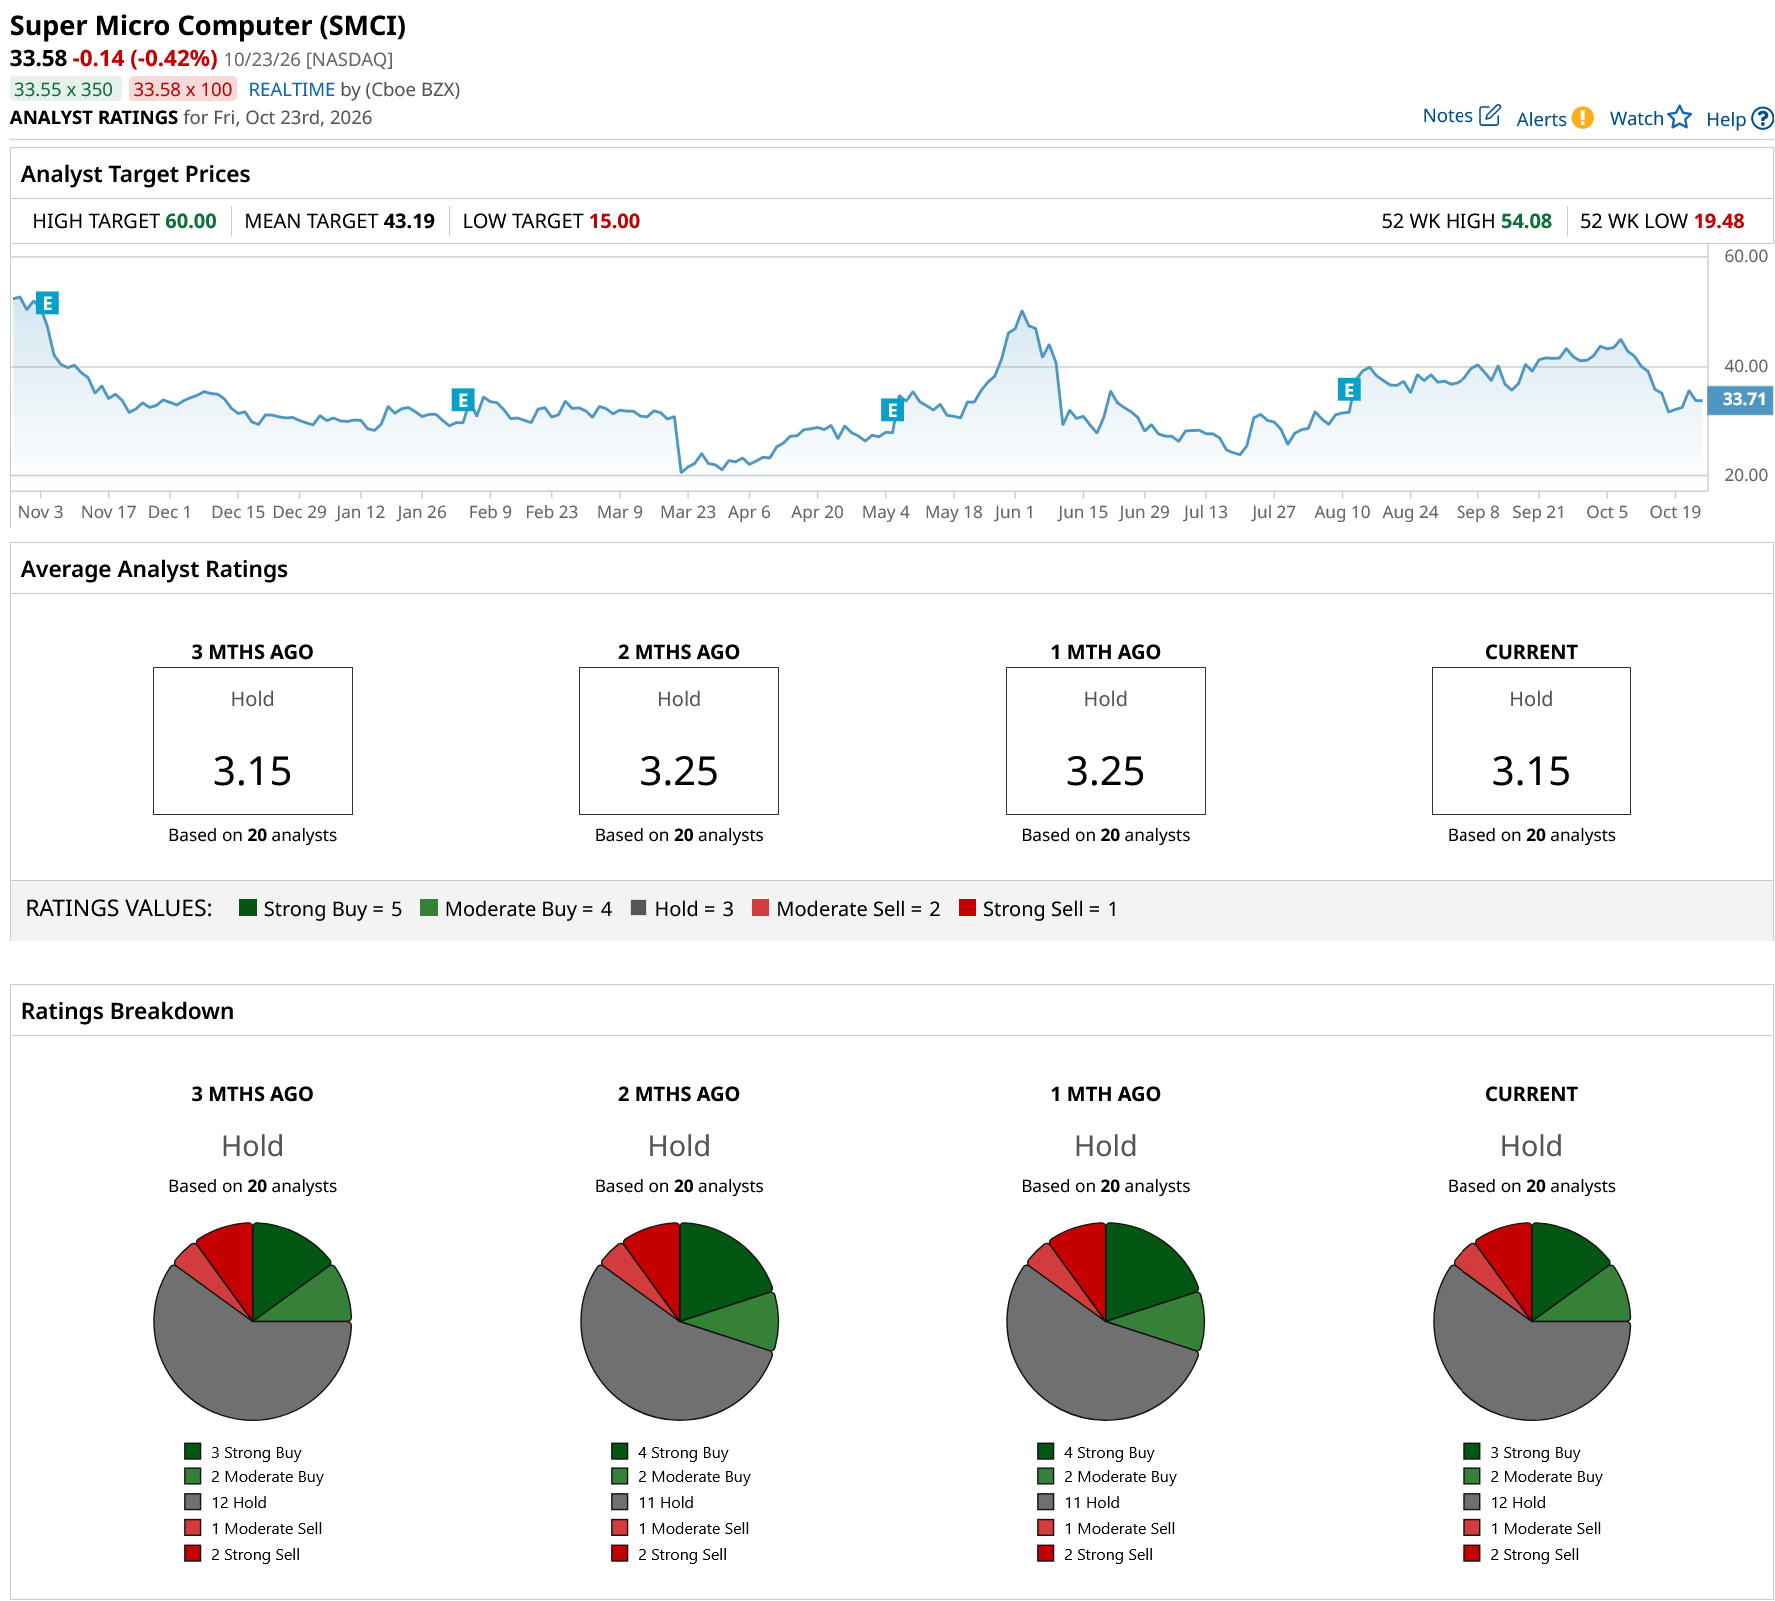
SMCI stock has a consensus “Hold” rating overall, signaling caution. Out of 20 analysts covering the tech stock, three recommend a “Strong Buy,” two give a “Moderate Buy,” 12 analysts stay cautious with a “Hold” rating, one offers a “Moderate Sell,” and two have a “Strong Sell” rating.
The average analyst price target for SMCI is $43.19, indicating a potential upside of 29%. The Street-high target price of $60 suggests that the stock could rally as much as 79%.
On the date of publication, Subhasree Kar did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.