


Rising optimism around Trane Technologies (TT) has been driven by upcoming quarterly earnings, with analysts lifting estimates for both profit and sales and pointing to a solid track record against past expectations.
Recent trading tells a mixed story for Trane Technologies. The share price is around $448.80, with a 1 day move down of 4.8% and a 90 day share price return that is lower by 6.7%. However, the year to date share price gain of 12.8% sits alongside a 5 year total shareholder return of about 163%, which shows a strong long term record even as investors reassess near term expectations ahead of earnings and digest the planned Cancoil acquisition.
Scan how Trane Technologies stacks up against other potential earnings movers with the hand picked 29 high quality undervalued stocks that may be pricing in far less optimism.
Trane Technologies looks like a high quality industrial story, yet the recent pullback and upbeat earnings mood leave a sharper question. Are you now paying a fair price for that strength or a stretch one?
Most Popular Narrative: 15% Undervalued
On the most followed view of Trane Technologies, a fair value of about $526.67 sits comfortably above the recent $448.80 share price. This view places more weight on backlog, services and capital projects than the market seems to be doing today.
Trane Technologies is poised for significant growth in the Commercial HVAC segment, with current record enterprise bookings growth of 37% year over year, a US$12.1b backlog that is up 70% year over year, and sustained strength in Americas commercial and applied bookings supporting potential future revenue and earnings.
See why 38 investors see Trane Technologies as 15% undervalued.
Result: Fair Value of $526.67 (UNDERVALUED)
Still, that upbeat Trane Technologies narrative can crack if commercial HVAC bookings tied to data centers slow or if pricing fails to offset cost and regional mix pressure.
Find out about the key risks to this Trane Technologies narrative.
Another View: What Trane Technologies’ P/E Is Telling You
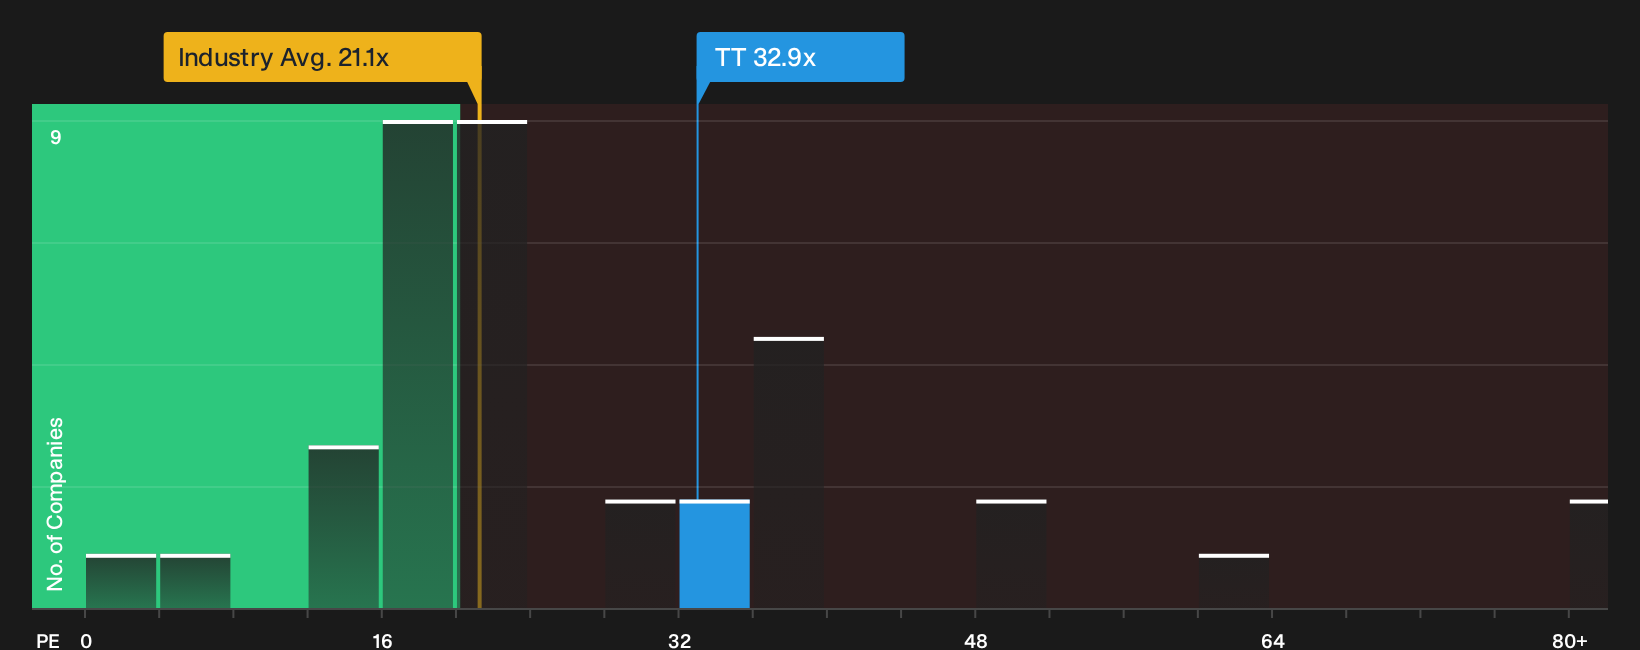
On a simple earnings multiple, Trane Technologies looks less forgiving. The P/E sits at 32.9x compared with 30.1x for close peers and 21.1x for the broader US Building group, while the fair ratio is 30.4x. That richer tag suggests less room for error if the growth story cools.
For a closer look at how these earnings multiples stack up against the fair ratio and sector, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The story so far around Trane Technologies leans optimistic, yet the valuation gap and rich P/E leave plenty of room for your own judgment. If you want to see why some investors are focusing on the positives, take a closer look at the 3 key rewards.
Looking for more investment ideas beyond Trane Technologies?
If Trane Technologies has sharpened your thinking on price versus quality, use that momentum and line up a few more contenders before the next move passes you by.
- Target reliable income by scanning companies that resemble dividend fortresses through the 6 dividend fortresses and compare their payouts and resilience for yourself.
- Hunt for mispriced quality by running the 20 high quality undiscovered gems which highlights lesser known businesses with strong fundamentals that the crowd may be overlooking.
- Protect your downside by filtering for sturdier balance sheets using the list of solid balance sheet and fundamentals (26 results) so you are not caught off guard when conditions get tougher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com