


Q3 update reframes the Bureau Veritas investment story
Bureau Veritas (ENXTPA:BVI) reset the conversation around its shares after reporting double-digit Q3 2026 revenue growth, confirming its outlook and lifting longer term revenue ambitions at its Capital Markets Day.
Management also spotlighted organic expansion, AI focused services and new energy data partnerships as potential future revenue drivers. For you as a shareholder or potential buyer, the question is how much of that story is already reflected in the current price.
That optimism has fed into the tape. Bureau Veritas now trades at €29.35, with a 90 day share price return of 8.78% and a 1 year total shareholder return of 6.24%. The 3 year total shareholder return of 51.72% points to momentum that has been building over a longer stretch as buybacks, new partnerships and the recent Q3 beat reshape how investors weigh both growth potential and execution risk.
Compare how Bureau Veritas stacks up against other quality operators by scanning our hand picked 223 resilient stocks with low risk scores that pair resilient balance sheets with more measured risk profiles.
Bureau Veritas now sits between a bullish story built on Q3 momentum, AI ambitions and buybacks, and a bear case that calls this a fully priced rerating. Consider which side today’s numbers support as you think about valuation next.
Most Popular Narrative: 11% Undervalued
Bureau Veritas closed at €29.35, while the most followed narrative pegs fair value closer to €32.95, so you are being asked to weigh a modest valuation gap against the quality of the growth story that sits behind it.
The company's rapid expansion into high-growth areas such as sustainability and cybersecurity services positions it to capture outsized revenue gains and potential margin uplift as client demand for ESG reporting, supply chain audits, renewable energy projects, and cyber assurance intensifies globally.
Ongoing complexity and globalization of supply chains is driving customer demand for risk mitigation, supply chain resilience assessment, and certification solutions, reinforcing Bureau Veritas's role as a trusted third-party, which is described as boosting both revenues and recurring cash flow.
See why 5 investors see Bureau Veritas as 11% undervalued.
Result: Fair Value of €32.95 (UNDERVALUED)
Still, the Bureau Veritas story can crack if currency swings keep distorting reported figures, or if acquisition-heavy expansion drags on integration and margins.
Find out about the key risks to this Bureau Veritas narrative.
Another View: Bureau Veritas through the earnings multiple lens
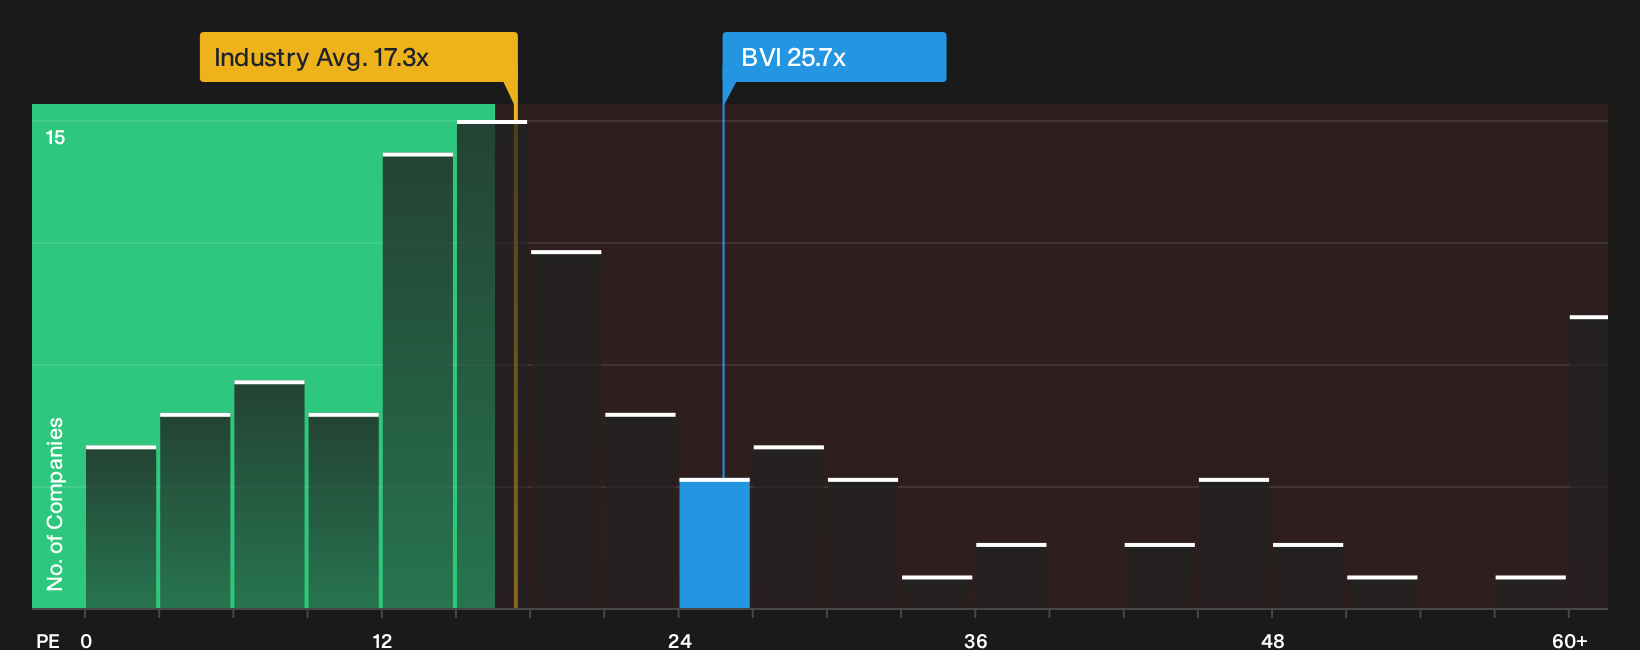
The DCF work suggests Bureau Veritas is undervalued at €29.35, yet the earnings multiple tells a less generous story. The stock trades on a 25.7x P/E, which is higher than the European Professional Services average of 17.6x and above a fair ratio of 21.7x that the market could move toward over time. That mix of discount on cash flows but premium on earnings raises a simple question for you as an investor: Is the bigger risk paying too much for today or underpaying for the future?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Bureau Veritas story so far. For a clearer perspective, look beyond headline reactions to the underlying data and consider both sides using our 2 key rewards and 2 important warning signs
Looking for more Bureau Veritas investment ideas?
If Bureau Veritas has sharpened your focus on quality and risk, widen your watchlist now before the next wave of compelling opportunities moves without you.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (205 results) that can help anchor your portfolio.
- Hunt for mispriced quality by reviewing the 195 high quality undervalued stocks that may offer more attractive entry points than headline stocks.
- Build a passive income stream with staying power by checking companies in the 225 dividend fortresses that combine yield with financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com