


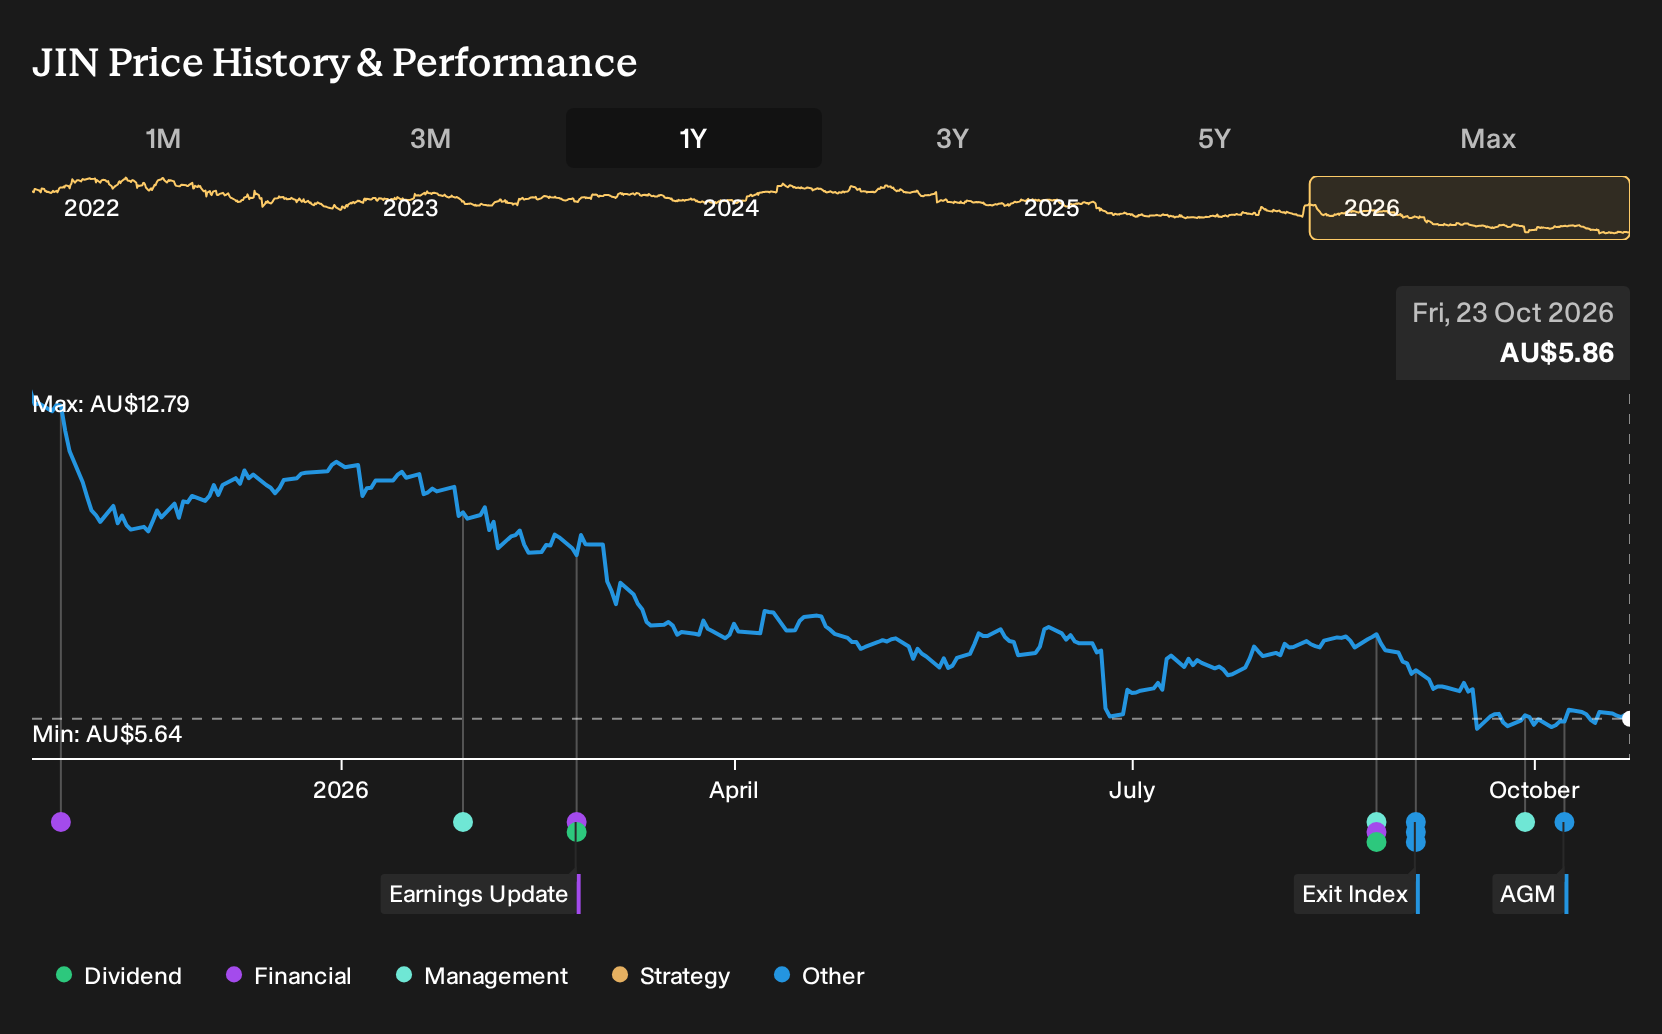
If you had backed the bullish July 2025 case for Jumbo Interactive and held on through a year of volatile headlines, the outcome was harsh. Investors who held Jumbo Interactive over the past year are down 52.6%, including dividends. That slump sits awkwardly beside forecasts of rising earnings, fatter profit margins, and supportive P/E assumptions. If those were the pillars of your thesis, which specific expectations about growth, regulation or digital adoption proved too optimistic?
Jumbo Interactive has already moved. See which of 5 high quality undervalued stocks still trade below our estimates.
What You Would Have Been Weighing Up With Jumbo Interactive
The shares cost A$12.77 at the start of the period, so anyone looking at Jumbo Interactive then had to decide which story felt more realistic.
The bullish view saw digitalization and AI as growth engines and treated a Fair Value of A$14.6, based on optimistic assumptions, as reasonable if rapid online lottery adoption and higher player lifetime value continued.
The cautious camp anchored on a Fair Value of A$11 and focused on tightening regulation, slower lottery interest among younger players, and the risk of regulators pulling sales in-house.
What The Results Changed For The Jumbo Interactive Thesis
Fresh guidance was the big swing factor. Jumbo Interactive increased its FY26 underlying EBITDA outlook to A$82 million to A$85 million, helped by stronger US Dream Giveaway and Canadian managed services earnings, which backed the bullish argument around international SaaS and services. The latest half told a tougher profit story. Revenue reached A$108.21 million while net income slipped to A$19.11 million and net margin moved from 28.4% to 17.7%, so the period cut both ways.
The key lesson is simple. When a Jumbo style thesis leans on margin expansion, do not just watch the top line or contract wins. Track net income and net margin side by side with any guidance upgrades to see whether growth is coming through in quality or only in volume.
What Jumbo Interactive's Lower Price Now Asks You To Believe
Jumbo Interactive now trades at A$5.86, well below where the earlier thesis started and with this Narrative’s Fair Value sitting above the current price on its own assumptions.
The core idea is that jackpots still matter, but international SaaS and managed services carry more weight. A buyer today would be assuming that offshore earnings and prize draw integrations scale roughly in line with the Narrative’s expansion case.
"The main factor that has to go right is continued execution on international expansion and prize draw integration, so that offshore EBITDA from Managed Services and Dream segments grows as guided while reducing reliance on Australian jackpot cycles."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking Beyond Jumbo Interactive
Jumbo Interactive lives on digital tickets and tight timing. Your exposure shifts with when players decide to participate.
Step aside, and an unnamed travel business also depends on customer prepayments. Travellers often hand over cash long before their trips depart.
That money rests on its balance sheet until holidays actually occur. It can resemble strong cash generation, yet much of it funds future hotel stays.
Both models rely on other people’s money parked in transit. The unresolved issue is how you treat that float when judging resilience.
That argument has a Narrative and a number behind it. → See the company one Narrative values 100% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com