


Barrick Mining has delivered a powerful share price run over the past few years, yet its recent pullback puts fresh focus on what investors are really paying for in terms of cash generation. Using the Discounted Cash Flow (DCF) lens, the key question is whether the current US$38.65 price is adequately supported by the cash the business can produce over time.
- Over the past 3 years the stock has surged 153.4%, which puts a lot of past optimism about Barrick Mining's cash producing ability under the microscope.
- The investment case now leans heavily on how efficiently the miner can turn its asset base and capital spending into steady, predictable cash flows for shareholders.
- Prefer to judge Barrick Mining on earnings? See why Barrick Mining's 9.7x P/E tells a different valuation story.
The issue now is whether Barrick Mining's recent share price level is justified by the cash flows implied by its intrinsic value estimate.
If you want to weigh Barrick Mining's cash flow question against a broader set of producers, compare it to the 35 elite gold producer stocks.
Is Barrick Mining Getting Expensive on Cash Flow?
The Discounted Cash Flow (DCF) approach here starts with what Barrick Mining actually turns into hard cash for equity holders. Over the last twelve months the miner generated a little over $4.6b in free cash flow, so the model is not built on a thin or hypothetical base. The projections then assume this cash engine softens over time rather than climbing aggressively, reflecting a profile that leans more mature than high growth.
Analyst forecasts in the DCF framework point to moderating yearly free cash flows through the early 2030s, with the second stage assuming a gradual step down rather than a sharp cliff. When those future streams are discounted back and compared with today's US$38.65 share price, the DCF output lands modestly below where the stock currently trades. This suggests the market already bakes in a fair amount of optimism about Barrick Mining's ability to keep converting its asset base into cash. Find out what Barrick Mining could be worth using our Discounted Cash Flow (DCF) estimate.
The Barrick Mining Narrative: What Would Justify Today's Price?
Narratives for Barrick Mining pick up where the DCF puzzle leaves off and explain which paths for growth, margins and earnings would need to occur for the stock to be worth meaningfully more or less than it is today. Each one treats Barrick Mining's fair value as a specific thesis about the business that can be revisited over time. This way, you can see how the argument holds up as new information appears on Simply Wall St's Community page.
One of the top community narratives on Barrick Mining: 6% undervalued
"Barrick Mining Corporation delivered one of its strongest quarters in recent years, reinforcing its transformation into a dual gold copper powerhouse…"
Discover why this Narrative puts Barrick Mining at 6% undervalued.
One More Piece Of The Barrick Mining Puzzle To Check
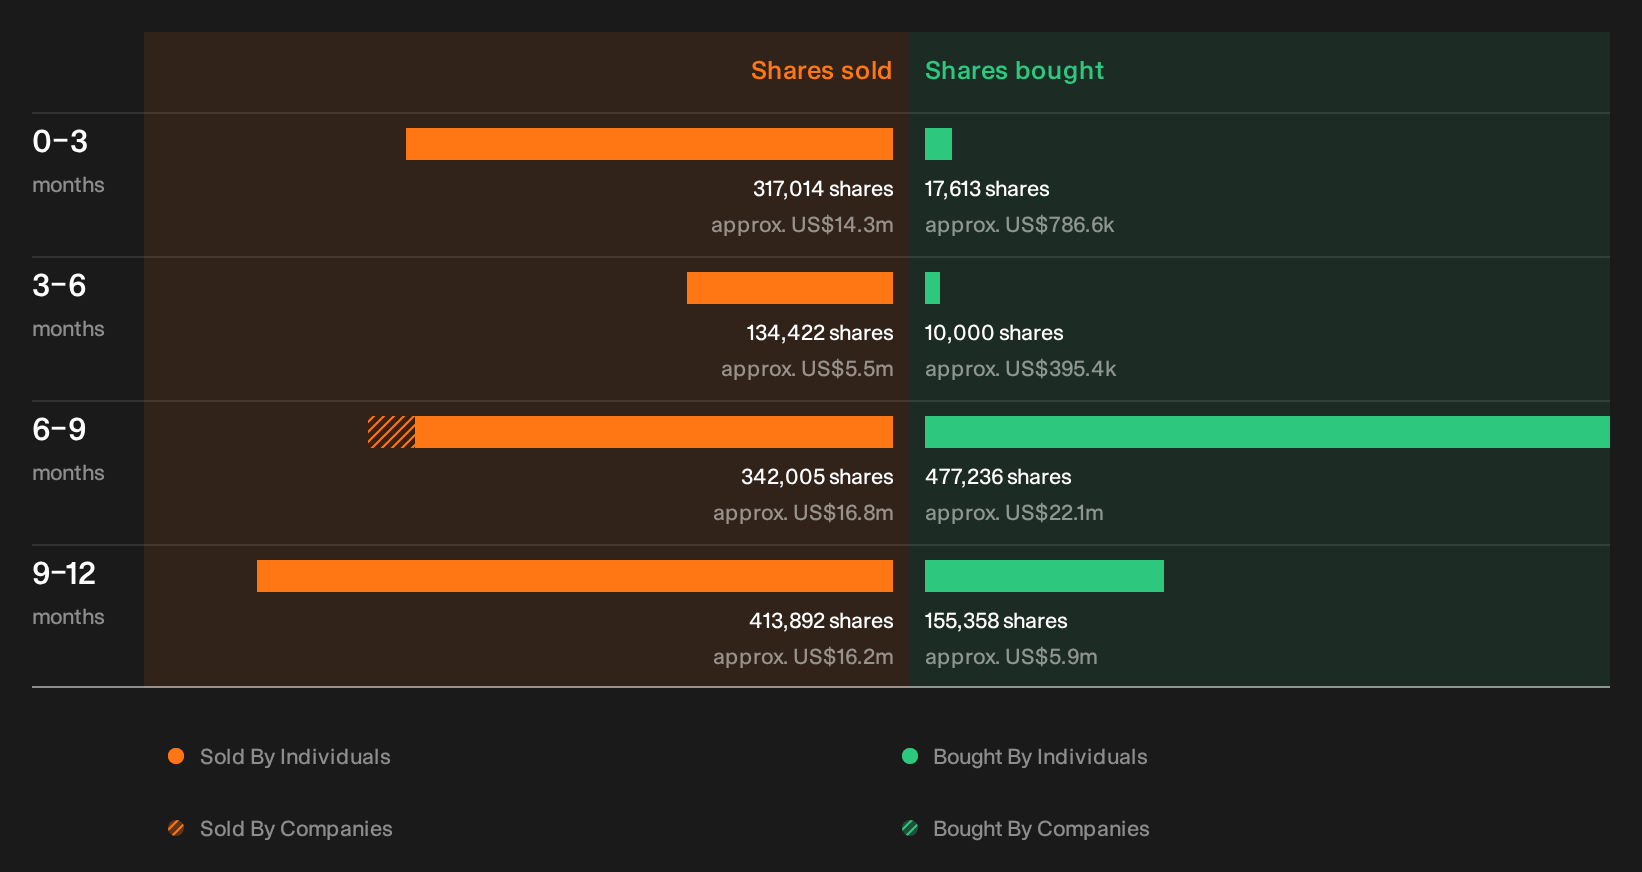
Cash flow and narrative only tell part of the story for Barrick Mining, because recent activity by insiders has raised fresh questions about who is selling, how much, and why it might matter next. See the recent insider selling flagged for Barrick Mining.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com