


Bank of New York Mellon Corporation (BNY) drew fresh attention after reporting higher third quarter and year to date net income and earnings per share, along with guidance that points to 15% growth in net interest income in 2026.
Recent trading has cooled slightly, with the 30 day share price return down 3.23% and the 90 day share price move down 8.55%, even though the year to date share price return sits at 24.16% and the 1 year total shareholder return is 38.59%. This points to strong longer term momentum around BNY as investors weigh its updated earnings guidance and fresh capital actions such as the preferred share issuance, ongoing buybacks and common and preferred dividend declarations.
Scan how Bank of New York Mellon Corporation’s latest earnings, dividends and preferred issuance stack up against a hand picked 6 dividend fortresses with similar income stories and balance sheet strength.
Short term momentum has cooled just as Bank of New York Mellon Corporation is issuing fresh preferreds, retiring shares and pointing to higher net interest income. Does that argue for getting involved now, or for waiting for a cleaner entry?
Most Popular Narrative: 11% Undervalued
Analysts following Bank of New York Mellon Corporation see a fair value of $163.36 against a last close of $145.32. This suggests investors are not fully pricing in the efficiency program and platform model that underpin this narrative.
The ongoing rollout of the platform operating model and dynamic budgeting, which has delivered about US$2b of efficiency savings over four years and underpins a higher 2026 operating leverage guide of 400 basis points, positions BNY to continue converting process efficiency into higher pretax margins and EPS.
See why 43 investors see Bank of New York Mellon as 11% undervalued.
Result: Fair Value of $163.36 (UNDERVALUED)
Still, the narrative around Bank of New York Mellon Corporation can change quickly if fee pressure affects custody and asset servicing, or if sector wide P/E multiples compress further.
Find out about the key risks to this Bank of New York Mellon narrative.
Another View: What The DCF Model Says About Bank of New York Mellon Corporation
While analysts see upside for Bank of New York Mellon Corporation relative to their $163.36 fair value estimate, the Simply Wall St DCF model points the other way. On that framework BNY at $145.32 trades above an estimated future cash flow value of $135.74, which frames the stock as overvalued rather than discounted.
That gap puts the spotlight on what you trust more: the cash generated over time or the earnings multiple the market is willing to pay today, and whether BNY’s execution justifies paying above what the DCF model suggests is a sensible entry point.
Look into how the SWS DCF model arrives at its fair value.
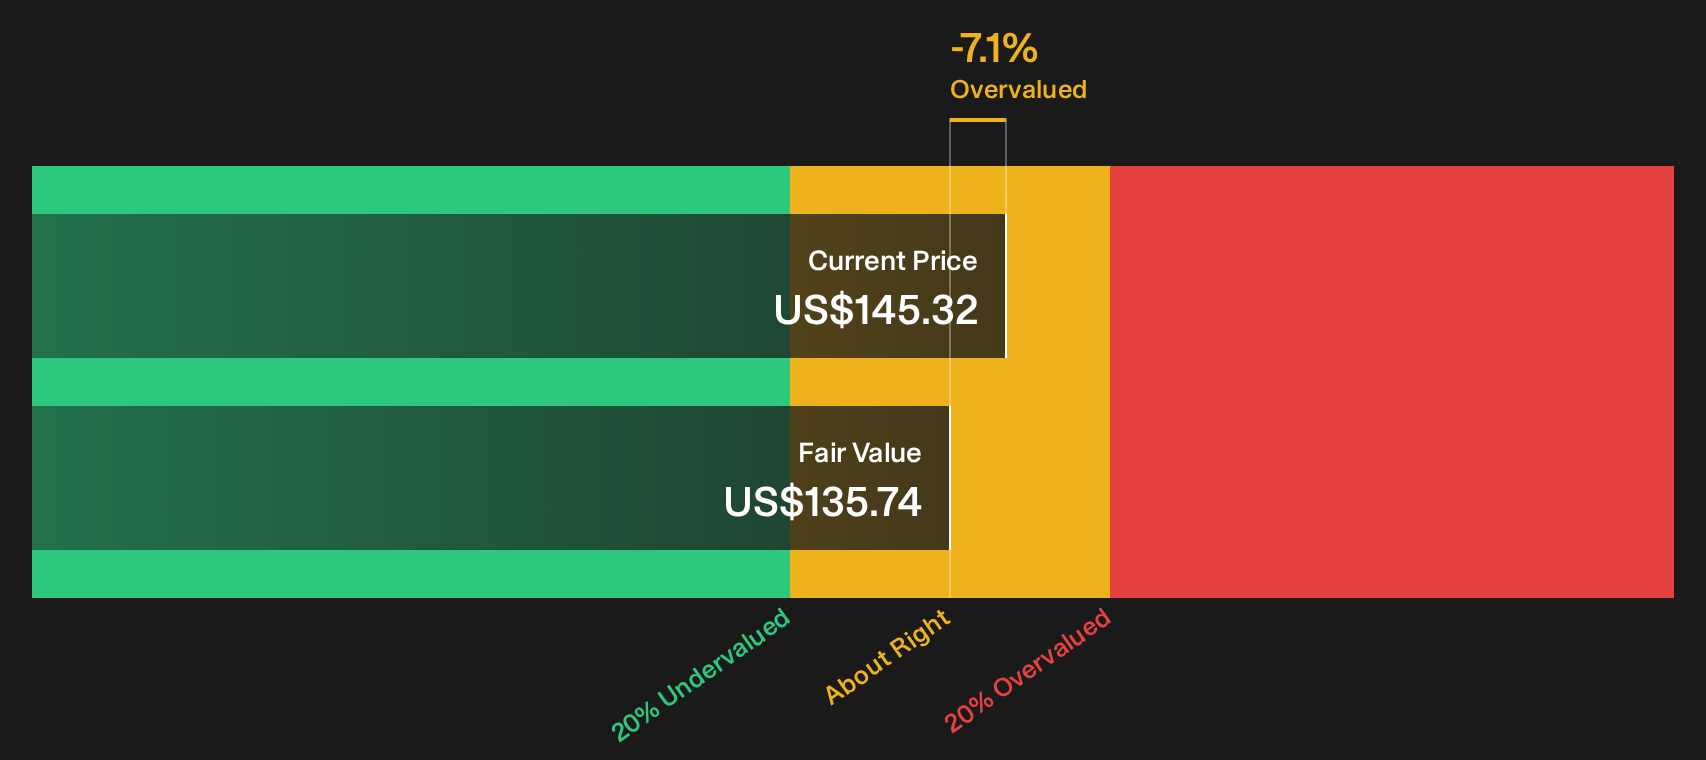
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bank of New York Mellon for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Bank of New York Mellon Corporation can leave you torn, so it is important to act promptly, review the full data set, and weigh both the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Bank of New York Mellon Corporation?
If the cross currents around Bank of New York Mellon Corporation leave you on the fence, broaden your watchlist with other stocks that match your income, value and risk preferences using targeted screeners on Simply Wall St.
- Target dependable income streams by reviewing a curated set of yield focused companies through the 6 dividend fortresses that balance payouts with underlying financial strength.
- Hunt for potential value opportunities by scanning the 29 high quality undervalued stocks that filters for quality businesses trading below their fundamentals.
- Prioritise capital preservation by checking the 30 resilient stocks with low risk scores that highlights resilient companies with lower risk scores before sentiment moves on without you.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com