


- Helios Technologies reported that its unit Enovation Controls was again included in the 2026 Fortune Best Workplaces in Manufacturing & Production list, marking a sixth recognition and a No. 30 ranking in the small and medium category.
- The repeated workplace award for Enovation Controls contrasts with commentary around slow organic growth, shrinking operating margins, and stalled EPS growth at Helios Technologies, highlighting a difference between cultural strengths and current financial pressures.
- We will look at how Helios Technologies' investment narrative intersects with concerns over slow organic growth and pressure on operating margins.
Compare Helios Technologies' current challenges with other industrial players by scanning a curated list of solid balance sheet and fundamentals (26 results) that may be handling margin pressure differently.
Helios Technologies Investment Narrative Recap
For an investor to stay with Helios Technologies, the core belief is that the shift toward electronics, electro hydraulics and higher value controls can offset slow organic growth in more traditional hydraulics. The big near term catalyst is execution on margin discipline and cash generation, especially with recent commentary pointing to shrinking operating margins and stalled EPS.
The largest operational risk is that cyclical end markets like construction, agriculture and recreational vehicles stay soft while cost and macro pressures keep squeezing profitability. The latest workplace award at Enovation Controls is positive for culture but does not materially change these nearer term financial pressures or the main business catalyst.
The most relevant update is Helios Technologies scheduling third quarter 2026 results for release on 5 November 2026, with a call the following day. That event gives you the next concrete checkpoint to see whether recent margin pressure is stabilising, and how management frames demand in construction, agriculture, marine and other cyclical sectors.
This earnings release also matters for testing the narrative that restructuring, automation and a higher electronics mix can support adjusted EBITDA margins above 20% while funding new product launches and potential acquisitions. Any detail on free cash flow, capital allocation and one off items will help you reassess both the near term risk in Helios Technologies and the credibility of longer range growth assumptions.
Helios Technologies' current analyst narrative points to revenues of US$1.0b and earnings of US$116.7 million by 2029. That profile implies 5.0% yearly revenue growth and an earnings increase of about US$45.3 million from current earnings of US$71.4 million.
Uncover why Helios Technologies' fair value indicates a 42% potential upside to its current price, which could narrow quickly.
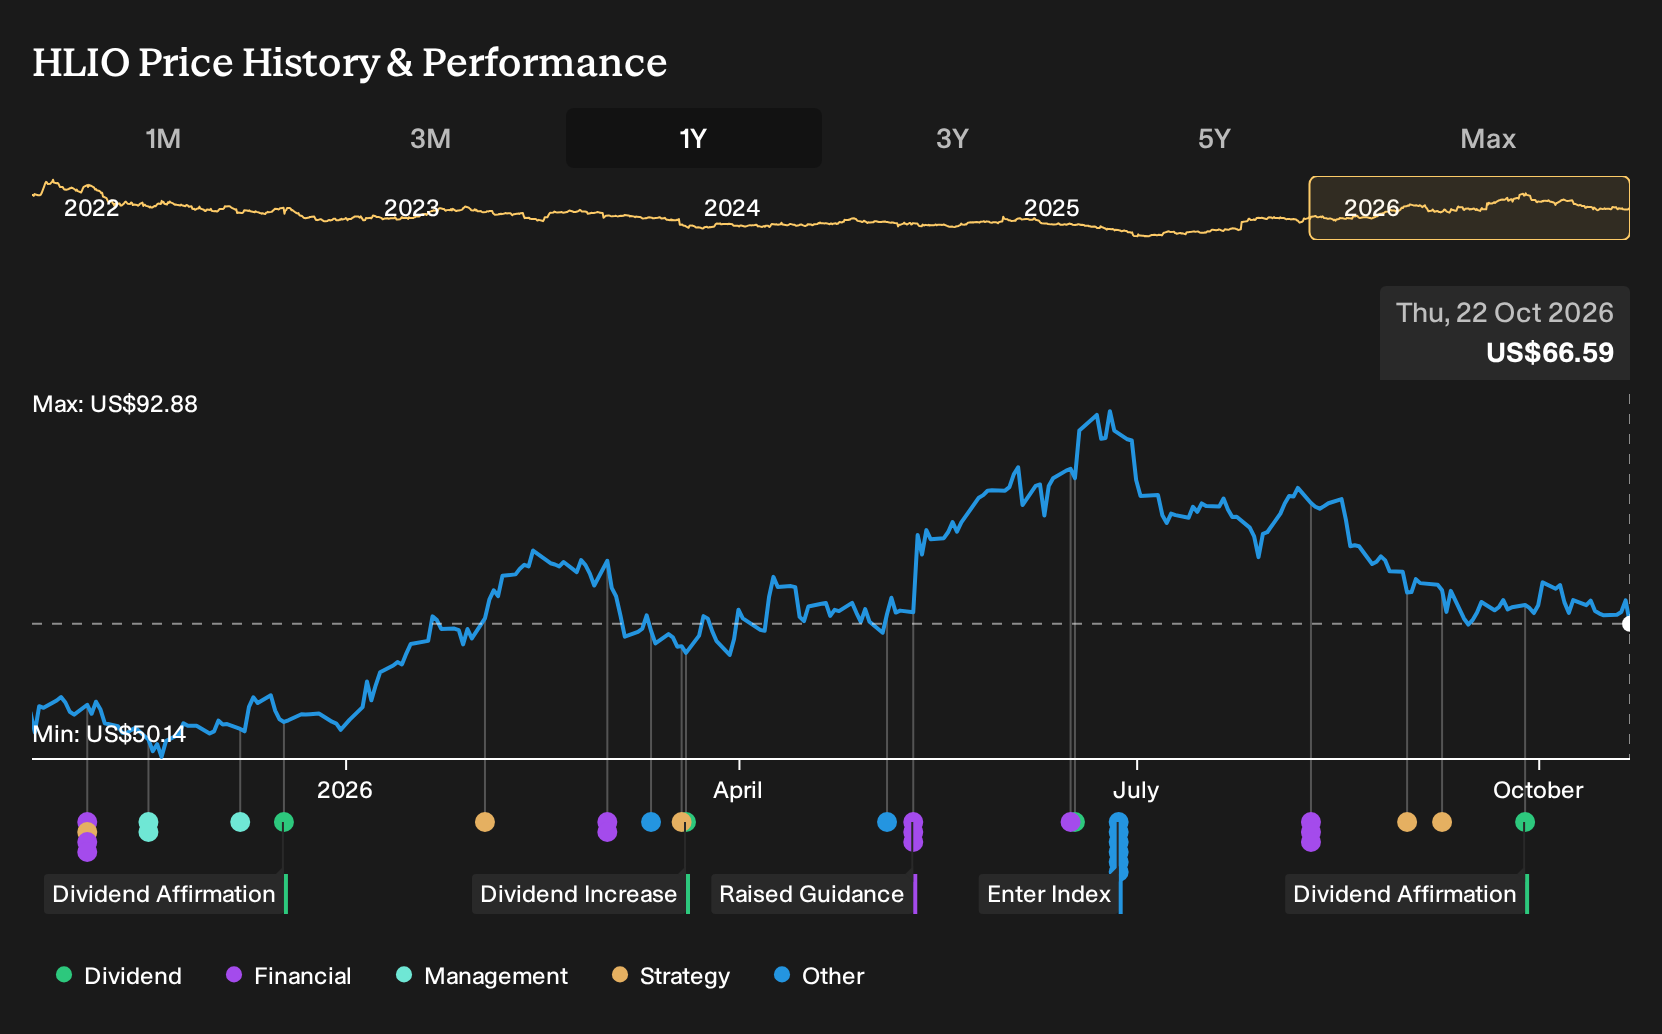
Exploring Other Perspectives
Some of the most optimistic analysts focus on one thing you may want to test against this workplace news at Helios Technologies. They lean heavily on margin expansion, with forecasts that profit margins could reach 11.5% and earnings about US$122.6 million by 2029, so this fresh data point may eventually reshape those expectations.
Explore 2 other Helios Technologies fair value estimates, including one that suggests as much as 64% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Helios Technologies research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Helios Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Helios Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Helios Technologies?
If Helios Technologies has you thinking harder about quality, risk and income, use that same lens across the wider market with the Simply Wall St Screener.
- For investors who want a focus on quality at a reasonable price, scan a curated mix of companies through 29 high quality undervalued stocks that might offer a more attractive risk to reward profile.
- If balance sheet strength is non negotiable for you, filter for resilient businesses using a 30 resilient stocks with low risk scores that keeps an eye on stability first.
- For those hunting for ideas beyond the usual large caps, cast a wider net across smaller high quality prospects using a 20 high quality undiscovered gems that surfaces companies still off most radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com