


- UFP Industries confirmed that Executive Chairman Matthew J. Missad will retire from his employment on December 31, 2026, while remaining Chairman of the Board, and the company affirmed a quarterly dividend of US$0.36 per share payable on December 15, 2026.
- This mix of leadership transition and continued cash returns to shareholders arrives as UFP Industries faces declining revenue, softer earnings per share and reduced returns on invested capital, which places more focus on execution and capital allocation discipline.
- We will now look at how UFP Industries' affirmed dividend, together with its earnings profile, could influence the broader investment narrative.
Contrast UFP Industries' leadership shift and steady dividend with other businesses that pair shareholder payouts with resilient balance sheets using our curated list of solid balance sheet and fundamentals (26 results)
UFP Industries Investment Narrative Recap
To stay on board with UFP Industries, you need to believe the shift toward higher margin composite decking, value added packaging, and ongoing cost cuts can offset softer construction exposed demand and pressure from transport and energy expenses. The short term swing factor is execution in those mix upgrade and cost programs, as earnings for the upcoming quarter are expected to decline even with revenue growth.
The biggest near term risk is that inflation in freight and energy, together with still muted end markets, keeps squeezing margins faster than Deckorators, packaging wins, and the US$60 million cost program can help. The leadership transition to an executive chairman role and then to non executive chair appears relatively contained for operations because continuity on the board is maintained.
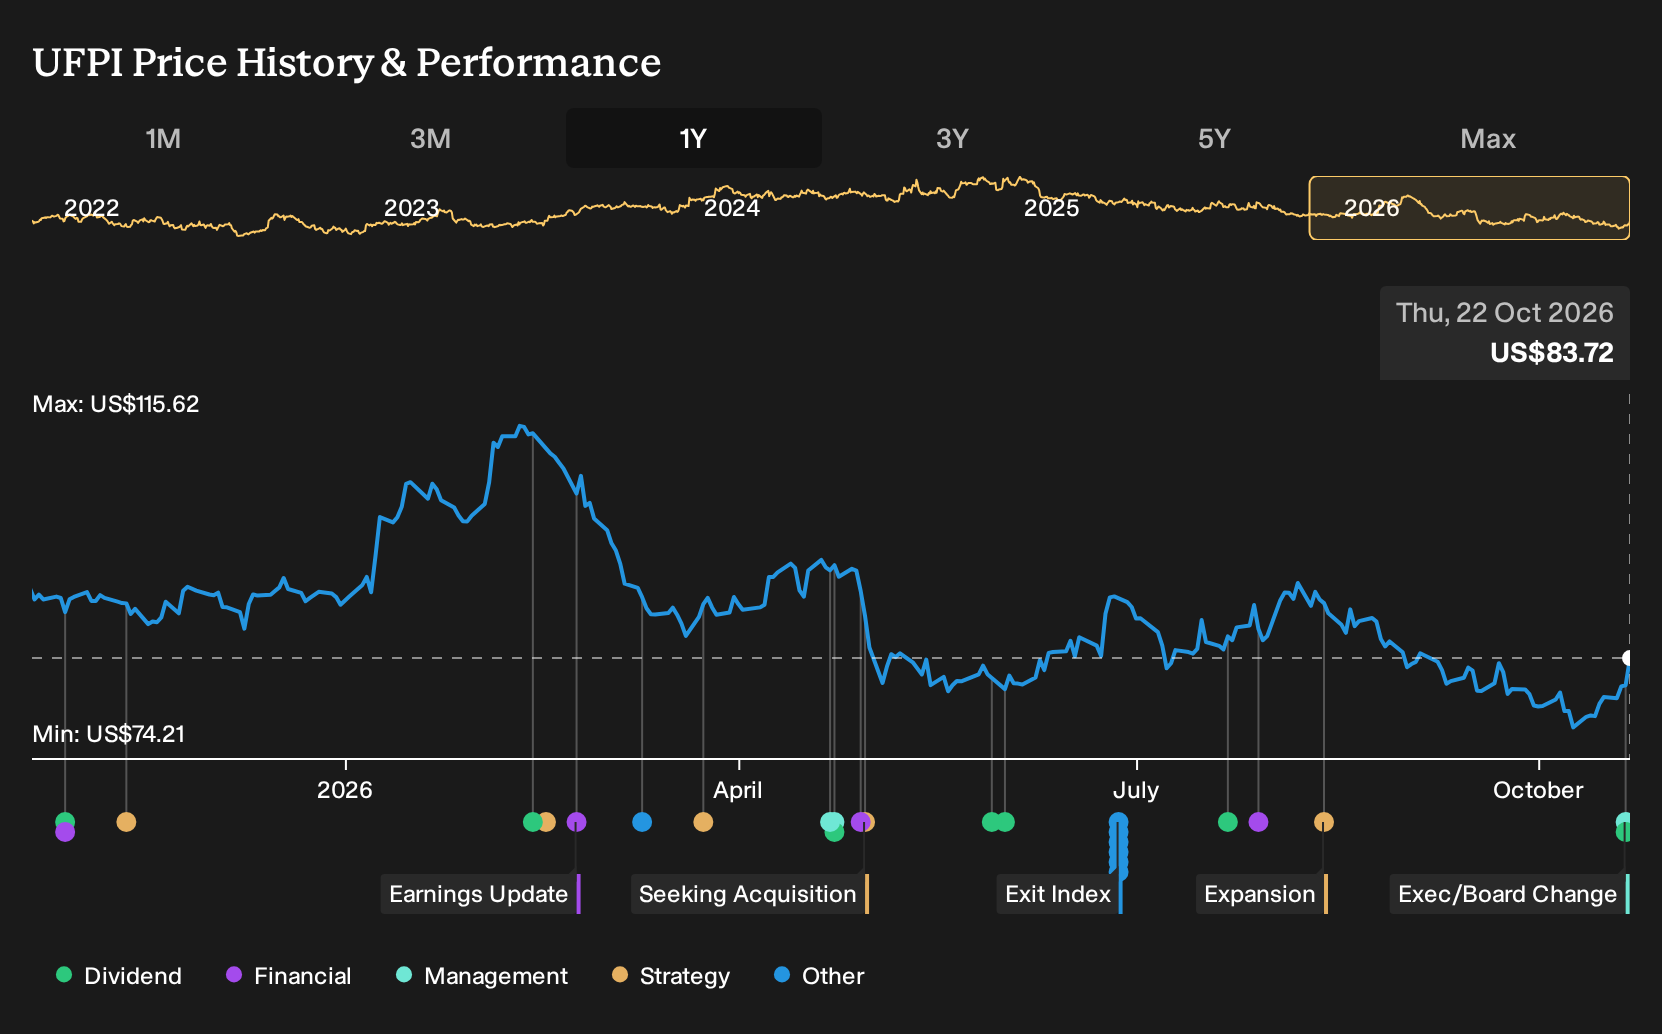
The dividend affirmation of US$0.36 per share for December 15, 2026 is the announcement that matters most here. It indicates that UFP Industries is keeping cash returns in the mix even after a period when revenue, earnings per share, and returns on invested capital have trended lower and the share price has fallen 17% over six months.
For you as a shareholder, that payout only really works if the business side improves. That means the push into Surestone and other composite products, the Deckorators platform, the structural packaging build out, and the remaining US$25 million of targeted cost savings all need to support margins enough that funding the dividend does not compete with reinvestment in the higher value parts of the portfolio.
How UFP Industries' Forecasts Frame The Dividend Question
UFP Industries' current dividend sits against a set of analyst assumptions that sketch out what needs to happen on the income statement over the next few years. The story that gets attention today is not just the payout, but whether the underlying cash generation moves in line with those expectations as leadership shifts and the product mix keeps tilting toward composites and higher value packaging.
Analysts are modelling annual revenue growth of 5.2% over the next three years, with profit margins rising from 3.8% today to 5.3% by about 2029. On that view, earnings would move from US$239.3 million today to US$384.7 million by 2029, while revenues are projected to reach US$7.3b in the same year. That path implies a sizeable uplift in profitability relative to the current earnings base, alongside a gradual improvement in margin quality as more of UFP Industries' activity comes from Deckorators, Surestone and the value added packaging platform.
UFP Industries' narrative projects US$7.3b revenue and US$384.7 million earnings by 2029. This rests on 5.2% yearly revenue growth and a roughly US$145 million earnings increase from US$239.3 million today.
Those projections also assume a lower P/E multiple in the future, with analysts using 16.0x their 2029 earnings estimate compared with 18.5x today. In plain terms, the share price targets do not lean on multiple expansion. They instead rely on the combination of higher earnings, fatter margins and a slightly smaller share count from around 5.31% annual buybacks over the next three years. For you, that mix matters because it ties any potential upside more to operational delivery than to a rising valuation multiple.
The current consensus price target of US$102.6 sits 21.8% above the recent share price of US$80.27, with the spread between the most optimistic and most cautious analyst targets running from US$115.0 down to US$90.0. That range reflects genuine disagreement about how much of the planned cost savings, composite decking growth and packaging expansion will actually show up in earnings by 2029. As you weigh UFP Industries and its dividend, the key question is how comfortable you are with those revenue and profit assumptions compared with the softer sales, earnings and returns the business has reported in recent periods.
Uncover why UFP Industries' fair value indicates a 23% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$101.8 and US$155.7, with one end suggesting only modest upside and the other implying a much richer view of UFP Industries. When you layer persistent cost pressure and leadership change on top, you can see why opinions differ so widely. Explore those alternative viewpoints before setting your own stance.
Explore 2 other UFP Industries fair value estimates, including one that suggests it could be worth just $101.80!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your UFP Industries research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for UFP Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UFP Industries' overall financial health at a glance.
Looking for more investment ideas beyond UFP Industries?
Once you have a view on UFP Industries, it can help to line it up against other opportunities that fit different objectives, from income to resilience to value.
- For investors who want income with staying power, review companies that our screener flags as potential 6 dividend fortresses and see how their payouts compare.
- If capital preservation and a steadier ride matter most to you, check out stocks that screen as 30 resilient stocks with low risk scores and assess how their profiles stack up against your tolerance for swings.
- When you are hunting for quality at a discount, scan through our 29 high quality undervalued stocks and see which businesses warrant a closer look on your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com