


- Cheniere Energy Partners, through Cheniere Energy Inc., has been developing the SPL Expansion Project at Sabine Pass, aiming to lift total liquefaction capacity to over 50 mtpa of LNG by phasing in new infrastructure including Train 7 and a boil-off gas re-liquefaction unit.
- The first phase centered on Train 7, with more than 6 mtpa of expected LNG capacity. This points to a larger fixed cost base and greater volume leverage, which could sharpen how investors think about Cheniere Energy Partners’ long-term contract coverage and project execution risk.
- We will now look at how Cheniere Energy Partners’ investment narrative could shift as Train 7 reshapes Sabine Pass capacity and risk.
What Is Cheniere Energy Partners' Investment Narrative?
To own Cheniere Energy Partners, you need to be comfortable with a capital heavy LNG export operation that lives and dies on long term contracts, reliable plant performance, and global demand for shipped gas. The SPL Expansion Project, starting with Train 7 and the boil off gas re liquefaction unit, fits directly into that story by scaling Sabine Pass beyond 50 mtpa and increasing volume leverage on an already large fixed cost base.
In the near term, the big swing factors remain execution risk on that new build, timing and terms of incremental offtake contracts, and how comfortably cash flow covers debt and distributions. Earnings have grown strongly in recent years and the P/E around 11.7x screens as good value versus the broader US market. However, analysts currently expect profit to decline over the next few years, which makes smooth delivery of the expansion even more important.
That said, there is a less obvious pressure point in the story that only really shows up once you look closely at ...
There's only one way to know the right time to buy, sell or hold Cheniere Energy Partners. Head to Simply Wall St's company report for the latest analysis of Cheniere Energy Partners's Fair Value.
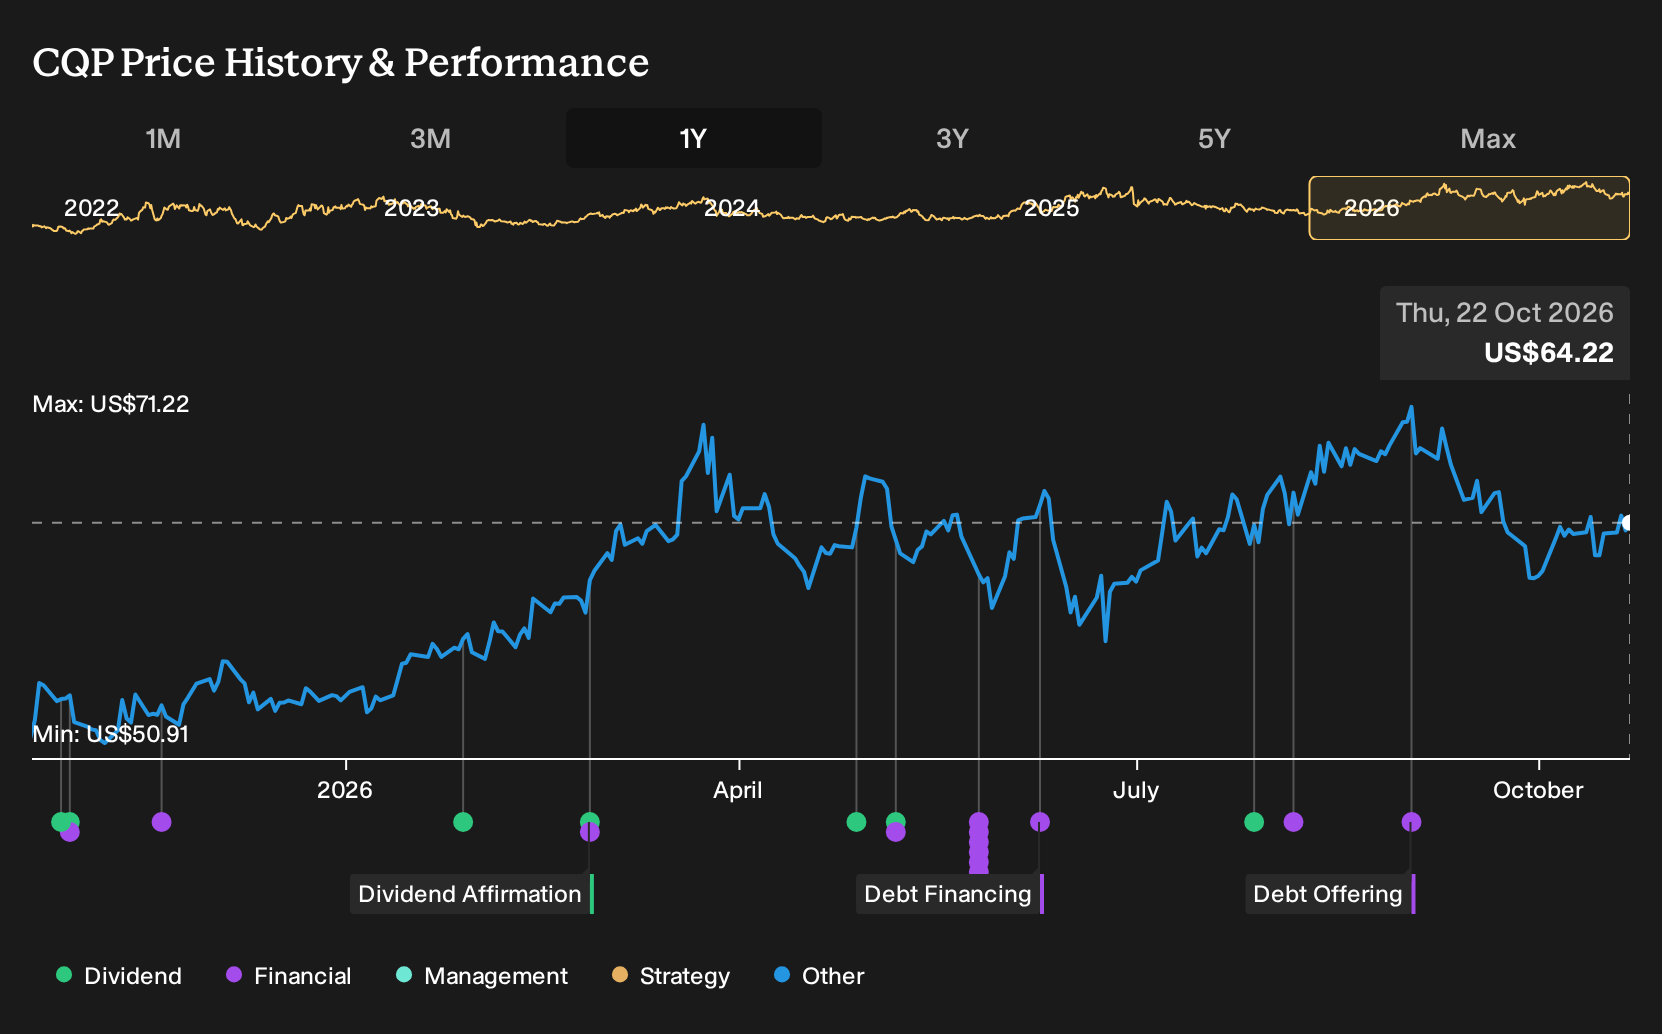
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community stretch from US$2.42 to US$60 per unit, which shows how far apart retail investors can be on Cheniere Energy Partners. Those views were formed before the Sabine Pass expansion update, so reassess them in light of the larger LNG footprint and what that could mean for earnings resilience and contract visibility.
Explore another Cheniere Energy Partners fair value estimate, including one estimate that suggests it could be worth as much as $60.00.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Cheniere Energy Partners research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Cheniere Energy Partners. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cheniere Energy Partners' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cheniere Energy Partners?
Once you have a view on Cheniere Energy Partners, it can help to line it up against a few different types of opportunities so you see where the risk and income profile really fits in your portfolio.
- Prefer quality at a reasonable price, with a focus on fundamentals that look robust on both cash flow and balance sheet strength, by scanning our 29 high quality undervalued stocks.
- If income stability matters most to you, compare CQP's payout with other companies that offer a 6 dividend fortresses.
- For a focus on resilience and lower overall risk, filter for companies that pass strict financial health checks using our 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com