


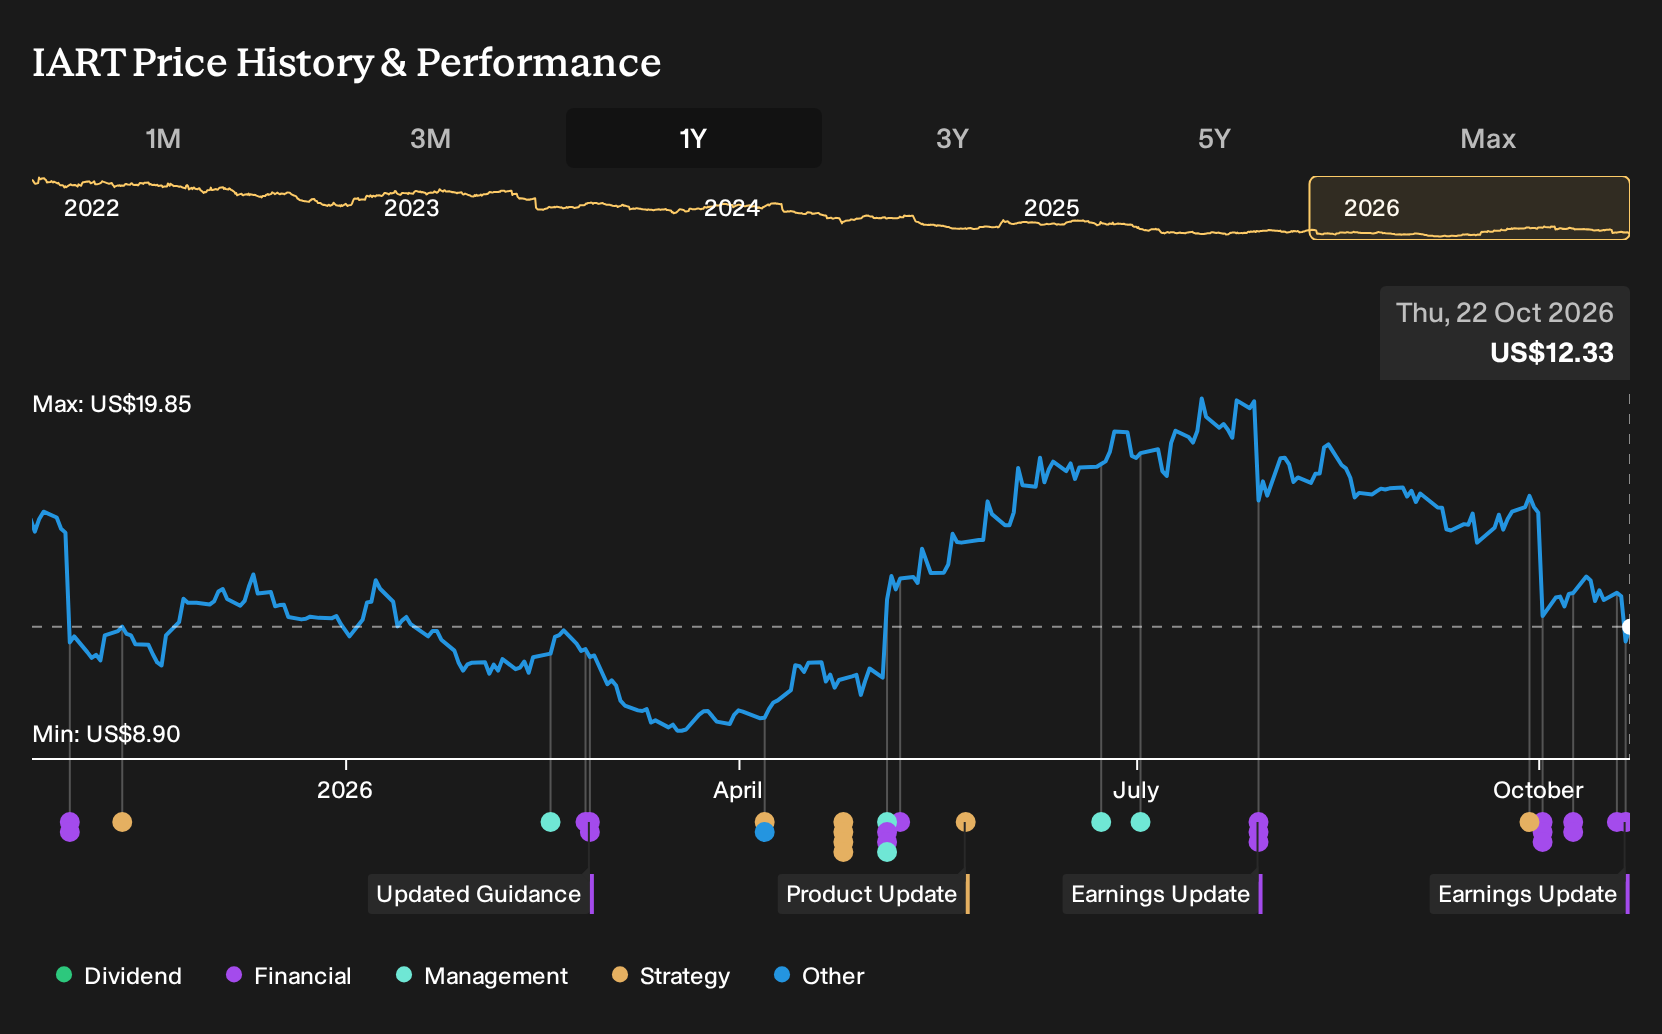
If you had decided on 22 October 2025 to skip Integra LifeSciences because the bullish and bearish analysts seemed too far apart, the outcome might look deceptively simple now. For Integra LifeSciences shareholders, the loss over the past year was 22.4%, including dividends. That result sits against a year that included upbeat earnings, raised guidance, and then a sharp drop after flood damage and legal probes. Which early warning or assumption in those 2025 narratives would you focus on to judge Integra differently?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Integra LifeSciences is not the only name tied to this theme. Zero in on 36 healthcare AI stocks and compare how each one is priced.
The Two Integra LifeSciences Stories Investors Were Choosing Between
The shares cost US$15.46 at the start of the period, and anyone looking at Integra LifeSciences then was effectively choosing between two sharply different stories that still both sounded plausible.
On the optimistic side, the bullish Narrative set Fair Value at US$30. It relied on Integra LifeSciences turning supply chain upgrades and the Braintree automation project into lasting cost efficiency and higher margins, as well as capturing more demand in advanced wound care.
The bearish Narrative pointed to a Fair Value of US$10. It focused on regulatory scrutiny, including FDA warning letters and ongoing recalls, along with quality and supply issues that could keep compliance costs elevated and weigh on profitability.
What The Integra LifeSciences Results Put To The Test
Fresh Q3 2026 numbers gave Integra LifeSciences bulls some backing. Revenue was US$411.2 million and net income was US$14.9 million, compared with Q3 2025 revenue of US$402.1 million and a loss of US$5.4 million. Net margin moved from -1.3% to 3.6%, yet later flood damage, lowered 2026 guidance, and legal investigations pointed in the opposite direction. Overall, the evidence cut both ways.
The useful takeaway is simple. When a narrative leans on cost fixes and quality remediation, track net margin and any guidance changes after operational shocks to see if the promised efficiency really holds up.
What You Are Paying For In Integra LifeSciences Today
Integra LifeSciences now trades at US$12.32, with the selected Narrative’s Fair Value sitting above that level based on its own framework rather than a hard fact.
The Narrative leans on Integra turning recent margin repair, cash generation, and product relaunch plans into reliable earnings while steadily cutting debt. A buyer today has to judge whether those improvements can outpace balance sheet pressure enough for the share price fall to reflect opportunity rather than warning.
"The main thing that has to go right is that Integra LifeSciences Holdings turns its compliance and manufacturing recovery into durable growth in Tissue Reconstruction and neurosurgery, while stabilising weaker areas such as ENT and continuing to reduce leverage. The numbers imply the share price already assumes Integra LifeSciences Holdings delivers on structurally higher margins, successful product relaunches, and deleveraging, which leaves limited room for disappointment in execution."
The price and this Narrative do not agree. → Uncover what this Narrative says Integra LifeSciences is actually worth
Beyond Integra LifeSciences’ Recovery Story
Integra LifeSciences is one way to think about medical procedures becoming more specialised. Another angle focuses on where surgeons rely on complex tools.
Hospitals often want not just devices, but systems that make procedures less invasive and more controlled for staff and patients.
One business builds robotic platforms that let surgeons operate through small openings, using detailed imaging and finely tuned instrument control at the console.
It adds software, training programs and data feedback so teams can study techniques, compare outcomes and refine performance over time.
If that kind of ecosystem keeps deepening, your Integra research might sit alongside questions about who shapes how surgeons actually work in practice.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 20% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com