


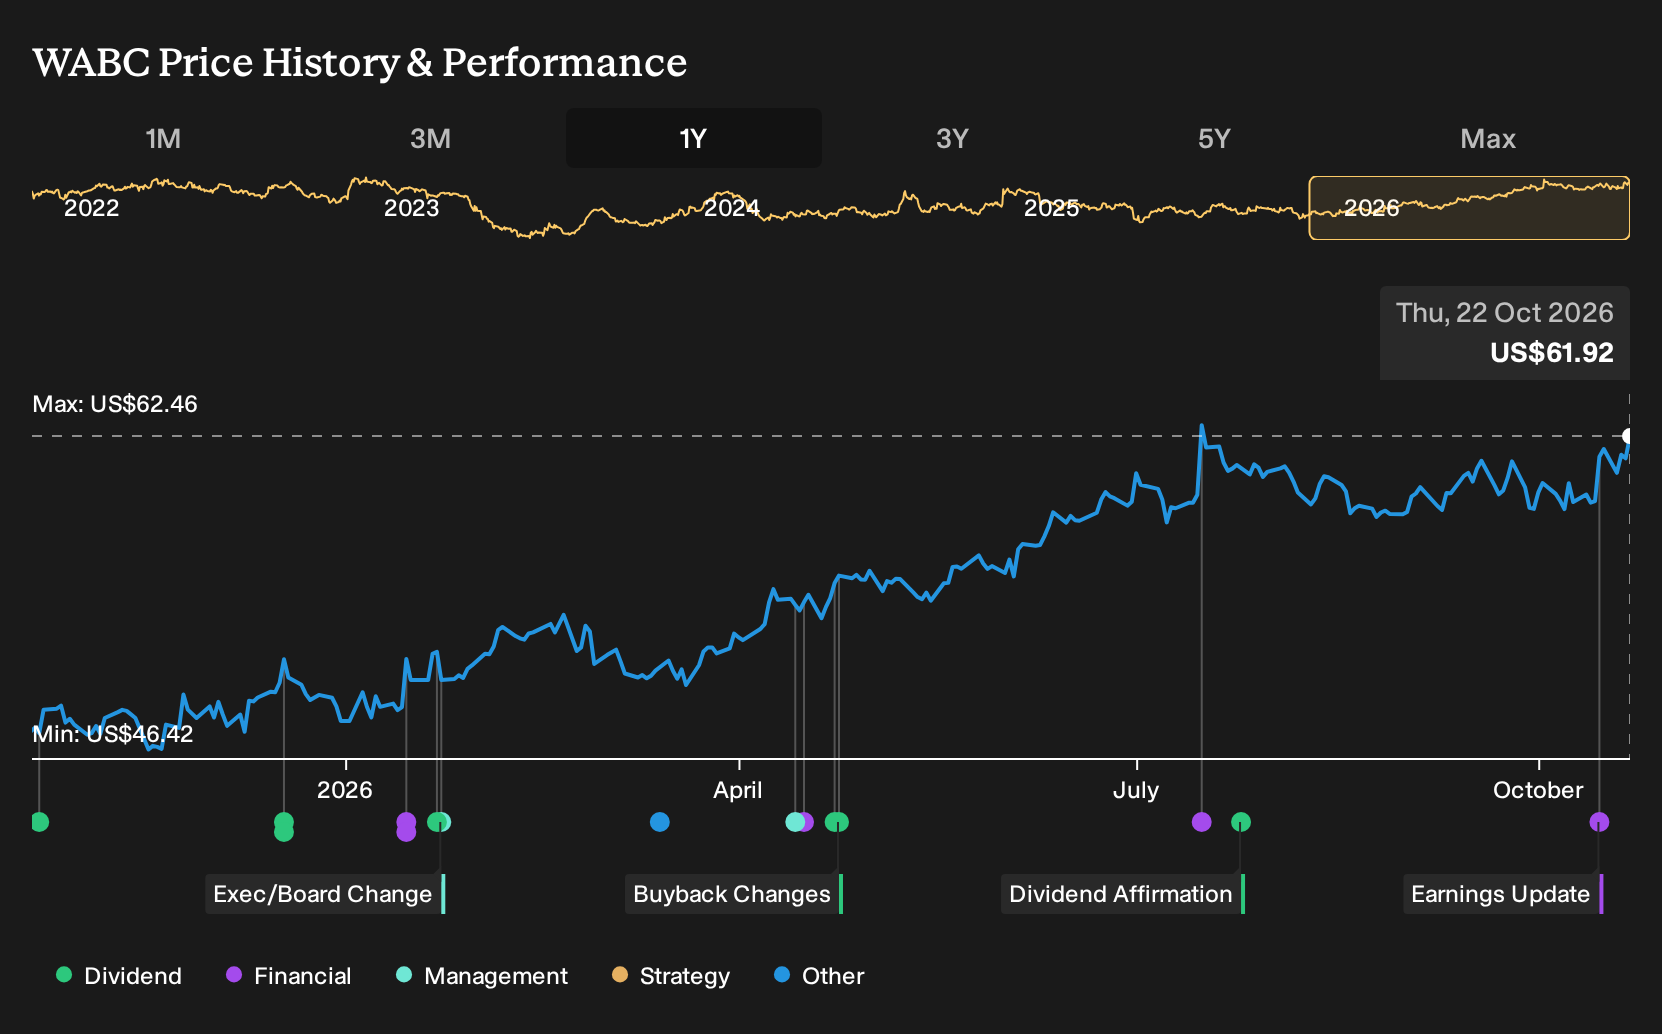
- Westamerica Bancorporation reported third quarter 2026 net income of US$28.15 million with basic and diluted EPS from continuing operations of US$1.22, and the board approved a US$0.48 quarterly cash dividend per share payable on November 13, 2026 to shareholders of record on November 2, 2026.
- Stable earnings per share, alongside the affirmed cash dividend and ongoing share repurchases, highlight how Westamerica Bancorporation continues to return capital to shareholders while keeping profitability relatively steady year over year.
- Attention now turns to how Westamerica Bancorporation's steady EPS and maintained dividend shape the broader investment narrative around the bank.
What Is Westamerica Bancorporation's Investment Narrative?
To own Westamerica Bancorporation, you have to be comfortable with a slower growth, income first banking model built on deposits and a tightly managed loan book. The latest quarter shows that pattern. Net income for the third quarter was US$28.15 million, similar to a year earlier, while basic and diluted EPS from continuing operations moved to US$1.22. The reaffirmed US$0.48 dividend and ongoing share repurchases, including 51,000 shares bought in the latest tranche, point to a board that keeps capital returns front and center rather than chasing rapid expansion.
In the short term, this dividend decision does not radically change the key drivers. Earnings trends, funding costs, credit quality, and how Westamerica Bancorporation prices loans against that backdrop still matter more than a single quarter’s payout decision. Forecasts that revenue and earnings may grow more slowly than the broader US market underline that the story is about stability and income rather than high growth, which makes execution on credit risk and capital allocation the real swing factors.
That said, the appeal of that steady dividend profile has to be weighed against one uncomfortable possibility that sits just beneath the surface.
There's only one way to know the right time to buy, sell or hold Westamerica Bancorporation. Head to Simply Wall St's company report for the latest analysis of Westamerica Bancorporation's Fair Value.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Westamerica Bancorporation research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Westamerica Bancorporation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Westamerica Bancorporation's overall financial health at a glance.
Looking for more investment ideas beyond Westamerica Bancorporation?
If Westamerica Bancorporation appeals as an income anchor in your portfolio, it can help to line it up against other candidates that match different return profiles, risk levels, and balance sheet strengths using the Simply Wall St Screener.
- For investors who want income without stretching too far on quality, start by scanning a 6 dividend fortresses that focus on resilience as much as yield.
- If value is your priority, compare Westamerica Bancorporation with a 29 high quality undervalued stocks that pair solid fundamentals with discounted prices.
- For a defensive core around any bank holding, round out your watchlist with a 30 resilient stocks with low risk scores that score well on financial strength and earnings stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com