


Biglari Holdings (BH.A) has drawn attention after recent trading left the share price at US$1,917.20, with short term moves diverging from its gains over the past month and past 3 months.
Recent trading in Biglari Holdings has been choppy, with the share price down 6.46% over the past day and 5.60% over the week. The stock is still showing a 10.01% 30 day share price return and a 7.17% 1 year total shareholder return, which suggests momentum has cooled in the very near term after a strong multi year run that produced a 160.84% 3 year total shareholder return and 133.80% over five years.
Scan for other momentum stories with similar multi year profiles to Biglari Holdings by checking our hand picked list of 29 high quality undervalued stocks that also combine returns with underlying fundamentals.
Biglari Holdings now trades well below one estimate of intrinsic value, yet the latest pullback hints at market hesitation over its mixed operations and recent loss. Is that caution warranted when you compare it with the numbers?
Preferred Price-to-Sales Multiple of 3x: Is it justified for Biglari Holdings?
Biglari Holdings now trades at a P/S of 3x, which looks rich against both its own loss making profile and the Hospitality sector reference points.
The price to sales ratio compares the market value of the equity to the revenue the business generates. For a group like Biglari Holdings, which mixes restaurants, insurance operations, oil and gas assets, and media, that single measure rolls all of those activities into one simple yardstick based only on sales, not profitability.
BH.A currently reports revenue of $405.612m and a net loss of $29.749m. That loss profile means earnings based multiples like P/E do not offer much help, so the valuation burden shifts to sales based markers and cash flow models. In that context, a 3x P/S multiple places a lot of weight on the ability of this diversified structure to eventually turn those revenues into sustainable profits.
The statements show BH.A is described as expensive on this measure versus both peers and the broader US Hospitality group. Management is running an unprofitable operation where earnings have declined by 23.1% per year over the past 5 years, while the stock still trades at a premium sales multiple. That combination indicates the market is paying up relative to sector norms despite weaker profitability, rather than applying a discount that might reflect the current loss making status.
Compared with its peers, BH.A trades on a P/S of 3x against a peer average of 0.9x. Against the wider US Hospitality industry, the gap remains wide, with BH.A at 3x and the industry at 1.6x. Those spreads are large and point to a valuation that is far less forgiving than the group average, even though the business is unprofitable and return on equity is described as negative.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-sales of 3x (OVERVALUED)
Still, the reliance on loss making operations and a premium P/S for Biglari Holdings leaves little margin for error if profitability or segment performance weakens further.
Find out about the key risks to this Biglari Holdings narrative.
Another View on Biglari Holdings Using Cash Flows
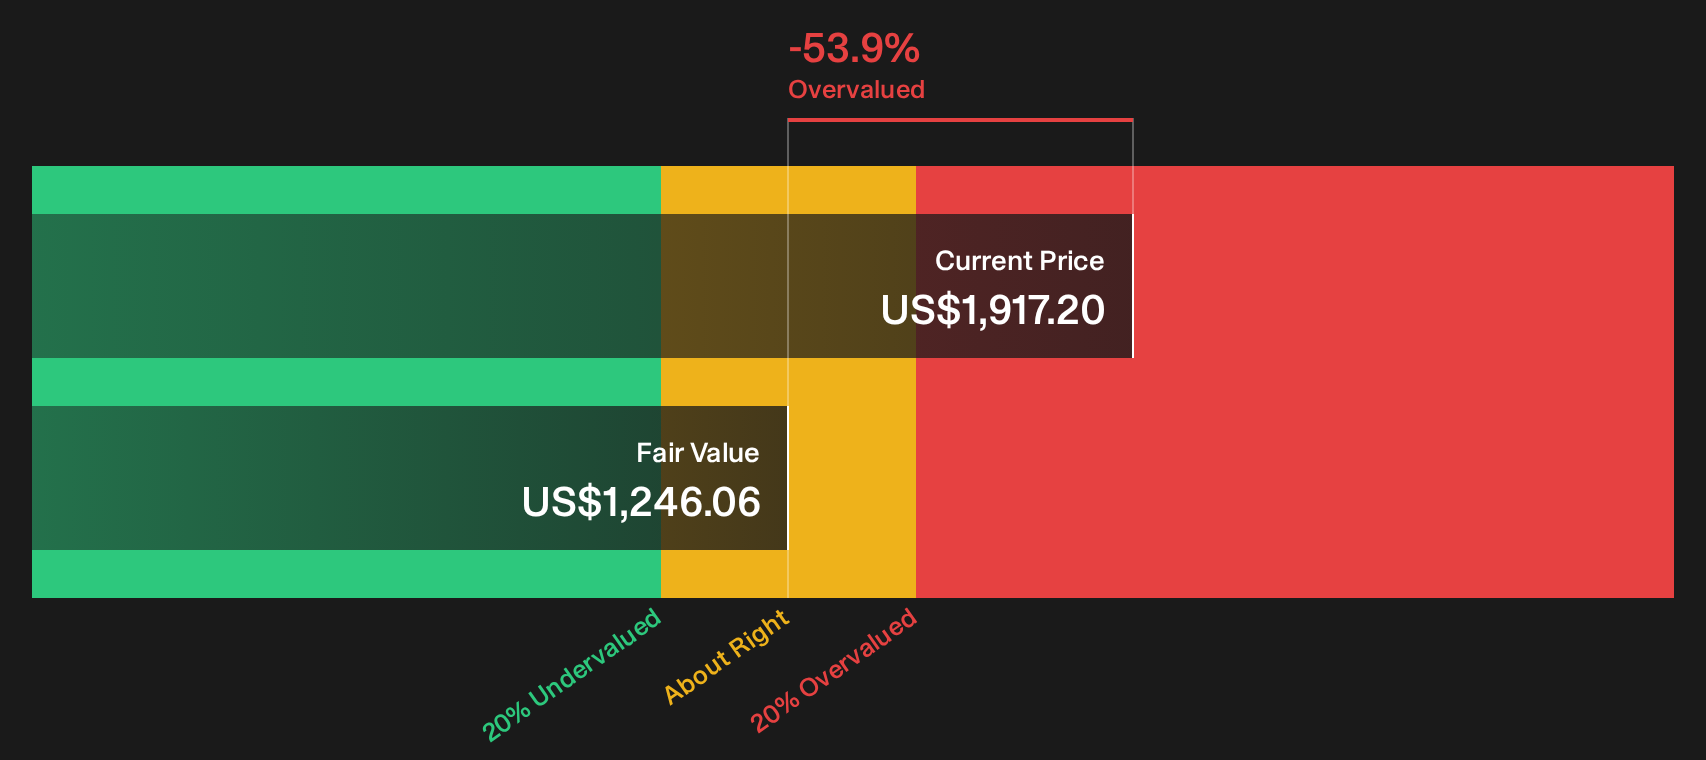
The high P/S multiple paints Biglari Holdings as expensive, and the SWS DCF model points in the same direction. At $1,917.20, the share price sits above an estimated future cash flow value of $1,246.06. That gap reduces valuation cushion. Is this a quality premium or just a rich entry point?
For readers who want to see how a cash flow lens tackles the same question, the SWS DCF model pulls the price apart step by step and can clarify which assumptions matter most for Biglari Holdings right now. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Biglari Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Worried this all sounds a bit one sided on Biglari Holdings, or maybe not cautious enough? Take a few minutes to test the figures yourself, weigh them against your own expectations, then zero in on the 1 important warning sign.
Looking for more Biglari Holdings sized investment ideas?
If Biglari Holdings sharpened your focus on valuation and risk, do not stop here. Broaden your watchlist with fresh ideas that match your own playbook.
- Target potential mispricings by scanning a hand picked 29 high quality undervalued stocks that marry stronger fundamentals with appealing entry points.
- Build income focused exposure by zeroing in on 6 dividend fortresses that aim to pair higher yields with resilient business models.
- Strengthen downside protection by concentrating on a 30 resilient stocks with low risk scores that highlights companies with more durable financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com