


J.B. Hunt Transport Services (JBHT) paired its third quarter earnings release with a fresh look at how it is using cash, highlighting margin pressure alongside dividends and ongoing share repurchases.
Recent updates on earnings, share repurchases and the reaffirmed dividend have landed against a cooling near term trend. The 30 day share price return is down 2.9% and the 90 day share price return is down 20%, even as the 1 year total shareholder return sits at 39.4% and the 3 year total shareholder return at 41.5%. Together, these figures point to longer term holders still sitting on sizeable gains while short term momentum in J.B. Hunt Transport Services has faded.
Scan how J.B. Hunt Transport Services compares with other cash returning haulers and logistics players by reviewing our hand picked list of 6 dividend fortresses in this space.
J.B. Hunt Transport Services now trades below both analyst targets and an internal fair value estimate after a sharp pullback. The real issue is whether that gap reflects opportunity or lingering concern about margins and cash generation.
Most Popular Narrative: 18% Undervalued
Against J.B. Hunt Transport Services' last close of $230.59, the most followed narrative pins fair value closer to $282. This frames the recent pullback as a valuation gap built on future cash flows and margin repair rather than short term trading swings.
The continued focus on equipment utilization and cost-to-serve initiatives, which have already removed more than US$135 million of structural costs, provides further room for efficiency gains that can support net margins as volumes move through the network.
The AI freight execution platform that J.B. Hunt Transport Services has rolled out across all business units is designed to automate load coordination and customer communications, which can improve asset utilization and contribute to higher earnings power over time.
See why 5 investors see J.B. Hunt Transport Services as 18% undervalued.
Result: Fair Value of $282.17 (UNDERVALUED)
Still, the sharp share price drop after the September 2026 earnings warning and the ongoing securities class action investigations could both challenge the bullish narrative for J.B. Hunt Transport Services.
Find out about the key risks to this J.B. Hunt Transport Services narrative.
Another View: What J.B. Hunt’s P/E Is Telling You
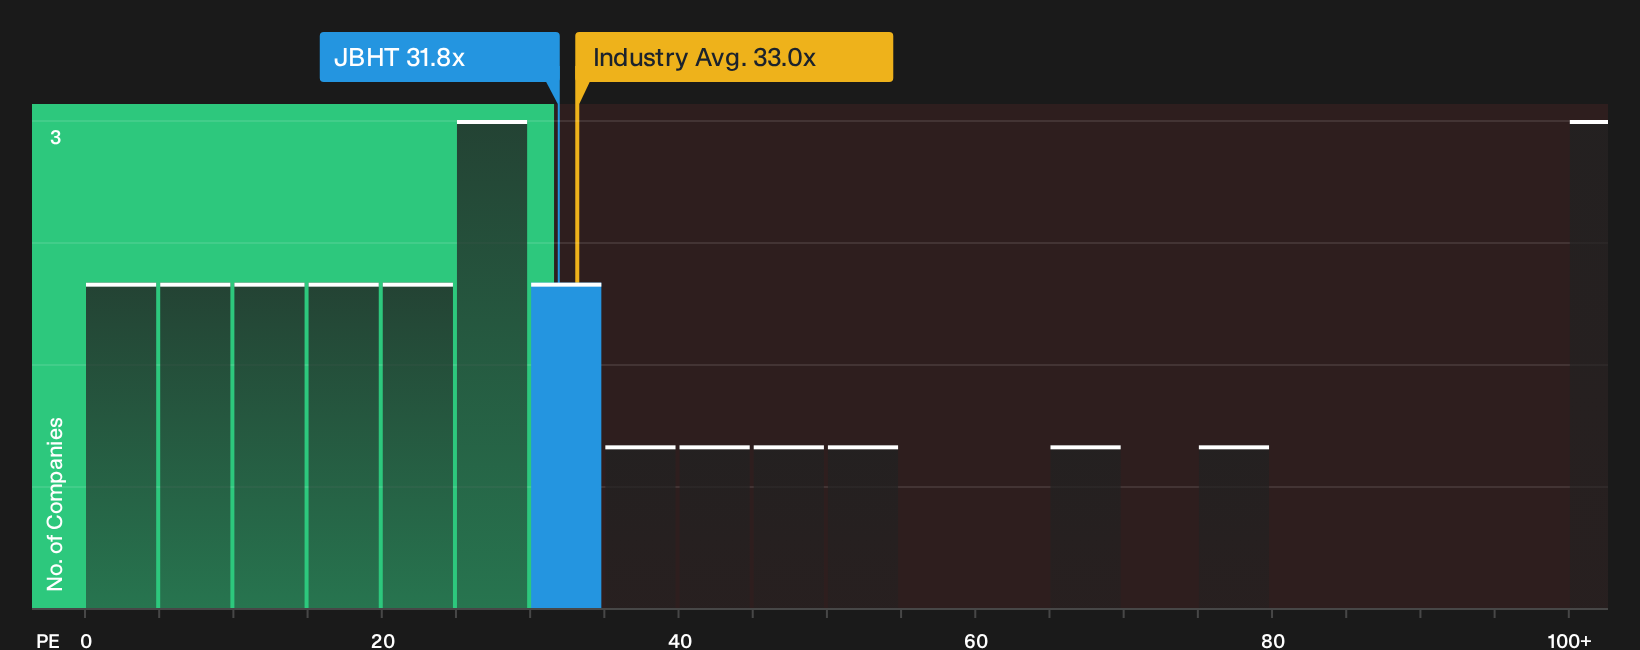
The cash flow and analyst fair value work present J.B. Hunt Transport Services as undervalued, yet its 31.8x P/E is well above a fair ratio of 20.2x and only slightly below the US Transportation average of 32.4x. That gap points to valuation risk if sentiment cools further, or room for catch up if earnings progress as expected. Which side of that tradeoff feels more convincing to you?
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If sentiment across J.B. Hunt Transport Services feels mixed after recent moves, do not wait for consensus to harden before forming your own view. Start by weighing the upside case that centers on 4 key rewards
Looking for more J.B. Hunt Transport Services style investment ideas?
Do not stop with a single freight operator when there are tools that can help you quickly surface other opportunities that match your own risk and return preferences.
- Chase potential mispricing by scanning a curated set of 29 high quality undervalued stocks that combine solid fundamentals with prices that lag underlying business quality.
- Protect the downside by filtering for companies in the 30 resilient stocks with low risk scores that pair modest volatility with more resilient financial profiles.
- Get ahead of the crowd by checking a 20 high quality undiscovered gems that highlights quality businesses investors are not widely focused on yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com