


Origin Bancorp (OBK) heads into its October 28 quarterly update with investors focused on forecasts for year over year gains in both earnings and revenue, set against mixed expectations and uncertain odds of an earnings beat.
Recent trading has cooled slightly, with a 30-day share price return of 4.7% down and a 7-day move lower as investors weigh the October 28 earnings risk. Even so, Origin Bancorp still carries a strong year to date share price gain of 37.81% and a 1-year total shareholder return of 57.89%. This points to momentum built over a longer stretch rather than just a short burst around this quarter.
Capitalize on the interest around Origin Bancorp's earnings setup by sizing up other bank stocks that combine momentum with balance sheet strength through our curated list of solid balance sheet and fundamentals (26 results).Origin Bancorp has run hard over the past year, yet the shares still trade below both analyst targets and some fair value estimates. Is that discount a margin of safety, or a signal the market sees real risk?
Most Popular Narrative: 12% Undervalued
Origin Bancorp is priced at $51.87, while the most followed narrative anchors fair value closer to $59.20 using a 7.24% discount rate. That gap frames the earnings release as a test of whether the business can keep justifying a higher valuation through capital returns and balance sheet discipline.
High tangible common equity of 11.1%, fifteen consecutive quarters of tangible book value per share growth to $36.37 and an expanded share repurchase authorization of US$121.6 million, together with a higher quarterly dividend of US$0.25 per share, give Origin Bancorp scope to keep returning capital in ways that can support per share earnings.
See why 0 investors see Origin Bancorp as 12% undervalued.
Result: Fair Value of $59.20 (UNDERVALUED)
Still, the Origin Bancorp story can be knocked off course if digital competitors win away higher value clients or if its tightly clustered Southern footprint encounters a regional downturn.
Find out about the key risks to this Origin Bancorp narrative.
Another View: Origin Bancorp Through Earnings Ratios
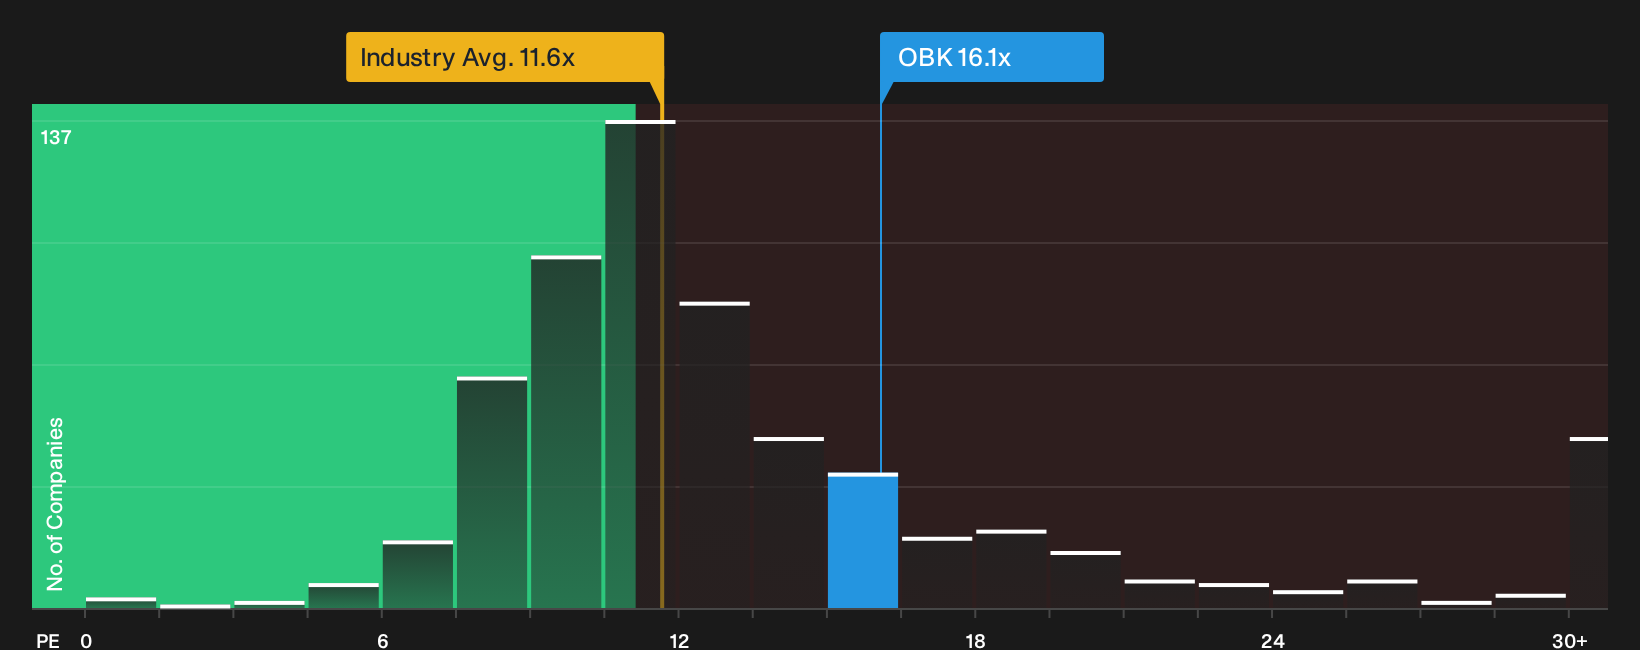
There is a different read on Origin Bancorp when shifting from fair value estimates to the simple P/E yardstick. The stock trades on 16.1x earnings compared with a fair ratio of 12.4x, the US Banks industry at 11.4x and direct peers at 17.2x.
That mix paints a complicated picture. Versus the sector, Origin Bancorp looks expensive, yet against closer comparables it appears more middle of the pack. The gap to the fair ratio hints at valuation risk if sentiment cools or earnings forecasts slip even modestly.
Investors comparing these signals will be weighing whether recent earnings strength and capital returns justify paying above the broader industry, or whether the market could drift toward that lower fair ratio over time.
For a closer look at how this earnings multiple stacks up against both peers and the broader sector, and what it could mean for future pricing power, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Origin Bancorp is mixed, so this is a moment to move quickly, stress test the numbers yourself and decide where you stand. To see which potential upsides are drawing attention and how they stack up against the risks, review the 3 key rewards.
Looking for more Origin Bancorp style investment ideas?
Origin Bancorp might be front of mind today, but you will miss out on other opportunities if you stop your research here. Put a few more carefully filtered ideas on your radar using the Simply Wall Street Screener and keep building a watchlist that actually reflects how you want to invest.
- Target potential value opportunities by scanning a 29 high quality undervalued stocks that pairs quality fundamentals with pricing that may still lag behind underlying strength.
- Build a cash flow focused watchlist by filtering for income ideas drawn from a 6 dividend fortresses that clears a 5% yield hurdle.
- Dial up resilience in your portfolio by concentrating on companies from a 30 resilient stocks with low risk scores that score well on financial strength and volatility checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com