


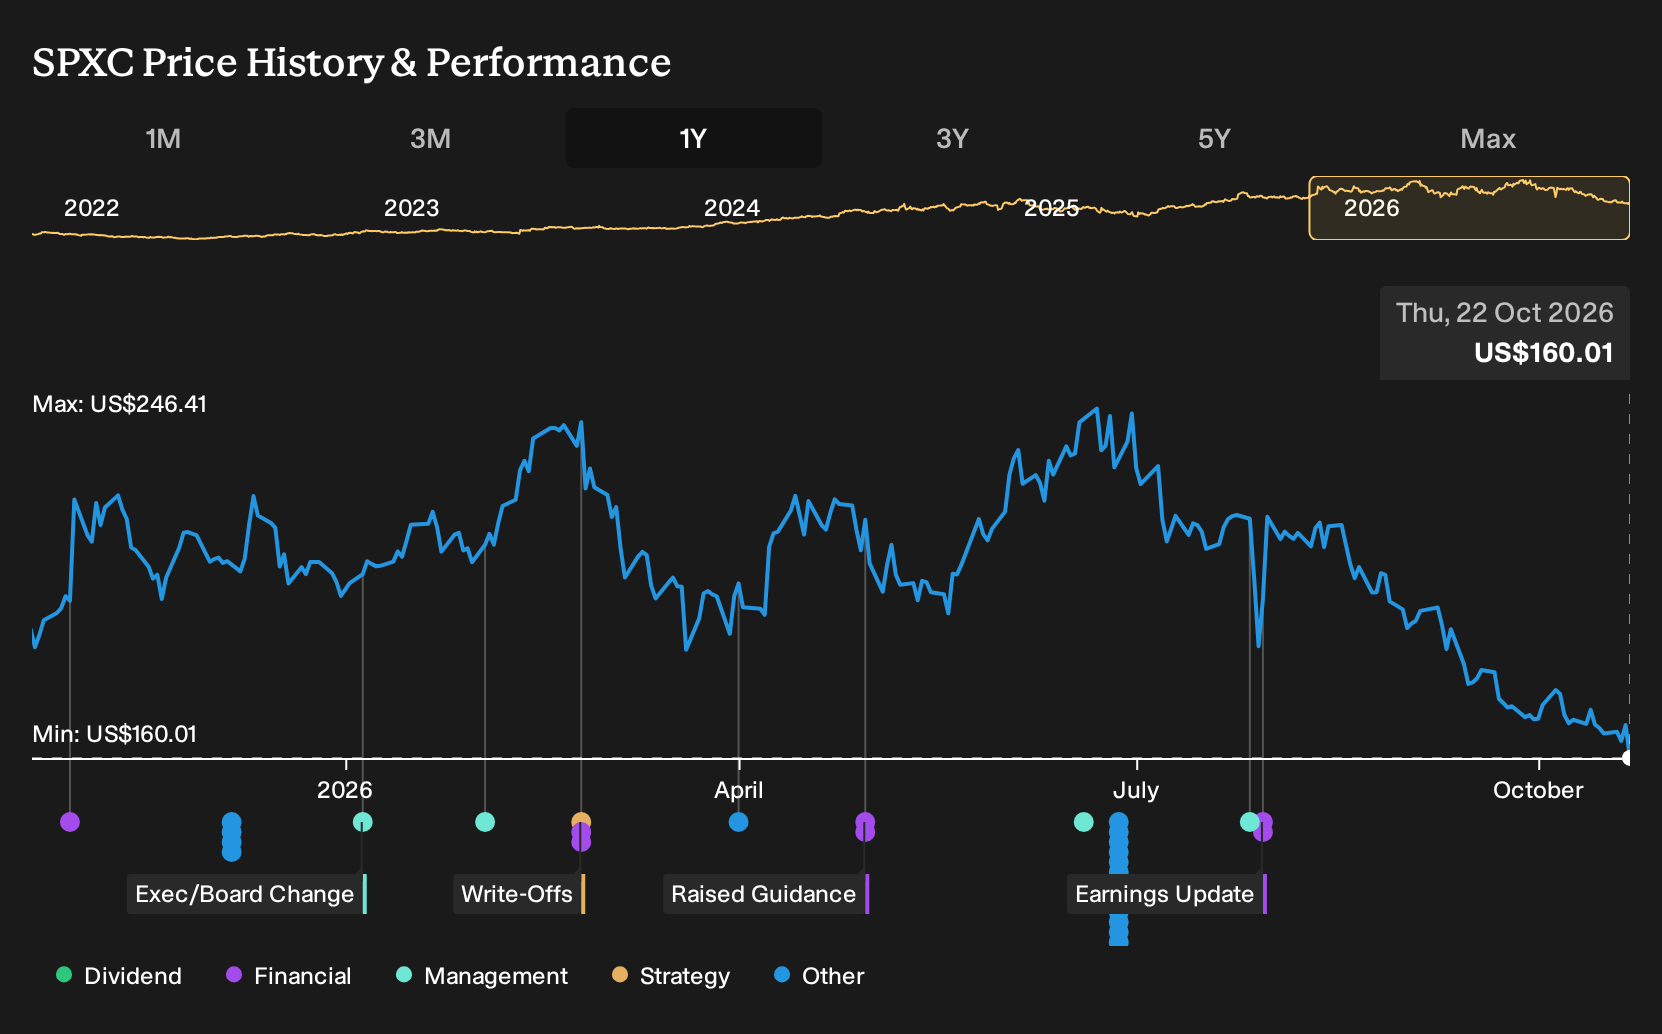
- SPX Technologies is preparing to report quarterly results for the period ended September 2026, with Wall Street expecting higher earnings supported by stronger revenue.
- Analysts point to the company’s track record of beating earnings estimates as a key backdrop for these expectations, which keeps attention firmly on how effectively SPX Technologies is running its operations.
- We will now look at how SPX Technologies' investment narrative could be influenced by expectations of another earnings beat this quarter.
Scan potential earnings beat candidates alongside SPX Technologies by reviewing the hand-picked 20 high quality undiscovered gems that analysts are watching closely this season.
SPX Technologies Investment Narrative Recap
To own SPX Technologies, you need to believe the HVAC and Detection & Measurement platforms can keep turning capacity additions and past acquisitions into solid, repeatable earnings. The near term swing factor is execution on data center cooling and broader HVAC backlog conversion. The upcoming earnings release may clarify how smoothly that volume is flowing through plants and into margins.
The biggest operational risk right now sits in the more project driven Detection & Measurement side and in cost pressure from Section 232 derivative tariffs. If revenue timing remains lumpy or tariffs are not fully offset, quarterly profitability could stay choppy. The latest earnings expectations do not materially change those core issues.
The most relevant update is the expectation for a year over year earnings increase on higher revenue for the September 2026 quarter. That is closely tied to the existing catalyst around expanded data center cooling capacity and higher data center HVAC revenue guidance of about US$430 million in 2026, which already frames how investors view SPX Technologies’ growth runway.
If the company reports figures that are consistent with those expectations, it would give investors more evidence on whether recent capacity expansions in places like Olathe and Springfield are translating into operating leverage. Any commentary on HVAC backlog quality, data center demand and Detection & Measurement order wins would directly influence how you weigh those catalysts against project timing risk and tariff related margin pressure.
What The Current Forecasts Assume For SPX Technologies
SPX Technologies' narrative projects US$3.7b revenue and US$509.6 million earnings by 2029. This is built on analysts assuming 14.6% yearly revenue growth and an earnings increase of about US$224.6 million from US$285.0 million today.
Discover why SPX Technologies' fair value indicates a 58% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$203 and US$252.79 per share, so private investors are already assigning a wide span to SPX Technologies. Set that against project timing risk in Detection & Measurement and tariff pressure, and you can see why opinions differ. Explore those alternative views directly.
Explore 2 other SPX Technologies fair value estimates, including one that suggests it could be worth just $203.00!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your SPX Technologies research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for SPX Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SPX Technologies' overall financial health at a glance.
Looking for more investment ideas beyond SPX Technologies?
If you want to pressure test your SPX Technologies thesis against other opportunities, cast the net wider with a few focused screens on Simply Wall St that match different investing styles.
- For investors who care most about balance sheet strength and underlying business quality, start with this curated list of solid balance sheet and fundamentals (26 results) and see which companies clear those hurdles.
- If downside risk control sits at the top of your checklist, compare SPX Technologies with a 30 resilient stocks with low risk scores that score well on resilience and stability.
- When you want ideas that have not yet drawn broad market attention but still show strong fundamentals, broaden your watchlist with a 20 high quality undiscovered gems that might deserve a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com