


Oil pushing past $114 per barrel has put cash generation back in the spotlight. When energy and input costs climb, businesses with solid cash inflows and modest expectations in their share prices can look increasingly interesting. Some of these companies trade as if their future cash streams barely matter. This article walks through three such stocks the screener flags as potentially undervalued on cash flows right now.
The three stocks in this article are just a small sample. The full screen surfaced 469 more companies with cash flow stories that also look potentially interesting on Simply Wall St’s discounted cash flow model.
Head straight into the Undervalued Stocks Based On Cash Flows screener to identify, analyze, and focus on the cash flow opportunities that best match your own investing criteria.
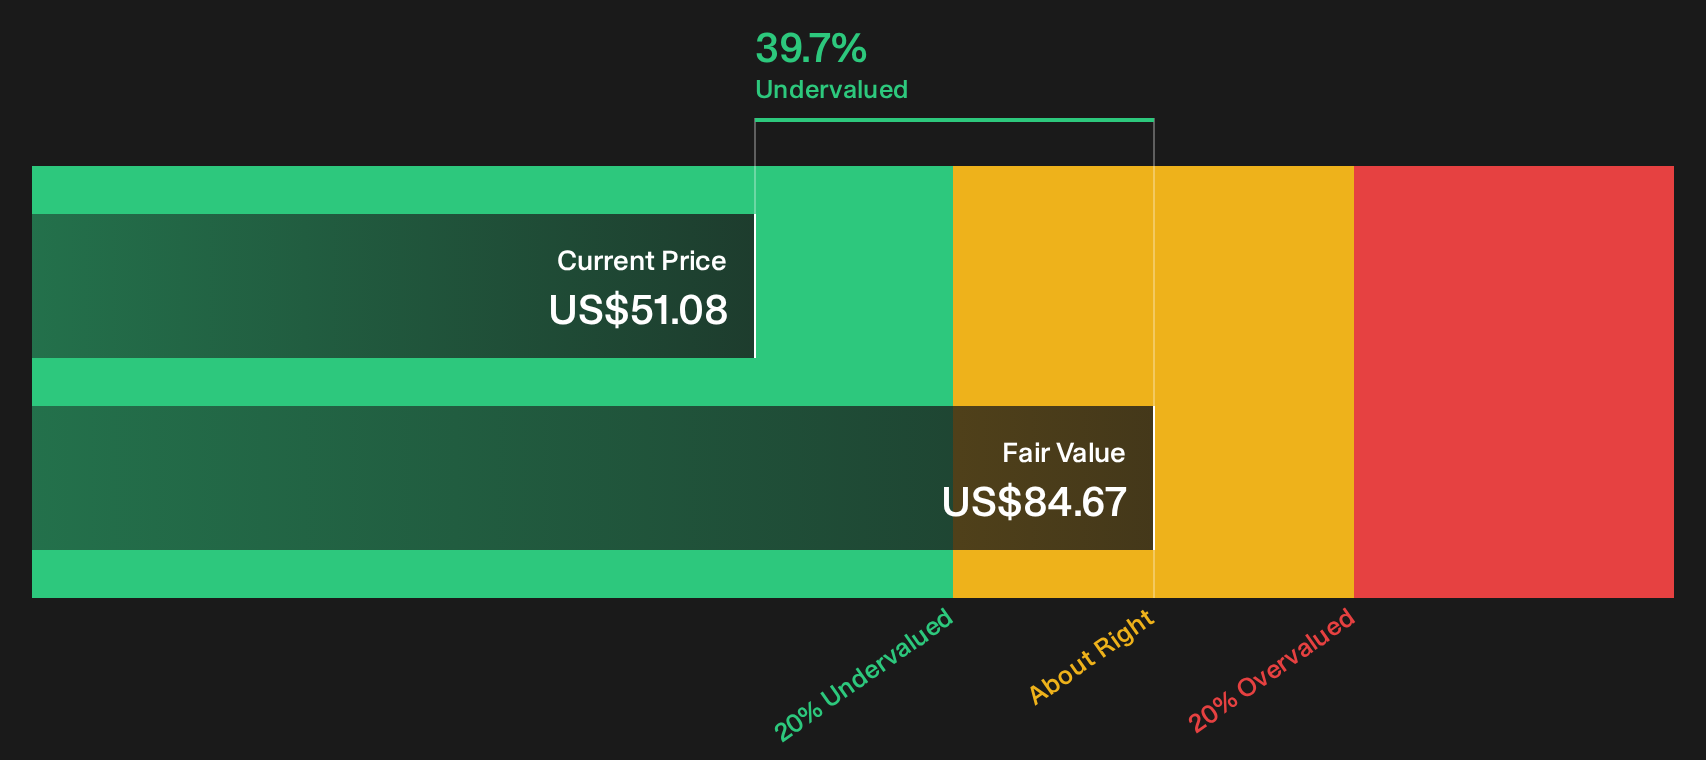
Bank of America (BAC)
Bank of America sits near the center of this cash flow screen because its lending, trading, and treasury operations generate modelable streams of interest and fee income that a DCF framework can weigh against today’s market expectations.
Bank of America runs a broad financial platform across consumer, wealth, corporate banking, and markets. Consumer Banking generates about US$40.8b of revenue, Global Markets US$26.3b, Global Wealth & Investment Management US$27.3b, and Global Banking US$24.1b, with the group valued by the market at roughly US$351.5b in equity.
"Bank of America's continued investment in digital engagement and AI-driven efficiencies remains a live driver, with plans to double the AI budget within a US$14b technology spend and more than 140 AI applications such as Erica and CashPro already reducing support needs, which could support revenue growth and net margins as the next wave of use cases rolls out."
What matters next for Bank of America is how one less visible pressure shapes the durability of those cash flows that the DCF model values.
Those quieter forces sit at the center of the full narrative for Bank of America, where the full thesis unpacks how cash flow durability, funding costs, and deposit behavior could be decoupling expectations.
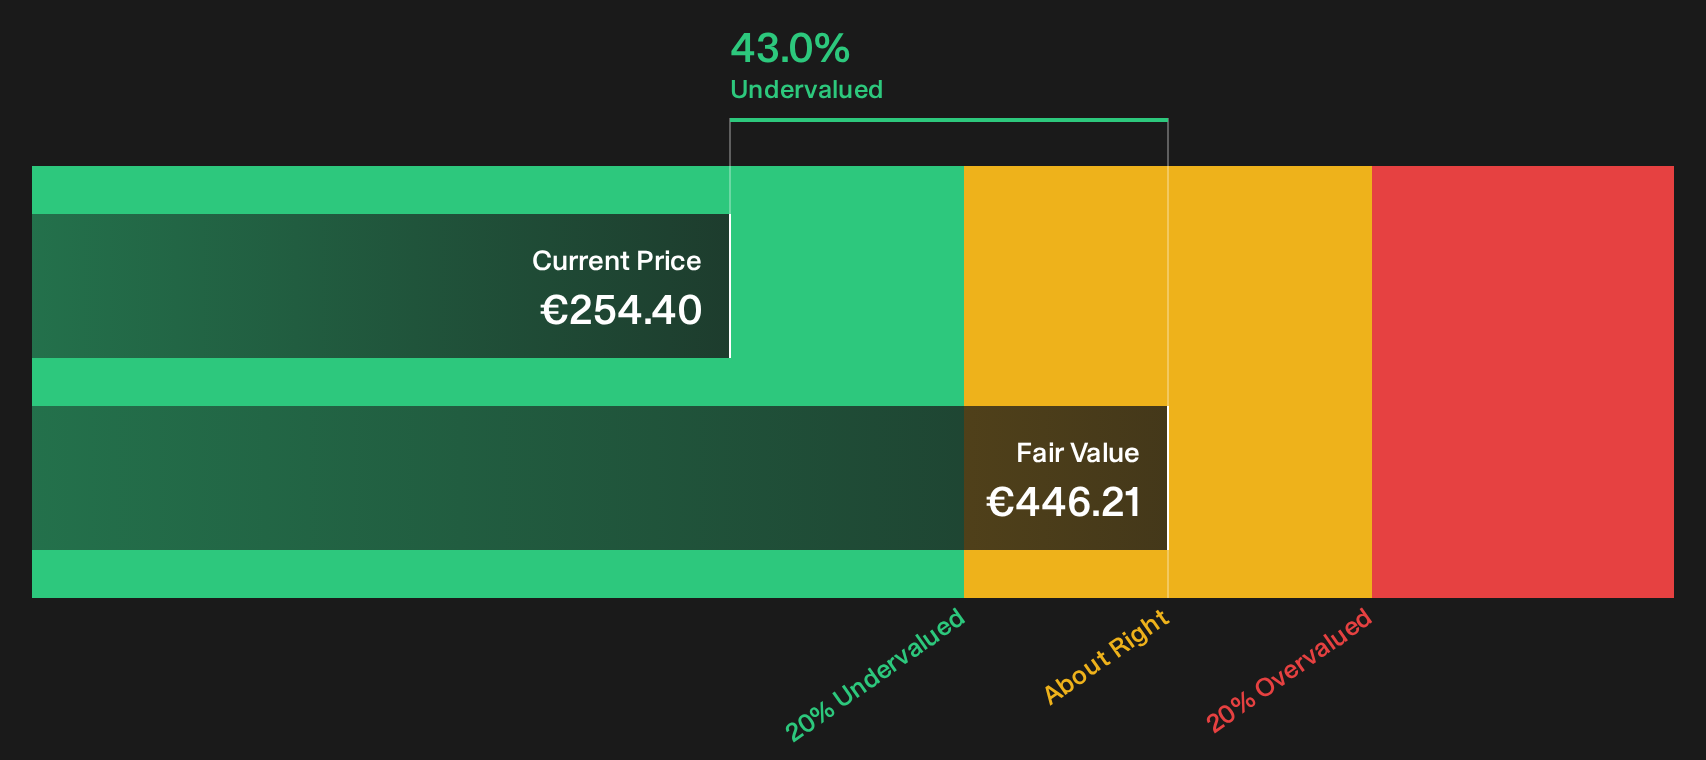
Ackermans & Van Haaren (ENXTBR:ACKB)
Ackermans & Van Haaren is a Belgian holding group that links cash flow heavy infrastructure projects with financial services. It is anchored by Marine Engineering & Contracting, which brings in about €5.34b of revenue, alongside €422 million from Private Banking and roughly €100 million each from Real Estate and AvH & Growth Capital, with the group valued at about €8.31b.
Ackermans & Van Haaren fits this cash flow screen through its mix of capital intensive marine projects and steady financial activities. This gives investors exposure to renewable energy infrastructure without relying solely on one cycle. That balance is also where the current debate around its valuation really starts.
"The renewed and extended partnership with the Delen family indicates strengthened client relationships and potential for future revenue increases and net margin improvements in banking operations."
The bigger swing factor is how earnings from its marine and renewables aligned projects evolve if a single key assumption on future returns shifts.
If that swing factor has your attention, the full narrative for Ackermans & Van Haaren shows how those cash flows could accelerate or stall as project returns and banking profitability interact.
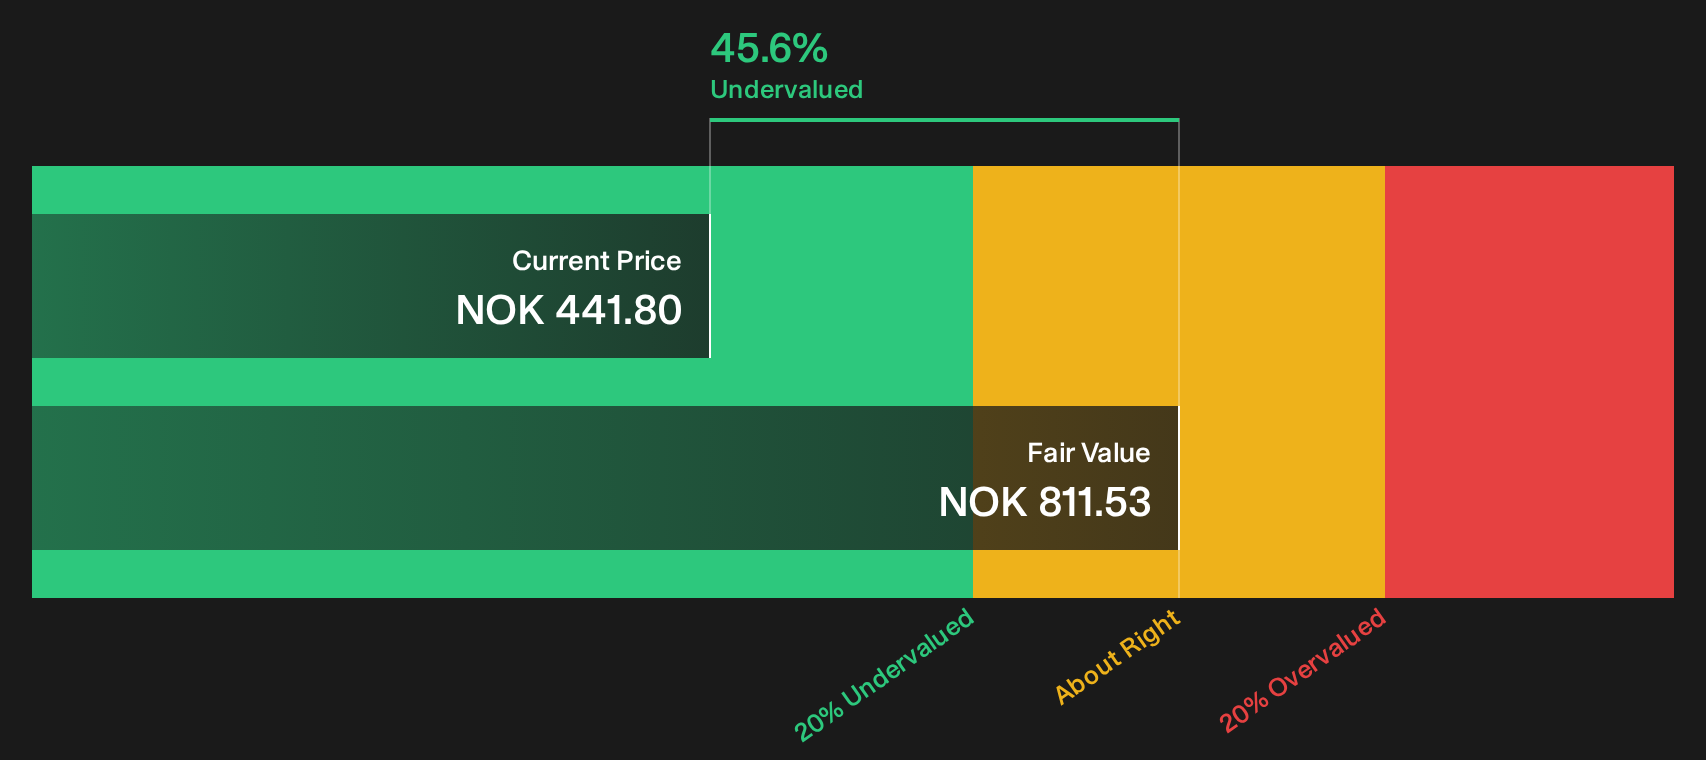
Protector Forsikring (OB:PROT)
Protector Forsikring is a non life insurer focused on commercial clients, public sector contracts and affinity groups, where recurring premiums and reserve management sit neatly within the cash flow lens of this screener. The group is valued at about NOK36.4b.
For Protector Forsikring, the appeal of this cash flow screen comes from a mix of recurring underwriting income and the way management treats capital as a scarce resource that has to earn its keep.
"Protector Forsikring continues to build out its data and AI tools across underwriting, claims and support functions, with management accepting higher current costs in order to raise decision accuracy and make the cost base more scalable, which is aimed at supporting net margins and earnings."
What happens next for Protector Forsikring depends on how one less visible pressure shapes the sustainability of those margins that cash flow investors care about.
That hidden pressure is exactly where the full narrative for Protector Forsikring shows whether Protector Forsikring's accelerating AI spend is masking risk or setting up a stronger cash engine.
Seeking Fresh Alternatives Before Others Do
Fresh ideas keep moving while attention lags. Some could be building breakout momentum or quietly dropping into better value under the radar for now, so consider researching them early.
- Spot income workhorses that aim to keep paying while prices swing around by scanning a curated set of 6 dividend fortresses before yields attract more widespread attention.
- Focus on real economy trends instead of headlines by tracking infrastructure and materials players inside the 42 power grid technology and infrastructure stocks while they are still outside broad market focus.
- Position next to potential earnings flywheels by reviewing cash generative AI enablers in the 55 AI infrastructure stocks while expectations remain grounded and entry points still matter.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com