


Australian dividend stocks are back in focus as slower local growth forecasts and higher unemployment push many investors toward cash flow they can see and count. With the treasurer flagging tougher economic conditions, the appeal of established businesses paying yields above 3% that look covered, growing and relatively steady is hard to ignore. This article walks through three income ideas from that universe and what sets each one apart.
The three stocks highlighted here offer a compelling starting point if you want exposure to higher yielding businesses where the dividend looks covered, growing and relatively stable. However, if you want the pick of this theme, these 6 dividend aristocrats stocks are the best of the best.
Medibank Private (ASX:MPL)
Medibank Private is one of Australia’s largest private health insurers, with the Health Insurance arm collecting recurring premiums that align directly with the Dividend Powerhouses theme, while a smaller Medibank Health division adds extra income from health services and insurance distribution.
Medibank generates about A$8.6b of revenue from Health Insurance and A$635 million from Medibank Health, with market value around A$13.6b. That mix of scale and predictability is what puts the stock on many income investors’ shortlists.
"The expansion and scaling of Medibank Private’s primary care clinics, virtual health and in home care services, including more than A$500m invested over a decade and increasing volumes of GP consults and acute home visits that reduce hospital bed days, is expected to support revenue growth in Medibank Health and help contain claims costs in the insurance book, which can be positive for net margins."
What really matters for Medibank shareholders now is how one quiet shift in its earnings mix shapes those future margins and the reliability of that dividend.
That shift in mix is exactly what the full narrative for Medibank Private unpacks, revealing how Medibank Private’s healthcare ecosystem could support earnings resilience while also masking some underappreciated risks.

ARB (ASX:ARB)
ARB Corporation is best known for its cash-generating 4x4 aftermarket accessories business, where bull bars, suspension kits, air lockers, canopies and camping gear help underpin its Dividend Powerhouses profile. The group earned about A$706 million from motor vehicle accessories and light metal engineering works and has a market value around A$1.4b.
For income investors, ARB matters because its core off-road accessories and camping hardware deliver repeat purchases from both weekend drivers and working fleets, creating the kind of steady cash flows that can help support a 3%+ dividend through different parts of the cycle.
"In the Australian market, ARB is the clear leader. Morningstar estimates ARB holds more than a 50% share in fabricated products (bull bars, rollover protection and the like) and around 35% of the suspension market."
What happens to that dividend story if one quiet pressure on cash flow and payout coverage moves the wrong way is what investors should watch.
If that pressure on cash flow is what worries you, read the full narrative for ARB to see how ARB’s payout story could be quietly decoupling from headline demand.

Commonwealth Bank of Australia (ASX:CBA)
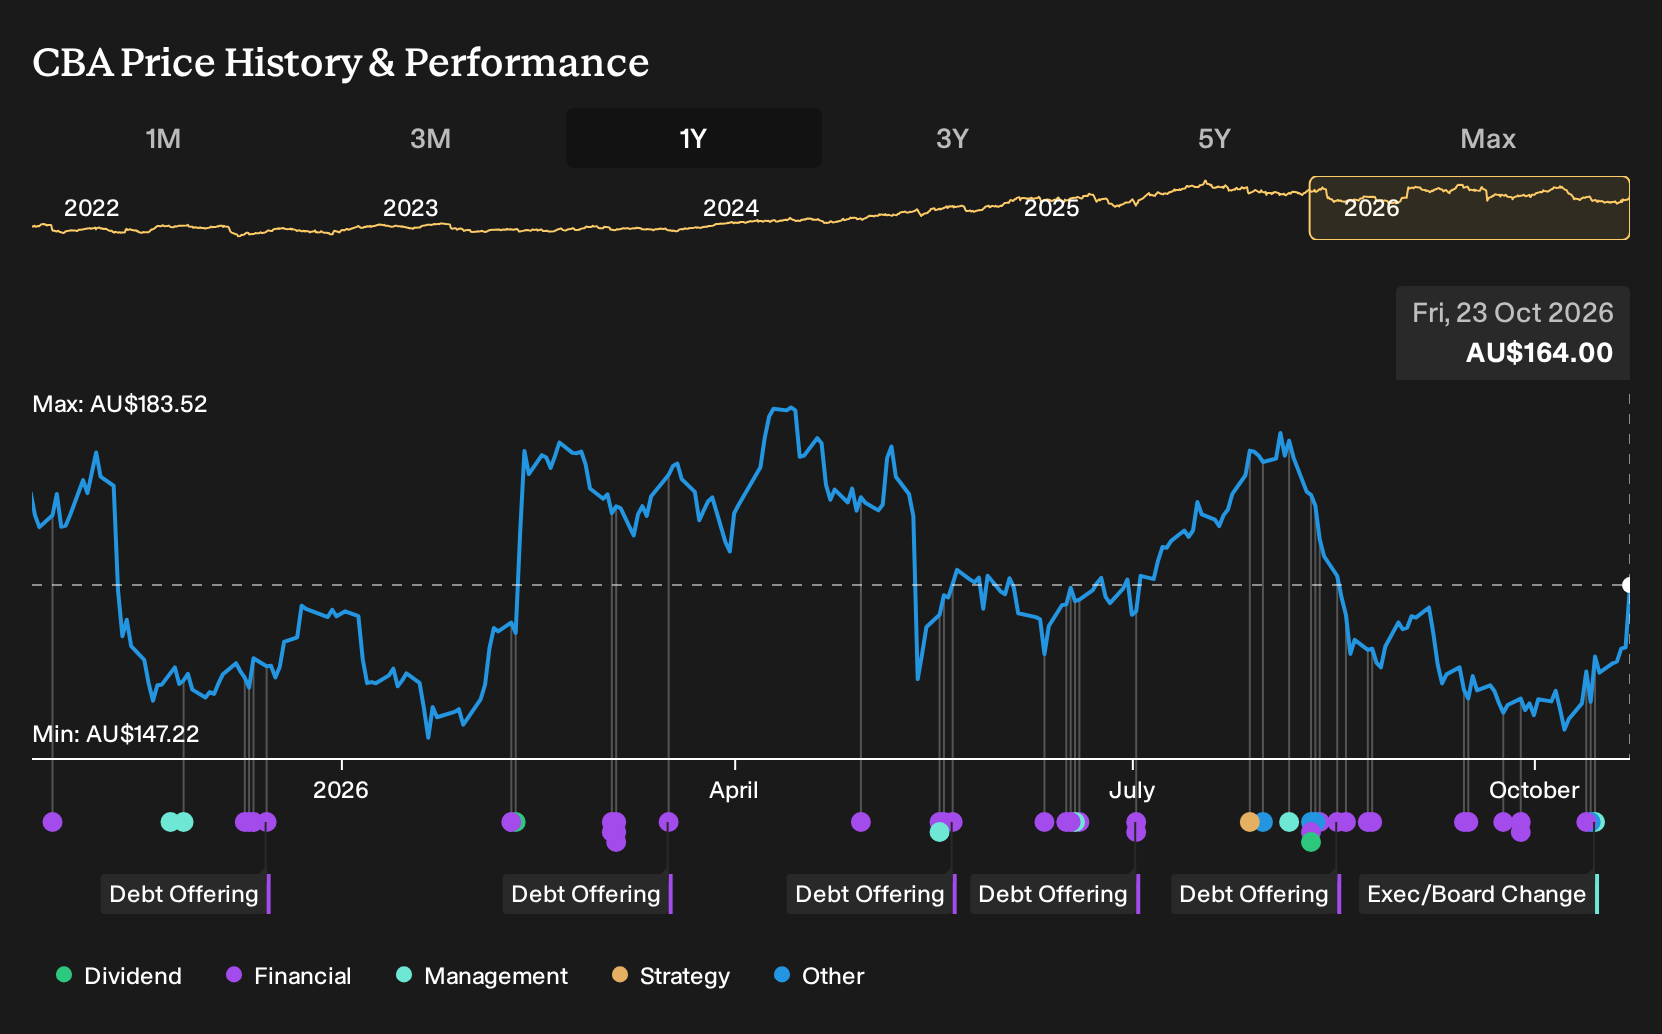
Commonwealth Bank of Australia is a full service lender and deposit institution, with its Retail Banking Services arm, including home loans and everyday accounts, generating A$13.4b of revenue out of roughly A$30.4b across all segments and underpinning dividends for a A$274.2b banking giant.
For income focused investors, Commonwealth Bank of Australia matters because its mortgage and deposit engine throws off steady cash that can support a covered yield, even as its broader mix of business and institutional units deals with rising digital competition and shifting customer behaviour.
"Growing competitive intensity in both digital payments and deposit products, as digital disruption accelerates and fintechs increase their activity, threatens to erode Commonwealth Bank of Australia's (CBA) traditional profit pools, putting downward pressure on net interest margins and fee-based revenues."
The real swing factor for that payout is what happens if one quiet pressure on dividend stability collides with already stretched expectations on future earnings.
If that collision is what you are weighing up, the full narrative for Commonwealth Bank of Australia shows how Commonwealth Bank of Australia’s income story could be quietly reshaped by accelerating digital competition.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. By the time momentum is flying, the best entry points can be gone. Scan these under the radar themes while it matters and consider them before broader interest builds.
- Look for smaller, punchy opportunities where the market has not fully caught on yet by running the 21 elite penny stocks with strong financials before prices move away.
- Focus on resilient cash generators that aim to balance income with capital protection through the curated list of solid balance sheet and fundamentals (12 results) while the window still appears attractive.
- Identify potential breakout beneficiaries of AI demand by reviewing the hand picked 55 AI infrastructure stocks while these stories are still relatively under the radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com