


- Xero and Bookkeeper360 recently launched a custom integration that embeds Xero and Melio powered AP and AR tools directly into accounting firms’ own platforms, with firm branding, SSO and enterprise grade support.
- The integration offers per client pricing without per seat fees, which could matter for practices watching software spend while scaling staff access and transaction volume.
- We will now look at how this embedded US Bookkeeper360 integration could influence Xero's broader accounting and payments investment narrative.
Scan how Xero’s US push around embedded payments compares with other software driven plays by reviewing our hand picked 15 high quality undiscovered gems building behind the scenes in similar workflows.
Xero Investment Narrative Recap
Xero asks you to believe that small business accounting, payments and AI workflows keep consolidating into a few core platforms. The short term swing factor is whether heavy US spending and the Melio led payments build out convert into efficient customer wins. The Bookkeeper360 deal nudges that thesis forward, but by itself it does not transform the immediate earnings picture.
The biggest near term risk still sits in execution and profitability. Net profit margins are 6.1%, lower than 10.8% last year, while US brand investment is set to rise by up to NZ$55m in FY27. If these integrations do not translate into better customer economics, that extra spend could drag on margins for longer.
The Google Gemini integration is the most relevant recent announcement to line up with the Bookkeeper360 news. Both push Xero deeper into the tools accountants and small businesses already use, whether that is a practice portal or an AI assistant. The Gemini app also leans on JAX, the agentic platform that already powers automated reconciliation.
For catalysts, this matters because it ties product usage, AI and payments more tightly together. Gemini access to real time Xero data for tasks like P&L queries, receivables and payables monitoring could support advisor stickiness and practical adoption of new features. The key execution watchpoint is whether this embedded approach offsets pricing sensitivity and justifies US marketing spend without further pressure on customer churn or acquisition efficiency.
What The Xero Earnings Path Implies
Xero's current profit pool and the analyst roadmap around it put the Bookkeeper360 and Melio integrations in clearer context for investors watching execution risk. The accounting and payments stack that shows up in a single US bookkeeping workflow is the same stack analysts are using to justify longer term earnings and revenue targets. That means small shifts in customer adoption today can compound meaningfully into the consensus models tied to 2029 assumptions.
Across the analyst set, the working model assumes revenue grows by 23.7% per year over the next three years, with profit margins moving from 6.1% today to 11.7% on a three year view. Forecast consensus earnings of NZ$612.0m by 2029 compare with earnings today of NZ$167.4m, which implies an earnings increase of about NZ$444.6m over that period if those projections hold. The same framework also leans on forecast 2029 revenue of NZ$5.2b as the top line anchor for those profitability and margin expectations.
That growth profile underpins the P/E assumptions currently embedded in analyst targets. The stock would need to trade on a P/E of 66.2 times those 2029 earnings compared with 80.1 times today, a level that sits well above the 24.6 times P/E cited for the wider NZ software peer group. Analysts also layer in share count expansion of 6.91% per year over the next three years, which matters if you are thinking in terms of per share outcomes rather than headline profit levels. Any gap between the hoped for margin lift and actual delivery would affect how that multiple and share issuance translate into returns.
Xero's narrative projects NZ$5.2b revenue and NZ$612.0m earnings by 2029. This requires 23.7% yearly revenue growth and an earnings increase of about NZ$444.6m from NZ$167.4m today.
Uncover why Xero's fair value indicates a 91% potential upside to its current price before the gap to Xero's valuation story narrows.
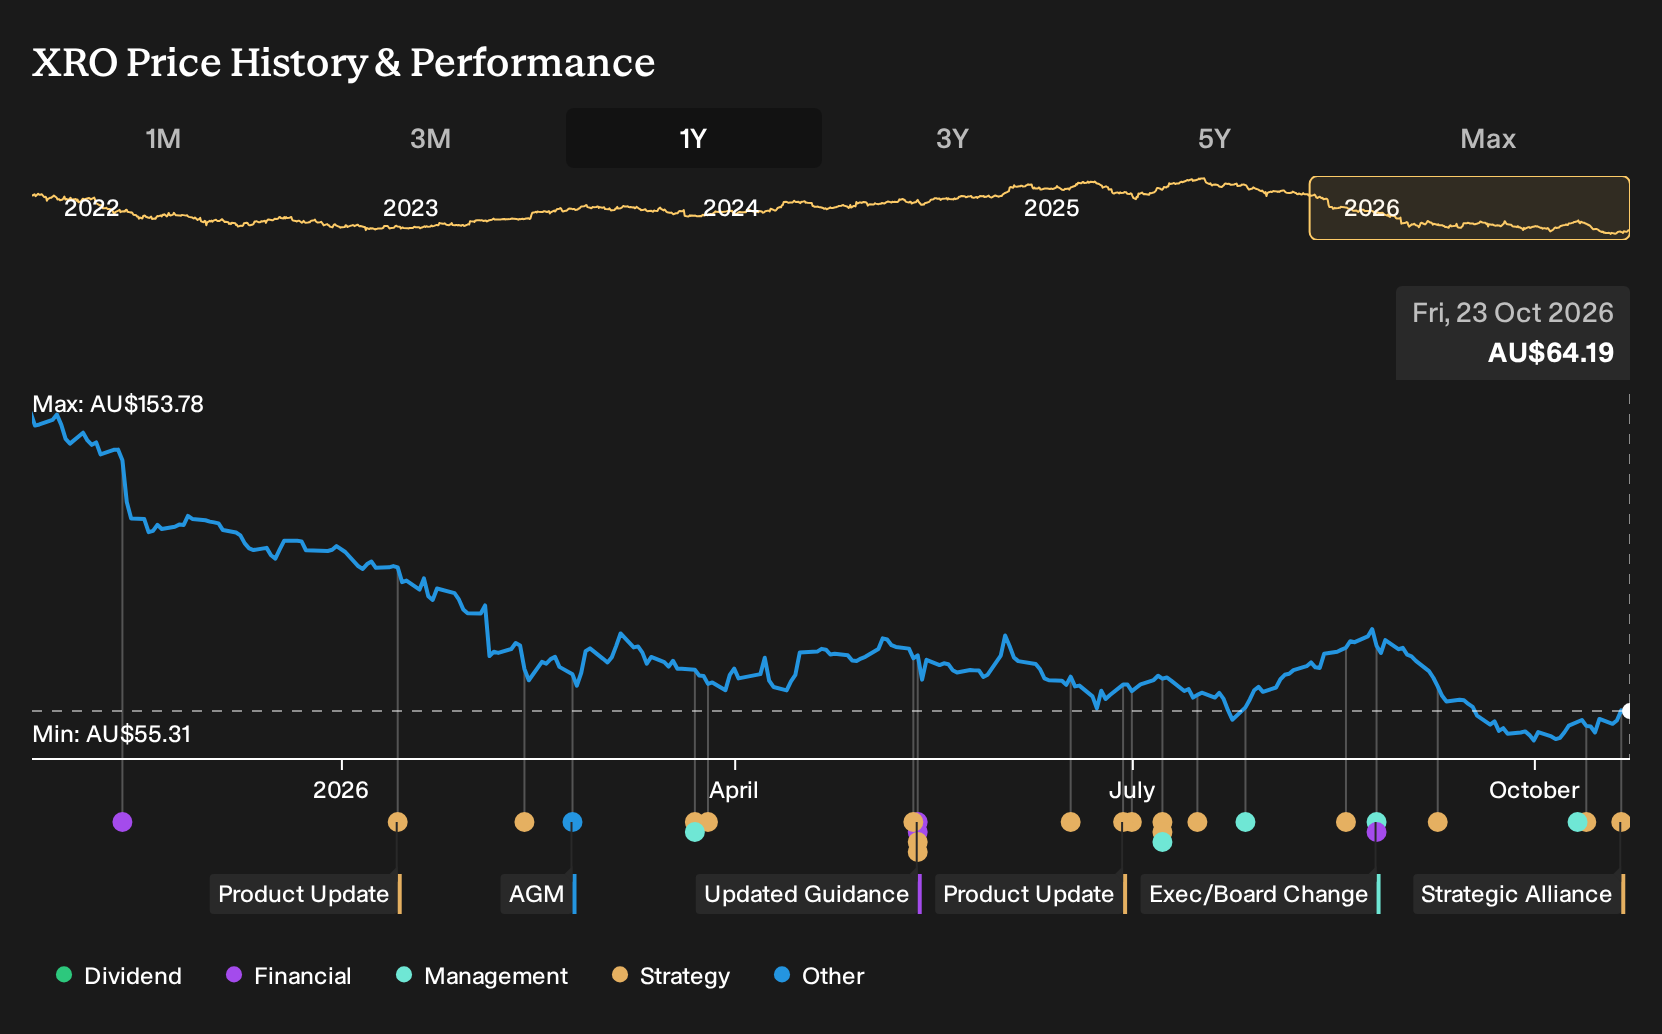
Exploring Other Perspectives
One contrasting angle is that the most cautious analysts see Xero’s heavy US and AI investment as a cost risk rather than a growth catalyst. Before this Bookkeeper360 integration, they were working off 19.9% annual revenue growth and NZ$495.9m earnings by 2029. That is far below consensus, which shows how widely views can differ and why it can help to weigh several narratives that may shift as this news is incorporated into updated models.
Explore 7 other Xero fair value estimates, including one that suggests it could be worth just A$66.83.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Xero research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Xero. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Xero's overall financial health at a glance.
Looking For More Xero Investment Ideas Beyond This Story?
If you want to pressure test Xero against other opportunities, it helps to scan a wider field of companies with clear filters rather than scrolling through tickers at random.
- If capital preservation sits high on your list, start with a group of companies that score well on stability using our 6 resilient stocks with low risk scores.
- For readers hunting for strong balance sheets that can better absorb shocks and fund growth internally, the Simply Wall St screener highlighting a list of solid balance sheet and fundamentals (12 results) is a helpful place to begin.
- Income focused investors who care about steady cash returns can line up alternatives to Xero by scanning our curated set of 6 dividend fortresses that meet a higher yield bar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com