


Rocket Companies (RKT) is stepping into a closely watched third quarter update, with its October 29 earnings release and conference call arriving just as U.S. housing demand shows fresh signs of strain.
Recent trading paints a mixed picture for Rocket Companies. The 1 day share price return of 5.67% and 7 day gain of 6.05% contrast with a 30 day share price decline of 7.85% and a year to date drop of 40.95%. This leaves momentum looking fragile despite a 3 year total shareholder return of 69.95%, which signals that investors have previously been willing to pay more when the earnings story appears clearer.
Compare Rocket Companies' setup against a hand picked 29 high quality undervalued stocks that also face housing and rate pressure but currently trade on stronger sentiment and fundamentals.
Rocket Companies has bounced in the last week yet sits well below where it started the year, which puts you at a fork in the road. Do you lean into this reset now, or wait for a deeper markdown once the valuation math is on the table?
Most Popular Narrative: 27% Undervalued
Against Rocket Companies' last close at $11.74, the most followed narrative pegs fair value around $16.00. This frames current pricing as a clear discount while still building in a margin of safety through a 9.14% discount rate.
The move to a revenue mix where more than 70% comes from servicing, purchase, home equity, personal loans, Redfin and Rocket Money subscriptions shifts Rocket Companies further away from pure rate driven refinance exposure and can support a steadier base for revenue and earnings.
The build out of AI tools that cut prospecting time, raise conversion and support roughly US$300b of fixed origination capacity with fewer production staff gives Rocket Companies room to add volume without matching growth in expenses, which can support net margins.
See why 35 investors see Rocket Companies as 27% undervalued.
Result: Fair Value of $15.99 (UNDERVALUED)
Still, the narrative around Rocket Companies unravels quickly if mortgage demand stays weak or if the Redfin and Mr. Cooper integrations fail to lift transaction volumes.
Find out about the key risks to this Rocket Companies narrative.
Another View: Rocket Companies On Earnings Multiples
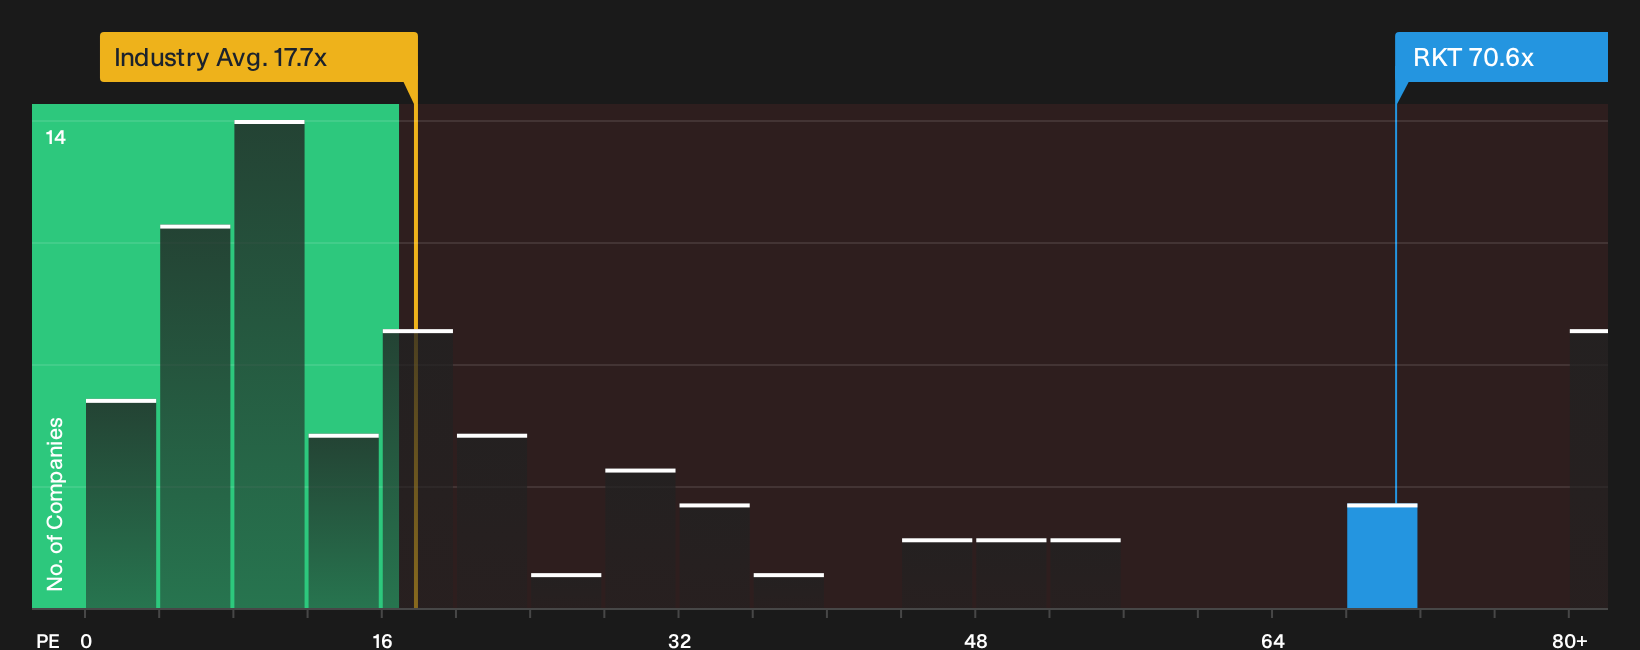
The story looks different when you switch from fair value estimates to plain earnings ratios. Rocket Companies trades on a P/E of 70.6x, while the US Diversified Financial industry averages 17.6x and peers sit near 33.1x. The fair ratio is 26.5x, which is the level the market could move toward if sentiment cools.
That gap leaves you weighing potential upside from the narrative of improvement against the risk that the share price has too much optimism priced in already, especially if earnings or housing data disappoint again.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Rocket Companies is split, and that is exactly when doing your own homework matters most. Move quickly, weigh the upside against the risk, and ground your view in the data with the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Rocket Companies?
If Rocket Companies has you thinking more broadly about opportunities, use that momentum to widen your watchlist with a few focused screens built for different goals.
- Target income first and hunt for dependable cash payouts with the 6 dividend fortresses.
- Stack the odds toward resilience and concentrate on durable balance sheets using the list of solid balance sheet and fundamentals (26 results).
- Get ahead of the crowd and scan for underfollowed potential with the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com