


- Insight Enterprises announced that it has been named an OpenAI Advanced Partner, expanding a long term collaboration to help enterprises build, deploy and scale AI solutions using OpenAI frontier models and Insight expertise in cloud, data, cybersecurity and digital transformation.
- The business is investing in an OpenAI Centre of Excellence and specialised AI delivery teams, signalling a deeper shift toward higher value consulting, managed services and agentic AI solutions built around offerings like Radius and Rapid AI.
- We will now see how Insight Enterprises' investment narrative could be influenced by its new OpenAI Centre of Excellence commitment.
Scan beyond Insight Enterprises and line up other AI infrastructure players using our curated list of 55 AI infrastructure stocks that may be gearing up for their next big catalysts.
Insight Enterprises Investment Narrative Recap
For a shareholder in Insight Enterprises, the core belief is that the business can keep shifting its mix toward higher margin cloud, security and AI services while client IT budgets remain uneven. The OpenAI Advanced Partner status and new Centre of Excellence lean into that story, but do not remove the near term pressure from historically flat sales and modest recent net revenue growth.
Right now, the key short term catalyst is whether the One Insight model and AI driven productivity actually translate into sustainable operating leverage after the recent gross margin move to about 21.7%. The biggest risk is that large clients stay cautious on spending or vendors reprice programs, which could leave earnings growth out of sync with expectations.
The OpenAI Advanced Partner announcement is the clearest operational tie in to existing AI and cloud catalysts. By formalising a Centre of Excellence and specialised teams around offerings like Radius and Rapid AI, Insight Enterprises is building more structure around services that already sit at the higher margin end of its portfolio compared with pure resale activity.
Execution still matters. Insight Enterprises needs these OpenAI linked solutions to support recurring work across strategy, governance, deployment and managed services, not just one off projects. If vendor program changes or client hesitancy reappear, the dependence on operating leverage and AI enabled productivity gains becomes more pronounced, which keeps the risk around margins and valuation alive.
What the Insight Enterprises Forecasts Assume
Insight Enterprises' narrative projects US$9.9b revenue and US$392.5m earnings by 2029. This setup assumes 4.9% yearly revenue growth and an earnings increase of about US$182m from current earnings of US$210.5m.
Analysts are effectively sketching a world where Insight Enterprises grows at a mid single digit clip on the top line while lifting profitability. The forecast calls for revenue to expand by 4.9% per year over the next three years, with net profit margins stepping up from 2.5% today to 4.0% by 2029.
Earnings today are put at US$210.5m and the consensus points to US$392.5m by 2029. That is roughly a US$182m jump in profit, with the lift tied to both higher margins and steady volume rather than to outsized sales gains alone.
The same models assume the share count shrinks by 5.26% per year over the next three years. If Insight Enterprises continues to retire equity at that pace, any earnings progress would be spread over fewer shares, which can amplify earnings per share even if the absolute profit line only grows gradually.
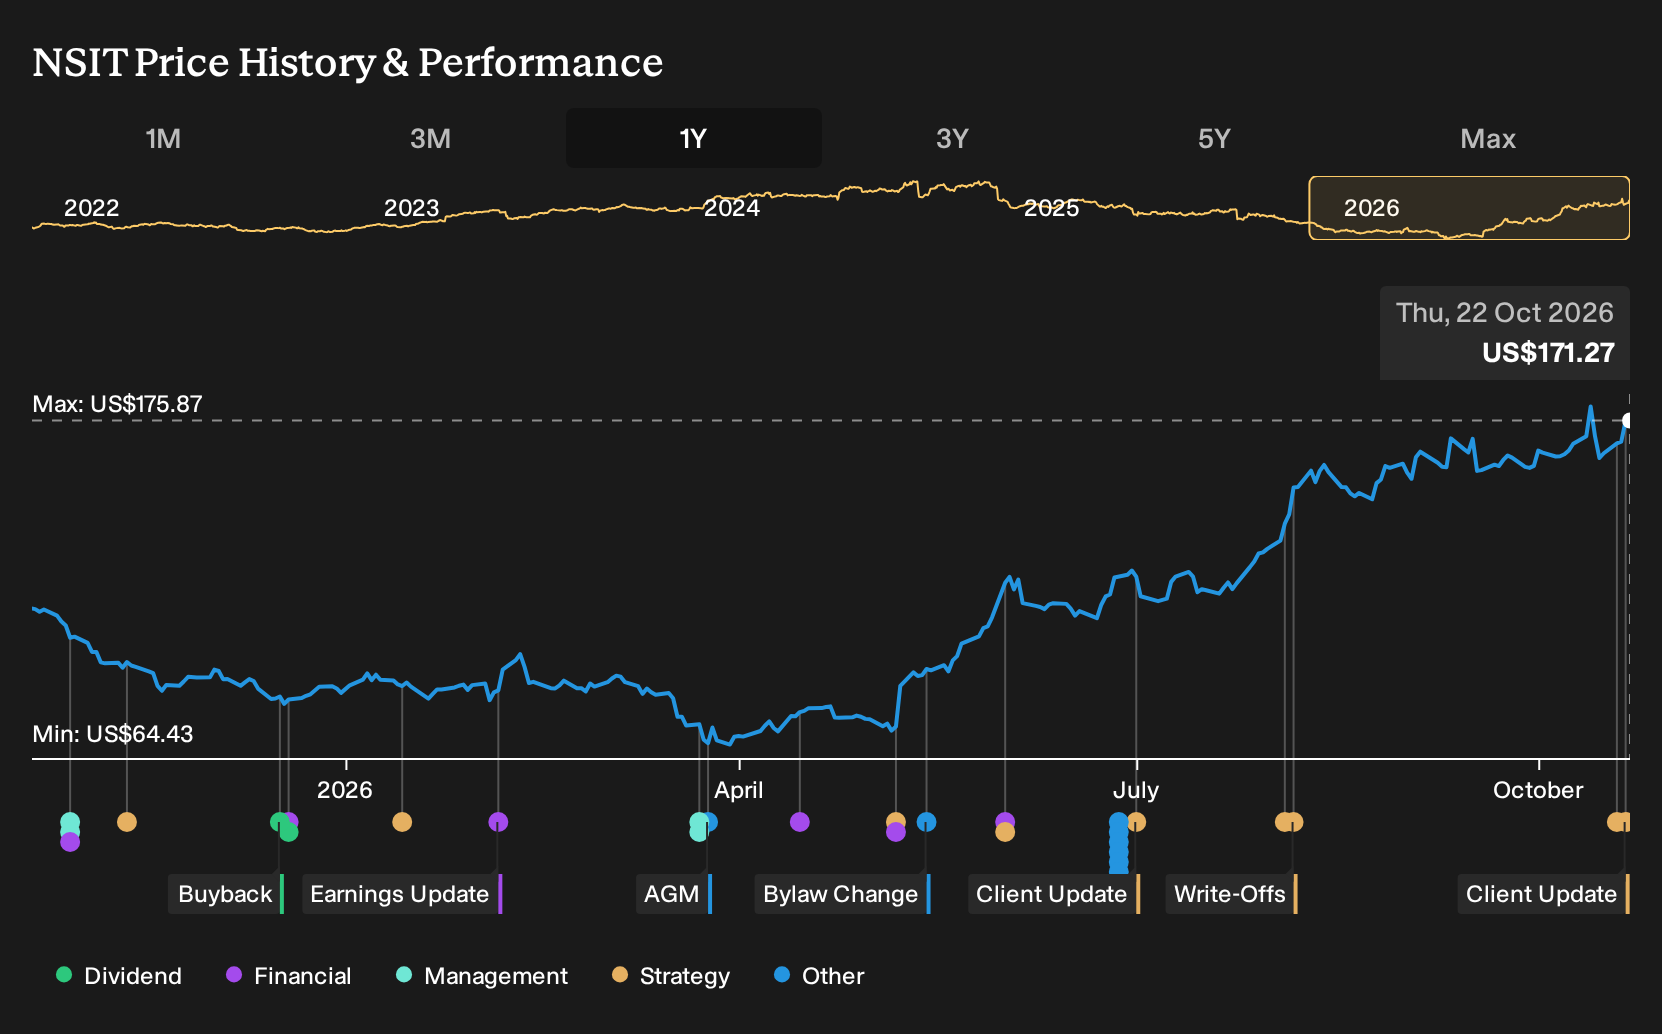
Uncover why Insight Enterprises' fair value indicates a 4% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
You might see the OpenAI Centre of Excellence as a clear services catalyst for Insight Enterprises, yet the lowest analysts were more focused on balance sheet strain. They were working off forecasts of about US$10.1b revenue and US$420.5m earnings by 2029, then applying a much lower implied P/E. Their view could shift after this news, and yours might too.
Explore 4 other Insight Enterprises fair value estimates, including one that suggests up to 36% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Insight Enterprises research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Insight Enterprises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Insight Enterprises' overall financial health at a glance.
Looking For More Investment Ideas Beyond Insight Enterprises?
If the Insight Enterprises story has sharpened your view on AI, services and balance sheet risk, broaden the field and line up a few contrasting opportunities using the Simply Wall St Screener.
- For investors who want potential upside with tighter risk controls, start with a group of companies that score well on stability and resilience through the 30 resilient stocks with low risk scores.
- If you care most about financial strength and staying power, filter for businesses that pair solid balance sheets with sound fundamentals using the list of solid balance sheet and fundamentals (26 results).
- Those hunting for mispriced quality can zero in on opportunities where fundamentals and valuation both look compelling by reviewing the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com