


AI heavy stocks have just been hit by a sharp sell off, which has pushed investors toward companies with clearer cash flow stories and more grounded growth plans. That pullback creates an opening in fast growing Canadian businesses where insiders already own a big stake and have their own wealth on the line. This article breaks down three such stocks from the screener and explains why they may deserve a closer look now.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders hold meaningful stakes alongside you. However, if you want the absolute best, these 11 high growth high conviction stocks are the cream of the crop.
Aritzia (TSX:ATZ)
Overview: Aritzia is a vertically integrated womenswear retailer that designs and sells its own brands through boutiques and digital channels across Canada and the U.S., aligning closely with the fast-growing, insider-backed theme.
Operations: Aritzia generates about CA$4.3b in apparel revenue, with roughly CA$1.6b from Canada and CA$2.8b from the United States.
Market Cap: CA$17.4b
Aritzia matters in this screener because its in-house brands and direct channels give management clear levers to pursue growth as they describe publicly.
"Aritzia's ongoing U.S. boutique rollout, with new locations reportedly paying back in under one year and management indicating room to expand from roughly 76 to 82 to at least 180 to 200 boutiques, points to a continued store-led uplift to net revenue."
The real tension sits in how one evolving cost pressure interacts with that expansion plan and ultimately shapes profitability and investor confidence.
How that cost pressure plays out against the rollout is exactly what sits at the heart of the full narrative for Aritzia, including how management aims to keep returns accelerating.

Total Energy Services (TSX:TOT)
Overview: Total Energy Services is an energy services provider whose drilling rigs and well servicing crews support fast growing upstream oil and gas projects.
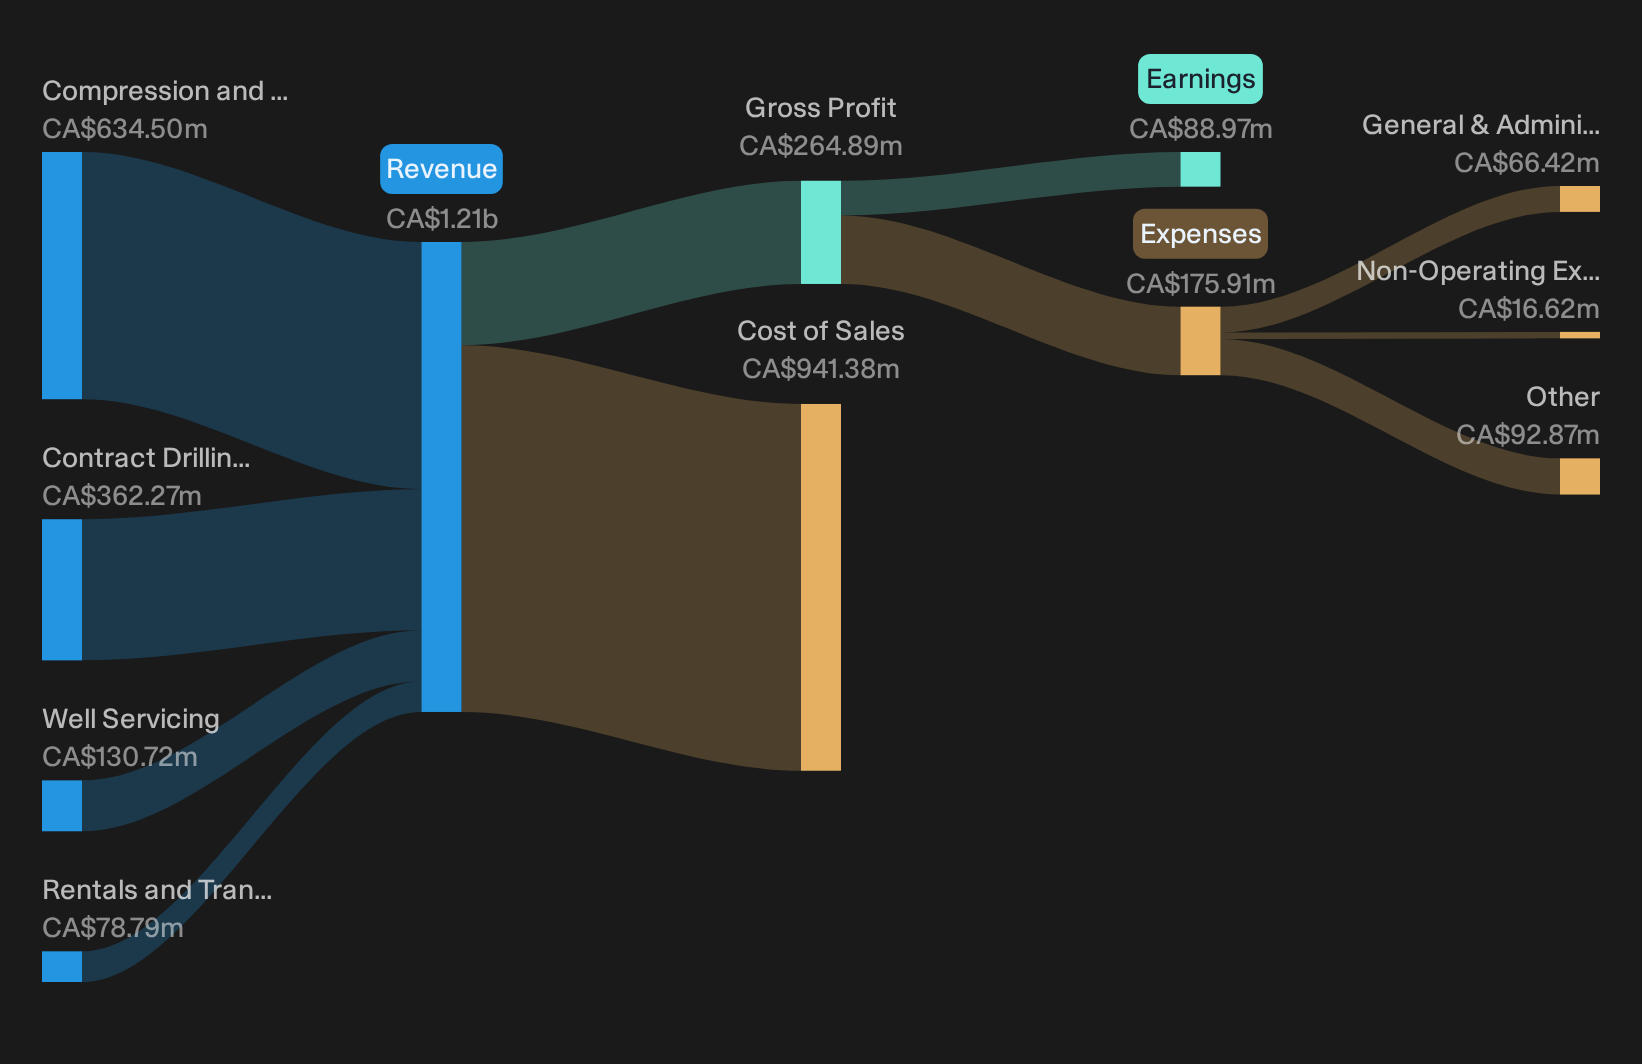
Operations: The business generates about CA$1.2b in revenue, led by CA$634 million from Compression and Process Services and CA$362 million from Contract Drilling, with activity spread across Canada, Australia, and the U.S.
Market Cap: CA$1.4b
Total Energy Services matters for this screener because its drilling and well servicing work sits directly on top of growing oil and gas activity, while a broader mix of rental, compression, and transport assets helps smooth out the cycle.
"The company is experiencing strong and growing demand for large-horsepower compression equipment, driven by the expansion of North American LNG export capacity and increased use of natural gas for power generation."
What investors will be watching now is how one ongoing shift in capital spending and pricing power filters through to future margins.
That turning point on margins is exactly what the full narrative for Total Energy Services unpacks, including how pricing, utilization, and capital discipline could reshape Total Energy Services over the next phase.
Cascades (TSX:CAS)
Overview: Cascades is a North American producer of packaging and tissue products, with e-commerce focused packaging solutions linked directly to fast growing online retail and logistics demand.
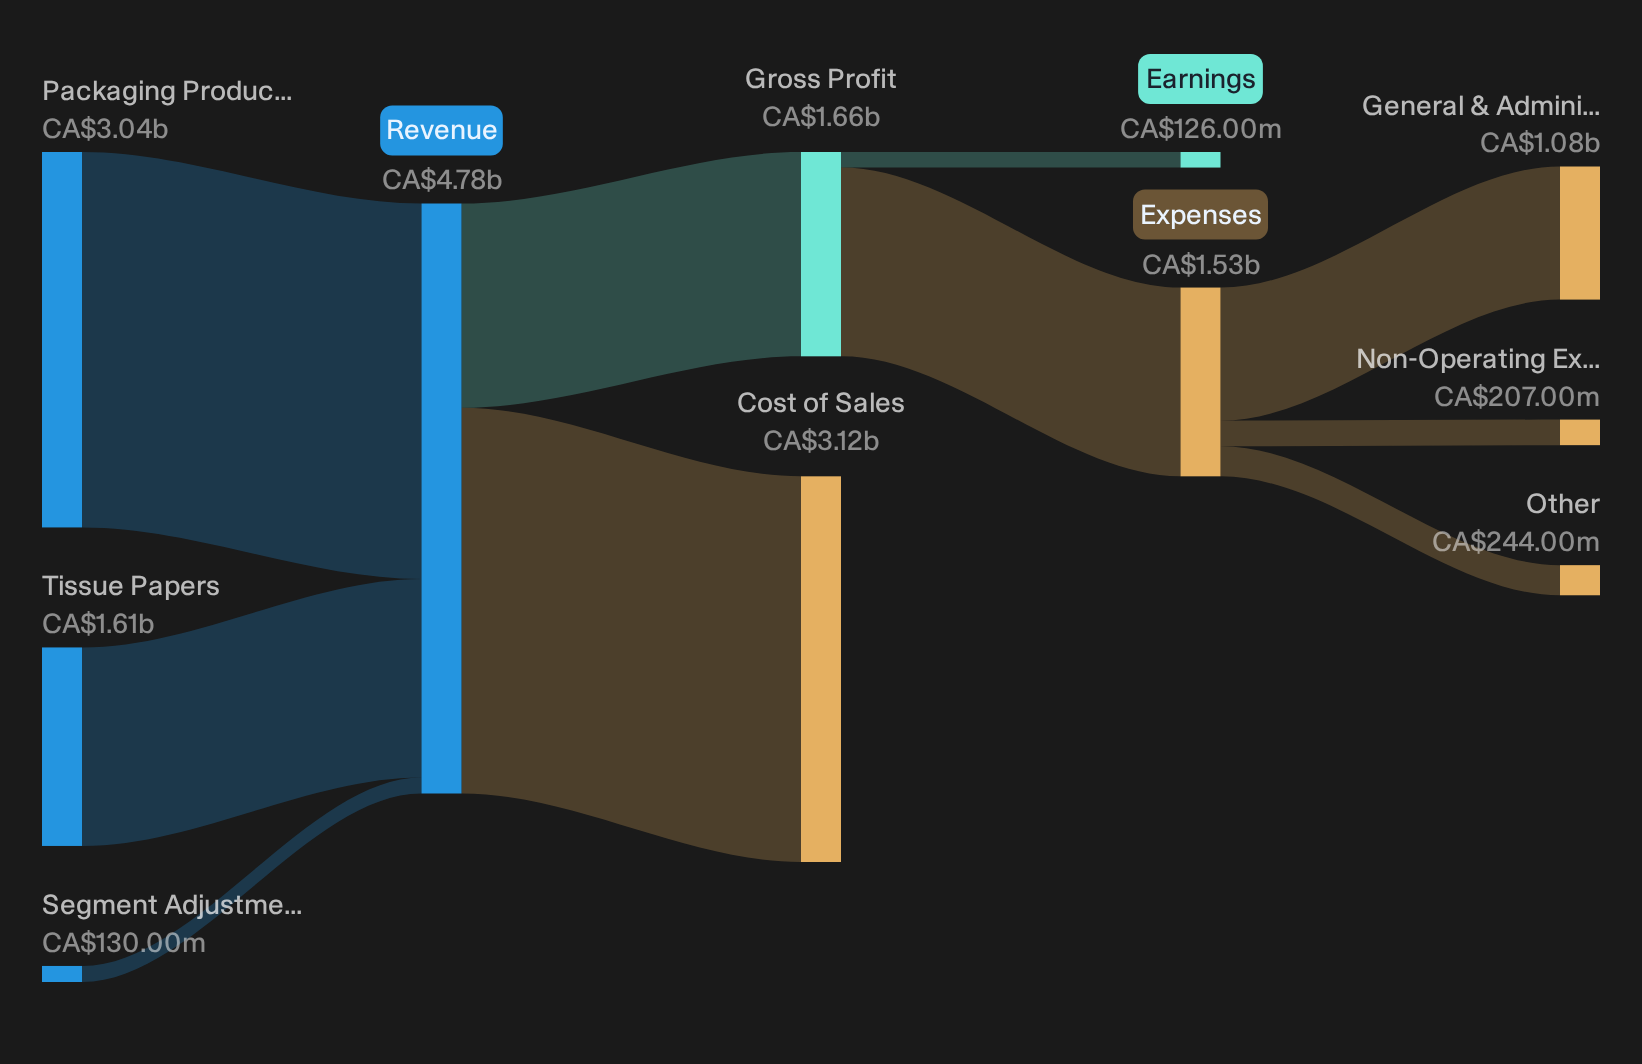
Operations: Cascades generates about CA$3.0b from Packaging Products and CA$1.6b from Tissue Papers, largely across Canada and the United States.
Market Cap: CA$1.7b
Cascades matters for this screener because its Packaging Products division supplies recycled, e-commerce ready boxes and mailers to a market where analysts and management both describe a constructive outlook on earnings growth tied to efficiency gains and greener materials.
"Continued ramp up at the Bear Island mill toward Greenpac level efficiencies, combined with targeted reductions in chemical and material usage, should lift Packaging segment productivity and support structurally higher EBITDA margins."
What really shapes the payoff for Cascades is how one emerging cost and pricing balance in packaging filters through to those future margins.
That cost and pricing balance is exactly what the full narrative for Cascades lays out in full, including where Cascades could see packaging margins quietly accelerating.
Seeking Alternatives Before The Crowd
Fresh opportunities rarely wait. Breakout stories gain momentum, laggards get caught dropping, and quiet winners stop flying under the radar for now. Scan the next wave and get in early.
- Target resilient cash generators by running the list of solid balance sheet and fundamentals (7 results) and spot businesses built to hold up when weaker peers start cracking.
- Hunt for future compounders through the 10 high quality undiscovered gems and zero in on under-followed companies with fundamentals that still look mispriced.
- Ride long term infrastructure momentum using the 42 power grid technology and infrastructure stocks and focus on operators tied to grid upgrades while that spending cycle remains under the radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com