


DEXUS (ASX:DXS) has reportedly hired Denison Partners to review the Dexus Healthcare Property Fund, exploring asset sales, new capital structures or a potential wind-up to address liquidity pressures driven by redemptions.
DEXUS shares trade at A$5.75, with a 1 month share price return of 3.42% and a 90 day gain of 1.95%. However, the year to date share price return is down 17.39% and the 1 year total shareholder return has fallen 20.29%, signalling that near term momentum has improved while longer term performance remains weak.
Compare how DEXUS’s repositioning efforts stack up against other real estate groups under pressure by scanning our curated list of solid balance sheet and fundamentals (12 results) for potential alternatives.
DEXUS trades at a clear discount to both analyst targets and an internal value estimate, yet the share price has started to recover. Where does that put fair value now that this healthcare fund review is part of the picture?
Most Popular Narrative: 1% Overvalued
DEXUS closed at A$5.75 against a widely followed fair value of A$5.70, a small premium that reflects a cautious outlook built into a relatively high discount rate of 8.66%.
Although access to diverse equity capital and the push to bring partners into the A$13b investment portfolio can release capital, moving from balance sheet ownership to lower co investment stakes rebalances the business toward fee based income. This may moderate absolute rental revenue even as funds management earnings become a larger share of the total.
See why 0 investors see DEXUS as 1% overvalued.
Result: Fair Value of A$5.70 (OVERVALUED)
Still, a successful resolution of the APAC legal appeals or stronger fee income from the A$36b funds platform could quickly challenge this cautious DEXUS narrative.
Find out about the key risks to this DEXUS narrative.
Another View On DEXUS Valuation
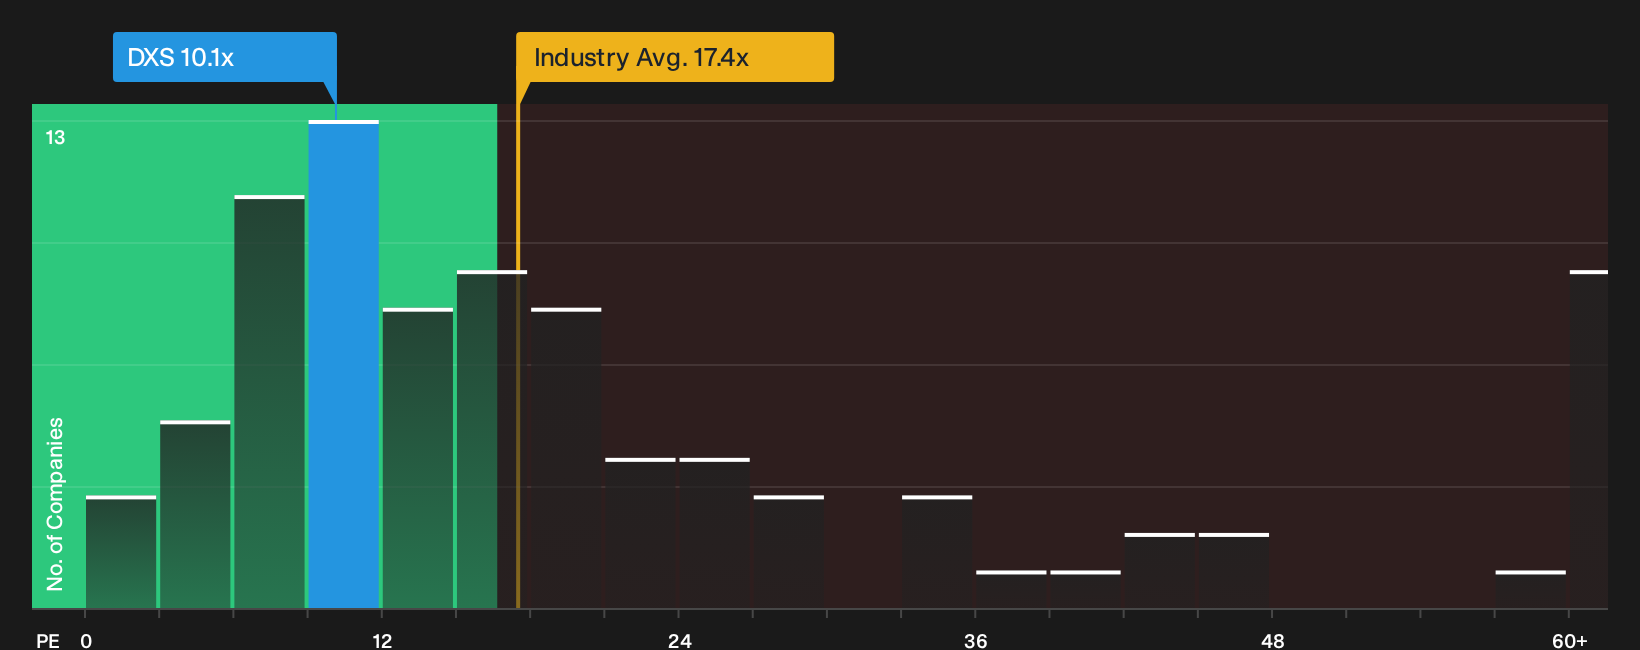
The earlier narrative framed DEXUS as slightly overvalued on a fair value of A$5.70. Using a simple earnings multiple tells a different story. DEXUS trades on a P/E of 10.1x versus 17.4x for the global Office REITs sector and a fair ratio of 10.7x, which implies a more modest pricing gap that could matter if sentiment swings.
To see how this earnings multiple stacks up against peers and what that gap could mean for future valuation risk or opportunity, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on DEXUS so far. If you want to move quickly and form your own view using the underlying data and context, review the 2 key rewards and 2 important warning signs.
Looking for more DEXUS sized investment ideas?
If DEXUS has you rethinking your portfolio balance, now is the time to scan fresh opportunities before the next wave of investors moves first.
- Target quality at a discount by reviewing the 4 high quality undervalued stocks that combine solid finances with prices that lag underlying fundamentals.
- Strengthen your income stream by assessing the 6 dividend fortresses that aim to pair higher yields with more resilient payouts.
- Dial back portfolio risk by focusing on the 6 resilient stocks with low risk scores that score well on financial resilience and volatility control.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com