


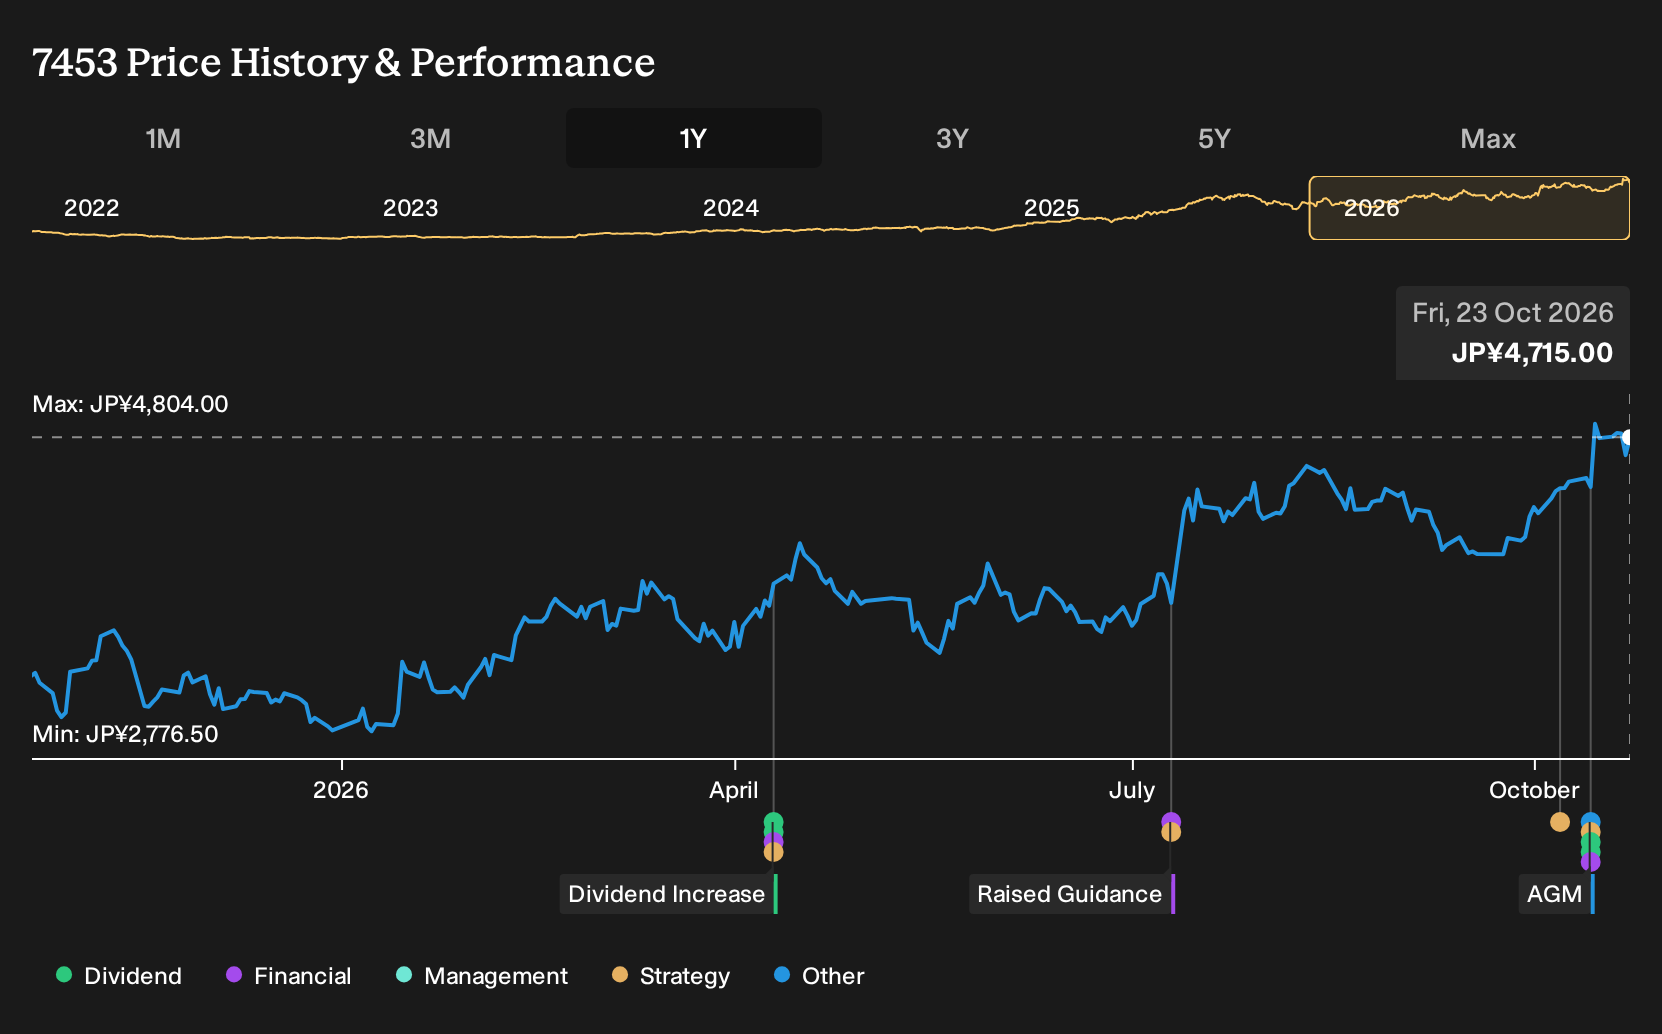
- Ryohin Keikaku outlined several shareholder returns decisions, including a proposed year end dividend of JPY 22.00 per share for FY26/8 and guidance for JPY 19.00 per share at both the second quarter and year end of FY27/8, alongside fresh earnings forecasts and board meeting details from October 2026.
- The mix of a higher year end payout for FY26/8 and a lower guided year end dividend for FY27/8 highlights how Ryohin Keikaku is balancing record profit levels with a more measured outlook for future cash returns.
- The focus now turns to how Ryohin Keikaku's revised dividend path could reshape the investment narrative that investors have been using so far.
What Is Ryohin Keikaku's Investment Narrative?
To own Ryohin Keikaku, you need to believe the MUJI ecosystem can keep drawing steady traffic across Japan and overseas while holding a tight grip on product quality and cost. The fresh guidance for operating revenues of ¥1,014,000 million and operating profit of ¥114,000 million for FY27/8 keeps the story anchored in execution on store productivity, merchandising and supply chain efficiency, rather than on financial engineering.
The new dividend path, with a higher payout linked to record profits for FY26/8 and softer guidance at ¥19.00 per share for FY27/8, signals that near term cash returns may not rise in a straight line, even as earnings are expected to grow. That is important given that the stock already trades on a P/E of 32.8x and Return on Equity is described as low, since any wobble in demand, pricing power or capital discipline can weigh more heavily on the current valuation.
Even so, there is a less obvious pressure point in the Ryohin Keikaku story that only really shows up once you look at ...
There's only one way to know the right time to buy, sell or hold Ryohin Keikaku. Head to Simply Wall St's company report for the latest analysis of Ryohin Keikaku's Fair Value.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ryohin Keikaku research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Ryohin Keikaku. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ryohin Keikaku's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ryohin Keikaku?
Once you have a view on Ryohin Keikaku, it can help to line that thesis up against other listed businesses with different risk and income profiles using the Simply Wall St Screener.
- If you want potential growth with less balance sheet stress, start by scanning companies that appear financially resilient through the 22 resilient stocks with low risk scores.
- For investors who care most about quality and valuation discipline, broaden your watchlist with the 72 high quality undiscovered gems that currently pass these filters.
- If income is your anchor and you want more ideas beyond Ryohin Keikaku, round out your research using the 29 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com