


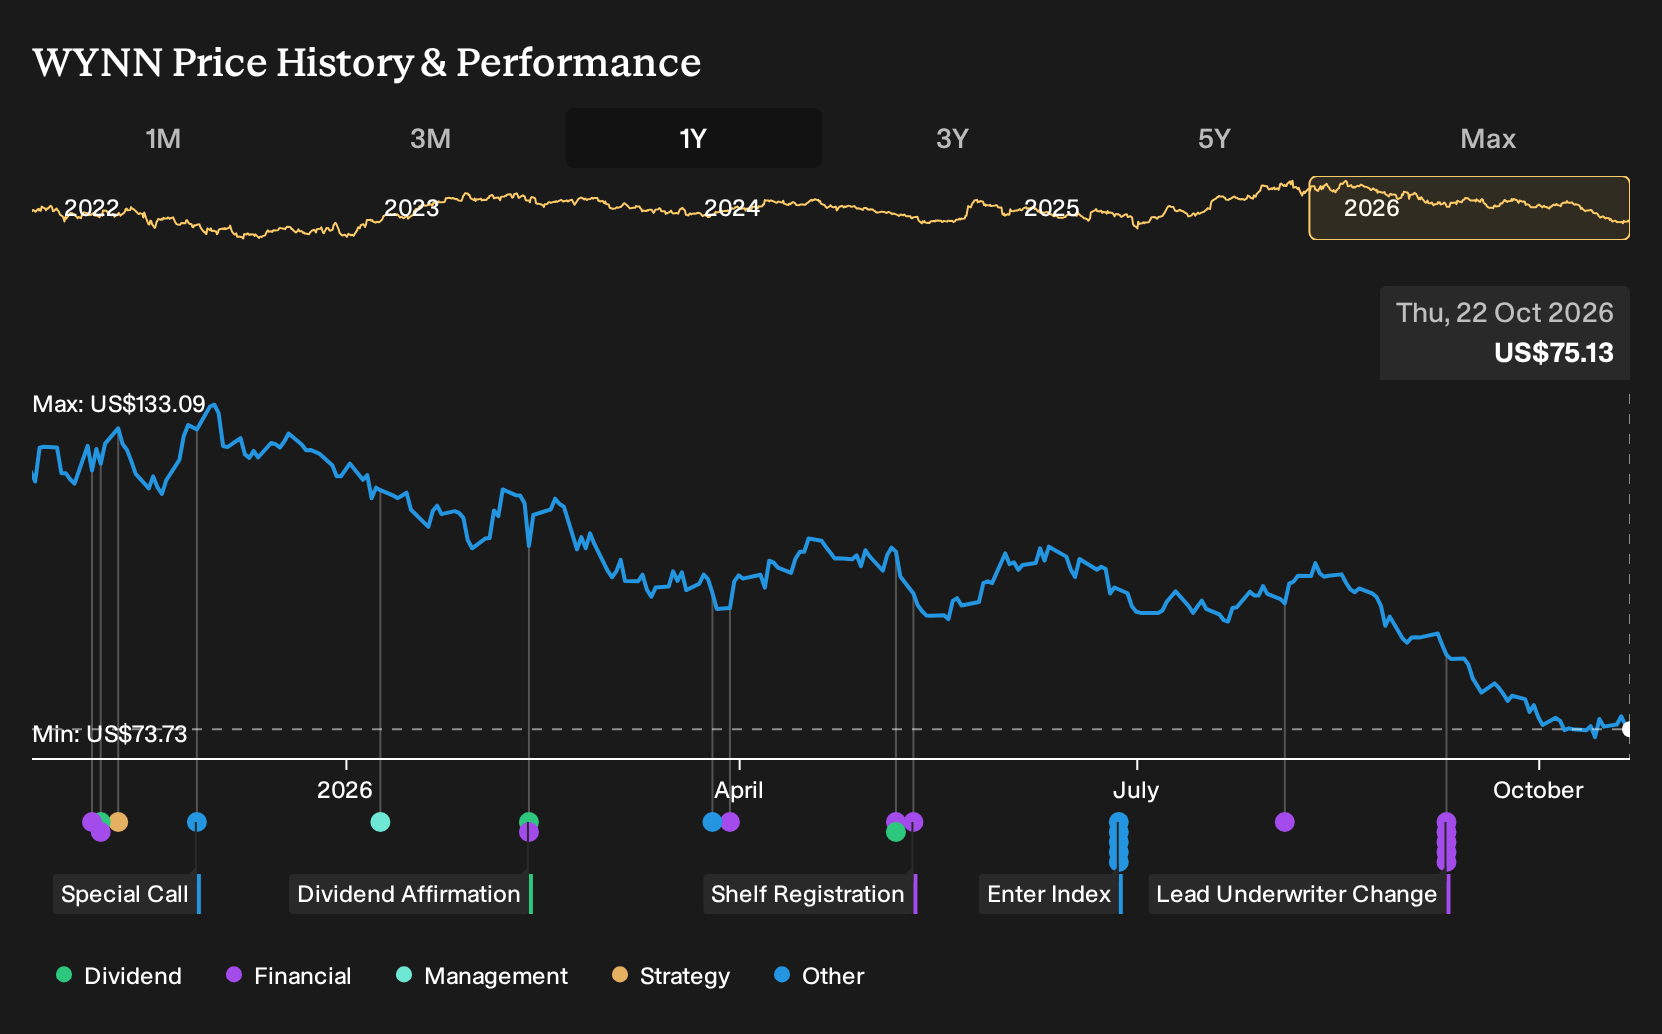
- Encore Boston Harbor, Wynn Resorts' Massachusetts property, saw Gross Gaming Revenue drop to the lowest level since February 2021 after a September 2026 strike by about 1,350 workers disrupted gaming, hotel, and food and beverage operations and raised security and other operating costs.
- The labor dispute at Encore Boston Harbor highlights how higher wage demands, service disruptions, and reputational pressure can directly affect Wynn Resorts' integrated resort model, which relies on tightly linked gaming, hospitality, and non-gaming spending to support property level profitability.
- We will now assess how Wynn Resorts' investment narrative, built around premium resorts and capital projects, could be affected by the Encore strike.
Stress test your thesis on Wynn Resorts by comparing its labor sensitive model with other operators in our hand picked 30 resilient stocks with low risk scores that may be less exposed to similar disruptions.
Wynn Resorts Investment Narrative Recap
To own Wynn Resorts you need to believe its high end resorts in Macau, Las Vegas and Encore Boston Harbor can keep attracting premium guests enough to support returns on large projects like the Enclave tower and Wynn Al Marjan Island. The Encore Boston Harbor strike directly tests that belief because the model depends on smooth, high touch service.
In the near term, the key swing factor is whether Macau and Las Vegas operations can offset disruption, higher wage pressure and lower contribution from Encore Boston Harbor. The biggest risk right now is that labor and operating costs, including security and contingency staffing, rise faster than revenue, which would squeeze EBITDAR margins across the portfolio.
Recent commentary around Encore Boston Harbor in the Massachusetts Gaming Commission data matters most here. A roughly 22% year over year and 26% month over month decline in Gross Gaming Revenue in September 2026, alongside lost food, beverage and room revenue and higher security costs, shows how quickly labor disputes can feed through to operating metrics for Wynn Resorts.
For catalysts, the same report is effectively a starting point for any recovery thesis at the property. Your question as a shareholder is whether Encore Boston Harbor can regain prior levels of gaming and non gaming activity once labor terms are settled, while the wider group continues to build out projects like Wynn Al Marjan Island and the Enclave tower without further cost creep or timing issues.
What The Encore Strike Means For Wynn Resorts' Forecasts
Wynn Resorts' narrative projects US$9.2b revenue and US$582.4m earnings by 2029. That profile rests on analysts assuming 7.4% yearly revenue growth and an earnings increase of about US$133.5m from current earnings of US$448.9m.
Uncover why Wynn Resorts' fair value indicates a 69% potential upside to its current price. This could narrow quickly as investors reassess Wynn Resorts' strike risk.
Exploring Other Perspectives
Some of the most optimistic analysts anchor their story not on Encore Boston Harbor, but on Wynn Al Marjan Island becoming a bigger earnings driver. Before this strike news, the bullish camp was pencilling in about US$9.7b of revenue and US$580.5m of earnings by 2029. You can treat that as one upbeat scenario that might be revised as new labor headlines and UAE tourism data filter through, and compare it with more cautious views to frame your own stance on Wynn Resorts.
Explore 3 other Wynn Resorts fair value estimates, including one that suggests potential upside of up to 105% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Wynn Resorts research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Wynn Resorts. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wynn Resorts' overall financial health at a glance.
Looking For More Ideas Beyond Wynn Resorts?
If the Encore Boston Harbor strike has you reassessing concentration risk in Wynn Resorts, it can help to compare it with other businesses that have very different balance sheet profiles, payout policies, and risk levels. A quick pass through a few targeted screeners can surface stocks that better match your tolerance for volatility and operational shocks.
- If capital preservation and fewer surprises matter most to you, focus on companies with sturdier finances and lower risk scores through the 30 resilient stocks with low risk scores.
- If you want resilient income streams instead, concentrate on businesses offering stronger yields and a history of paying out to shareholders via the 6 dividend fortresses.
- If you are hunting for mispriced quality, filter for stronger fundamentals that are not yet widely recognized in the market by using the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com