


Hycroft Mining Holding (HYMC) put fresh drilling results in front of investors after reporting the highest grade intercept in its history from the 2025 to 2026 exploration program.
The fresh resource update lands after a sharp pullback, with Hycroft Mining Holding’s share price down 30.54% over the past month and 35.41% year to date, even as the 1-year total shareholder return sits at 111.54% and the 3-year total shareholder return is very large. This suggests long term holders have seen strong swings in value while short term momentum has faded.
Scan how Hycroft Mining Holding stacks up against other miners by reviewing our hand picked 35 elite gold producer stocks, positioned for potential resource upgrades and drilling catalysts.Big drill hits meet a falling share price, so the question now is whether Hycroft Mining Holding still offers enough upside potential to compensate for the recent drawdown when you run the numbers.
Preferred Price-to-Book of 5.9x: Is it justified?
On the latest figures, Hycroft Mining Holding trades on a P/B ratio of 5.9x while the broader US Metals and Mining group sits at 2x and the company level peer set is at 3.4x. That is a rich tag for a $15.76 stock in a sector where many investors lean heavily on asset values and balance sheets to frame expectations.
P/B compares the share price with the book value of equity. It links what you pay in the market to the accounting value of net assets such as the Hycroft Mine claims. For a pre profit developer with minimal reported revenue and a loss of $86.205m, a premium multiple like this usually signals that the market is placing a lot of weight on factors such as future drilling success, resource growth or potential production rather than the current income statement.
The gap to peers is sharp. At 5.9x P/B against 3.4x for similar miners and 2x for the wider US Metals and Mining industry, investors are clearly paying a higher price relative to book value than is typical across the group. This points to expectations that the resource base or cash flow profile could justify that premium over time.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-book of 5.9x (OVERVALUED)
Still, setbacks such as weaker drilling outcomes or further share price volatility could quickly challenge the premium that investors are currently paying for Hycroft Mining Holding.
Find out about the key risks to this Hycroft Mining Holding narrative.
Another View: Our DCF Model Paints A Different Picture
The same Hycroft Mining Holding that looks expensive on a 5.9x P/B ratio screens very differently when run through the SWS DCF model. On those cash flow assumptions, an estimated fair value of $44.93 against a $15.76 share price suggests the stock is trading well below that implied worth. If the market is leaning on asset value while the model leans on future cash generation, which lens should matter more to you?
Look into how the SWS DCF model arrives at its fair value.
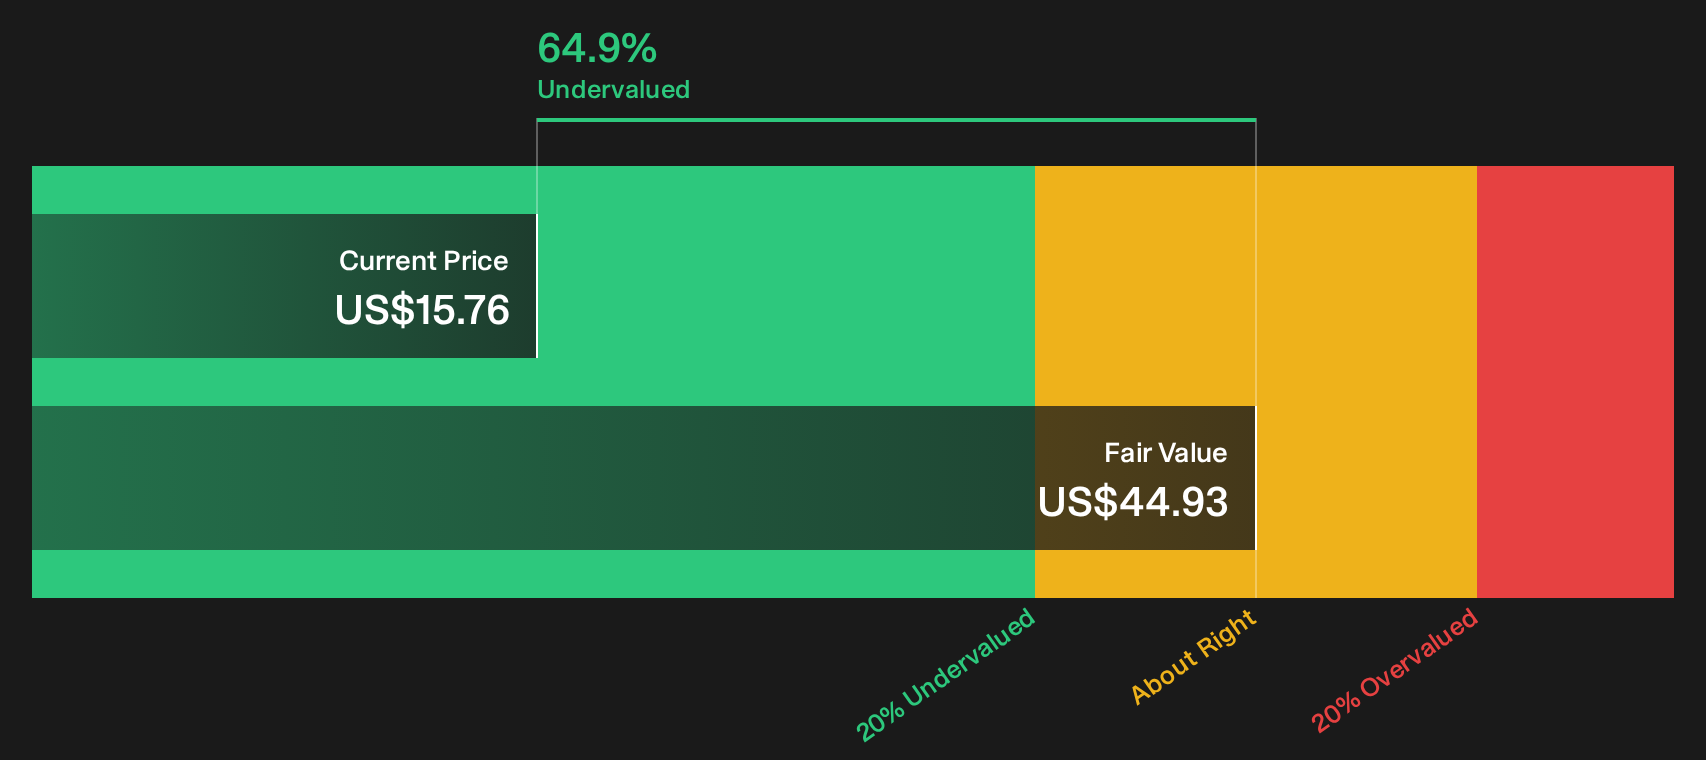
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hycroft Mining Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Hycroft Mining Holding can be confusing, so move quickly, review the data yourself, and weigh the 2 key rewards and 4 important warning signs against your own expectations.
Looking for more investment ideas beyond Hycroft Mining Holding?
If Hycroft Mining Holding has your attention, broaden your watchlist with a few focused stock ideas that match different risk levels and return profiles.
- Target potential mispricing by scanning a curated set of companies that combine quality and attractive valuations through the 29 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that offer robust yields and payout histories via the 6 dividend fortresses.
- Protect your downside risk by researching companies with resilient balance sheets and fundamentals using the list of solid balance sheet and fundamentals (26 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com