


Agnico Eagle Mines has delivered a powerful share price run over the past few years, yet the recent pullback is forcing investors to ask whether the current tag can still be explained by its earnings. With the spotlight back on fundamentals after analyst downgrades, the question is how much of Agnico Eagle’s story is already reflected in what you are paying for its profits today.
- Over the past 3 years the stock has returned about 2.9x, which puts a lot of focus on whether the earnings base is strong enough to carry that kind of re-rating.
- Freedom Broker’s recent downgrade, which cited trimmed near term EBITDA forecasts and operational risks, highlights how changes in expected profitability can quickly alter what looks reasonable for Agnico Eagle’s earnings multiple.
- There is a second opinion on Agnico Eagle Mines worth weighing. See what analysts think Agnico Eagle Mines's shares could be worth.
The issue now is whether Agnico Eagle’s current share price around US$176, after recent declines, is appropriately aligned with the earnings power that the business is generating.
If you want to pressure test whether Agnico Eagle Mines is the outlier or part of a broader pattern, compare it with other 35 elite gold producer stocks
Does Agnico Eagle Mines Look Undervalued on Earnings?
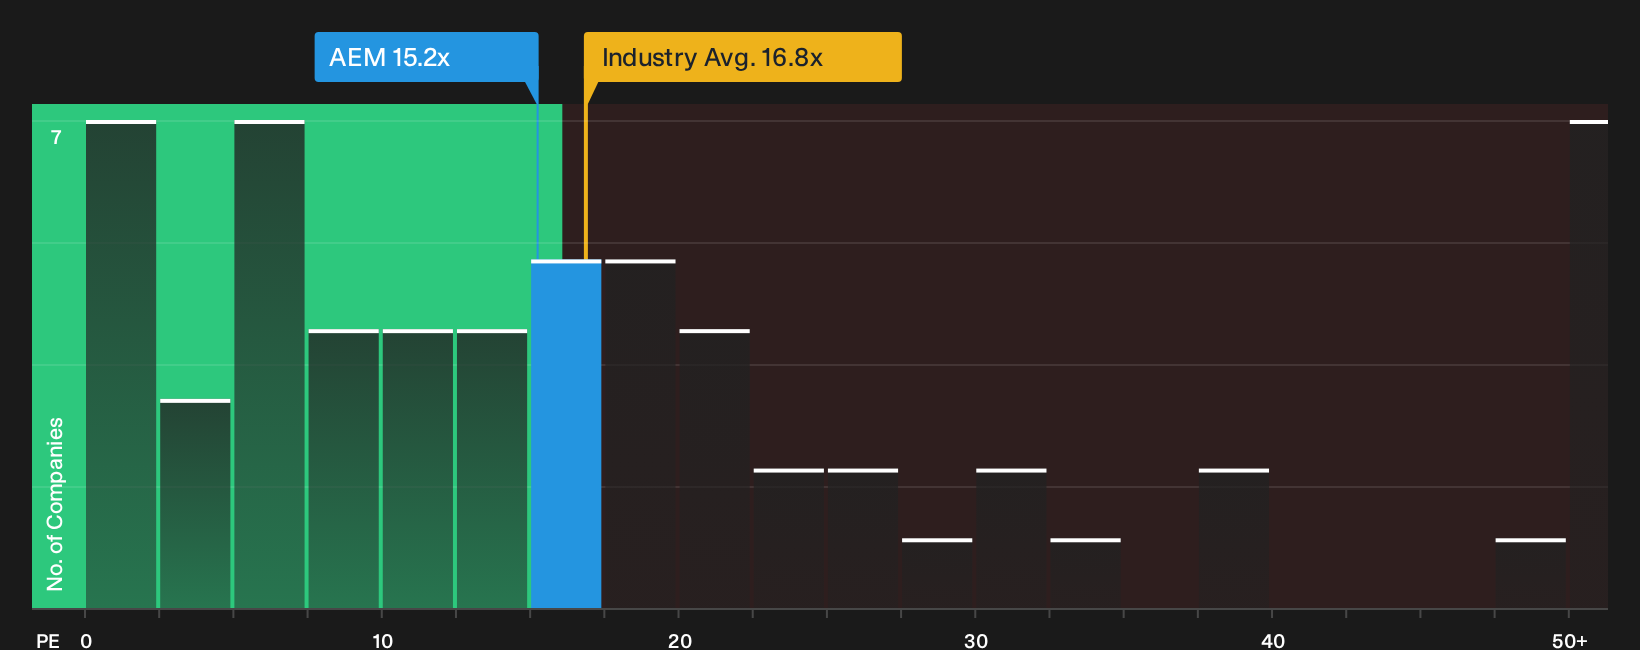
The P/E ratio suits Agnico Eagle Mines because earnings still anchor how investors judge a mature gold producer. On that metric, the stock changes hands at about 15.2x trailing earnings, which is slightly below the broader metals and mining sector on roughly 16.8x and under the peer group closer to 17.2x. For a reader, that means the market is not placing a clear premium on Agnico Eagle’s current earnings stream compared with similar resource stocks.
Freedom Broker’s downgrade, which pointed to trimmed near term EBITDA and operational risks, has pressured sentiment. Yet the current multiple still screens below the level suggested by a more tailored fair P/E for Agnico Eagle Mines that blends its sector, profitability profile and risk. That gap implies investors are pricing in some caution around those flagged risks, so you would want to weigh how durable you think the earnings base is before treating the discount as an opportunity. Explore the numbers behind Agnico Eagle Mines's P/E valuation.
The Agnico Eagle Mines Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Agnico Eagle Mines give you a way to spell out the future that would need to unfold for the current P/E and any fair value estimate to make sense. Narratives link Agnico Eagle Mines' share price to clear assumptions about future growth, margins and earnings, and where a single ratio or model outputs one figure, they lay out the path that number relies on so you can watch how reality compares over time on the Community page.
Community views on Agnico Eagle Mines pull in opposite directions, with one camp focusing on a fixable production puzzle and the other on execution risk and cost pressure.
Bull case: 100% undervalued
"Agnico's Canadian Malartic mill is a processing monster, handling roughly 55,000 to 60,000 tonnes of ore per day..."
Discover why this Narrative puts Agnico Eagle Mines at 100% undervalued.
Bear case: 47% overvalued
"The regional hub model, long project list and capital return framework only work if Agnico Eagle Mines continues to convert its large growth pipeline into reliable low cost production..."
Explore why this Narrative puts Agnico Eagle Mines at 47% overvalued.
One more Agnico Eagle Mines piece that could change how you see the whole story
Numbers only tell part of the story for Agnico Eagle Mines, because the people steering the assets and how they are rewarded can tilt risk and reward in ways the P/E alone cannot. See who runs Agnico Eagle Mines and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com