


Rare earth magnets have quietly become the muscle behind modern defense, and growing pushback against China’s grip on this supply chain is forcing a reset in where and how these materials are produced. That shift is already pulling fresh attention toward North American players like REalloys and peers in permanent magnets and motors. This article breaks down three stocks exposed to that same news, and why their stories deserve a closer look now.
The stocks covered below are just a first cut, and the full screen has surfaced 15 more North American defense linked permanent magnet and motor manufacturers with equally compelling narratives that are not included in this article. To identify and analyze the highest conviction plays in this space, head straight into the North American Defense-Linked Permanent Magnet & Motor Manufacturers screener.
Novanta (NOVT)
Novanta plugs directly into the screener’s focus on high performance motion control, with its precision medicine, manufacturing and robotics hardware closely tied to the same permanent magnet and motor supply chain that REalloys aims to support for domestic and defense linked customers.
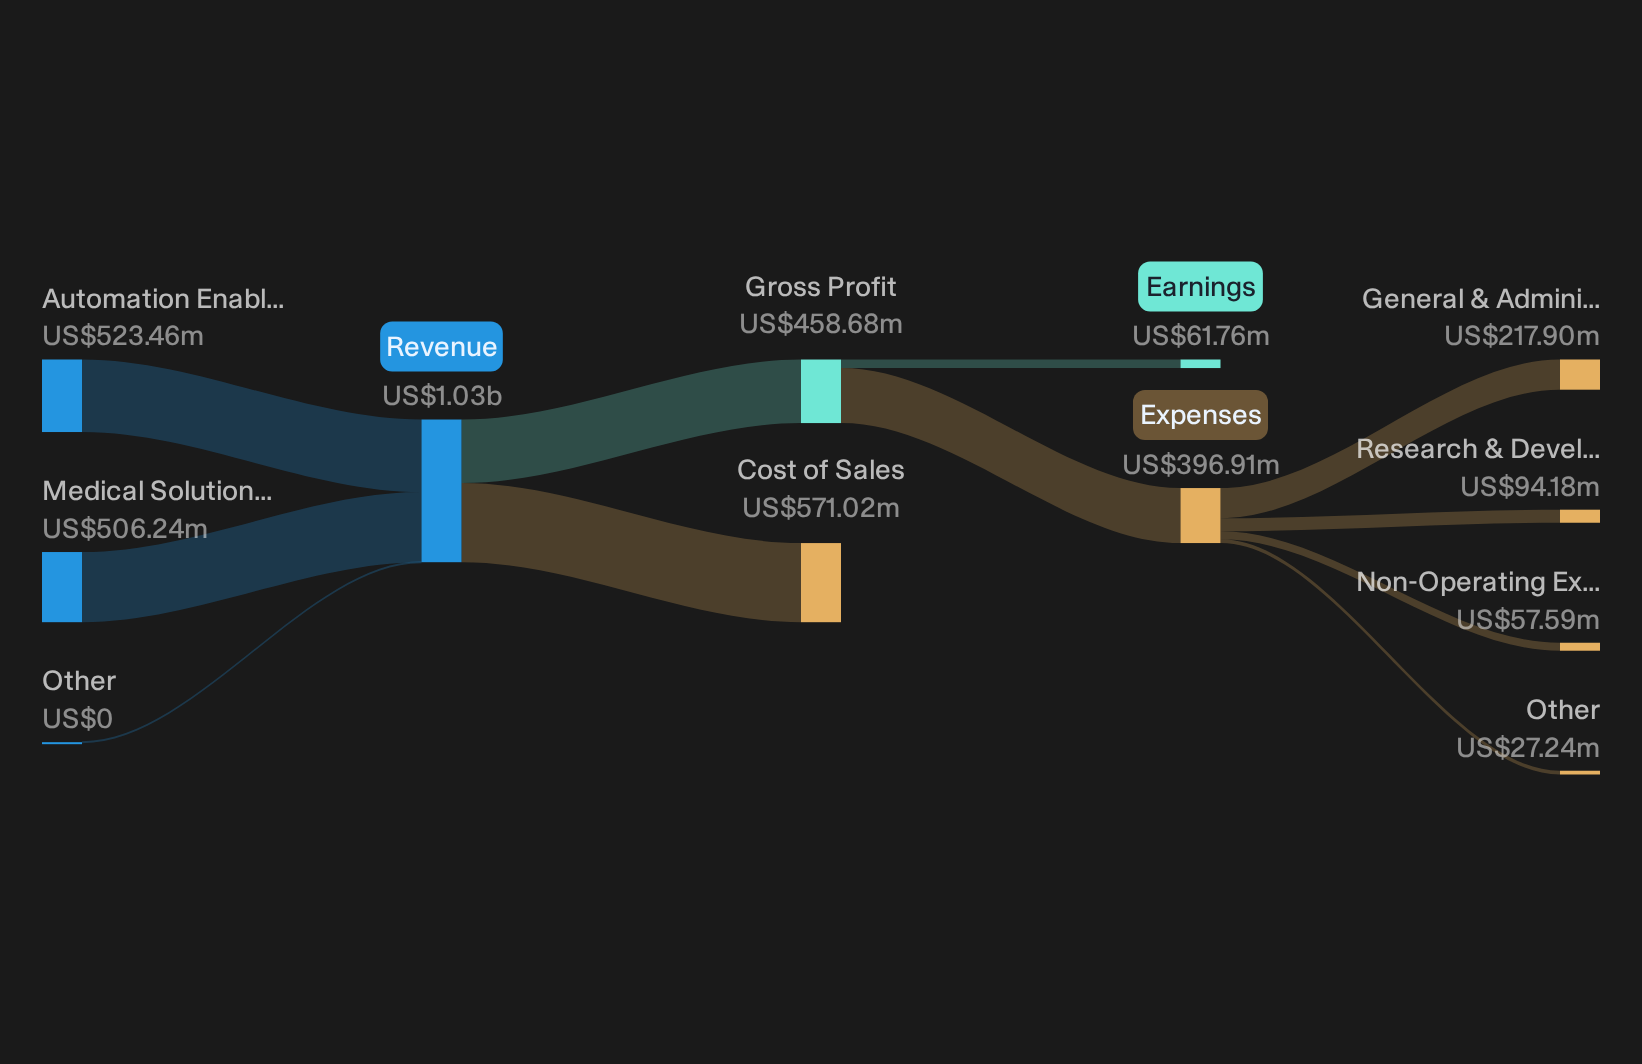
Novanta generates roughly US$523 million from Automation Enabling Technologies and about US$506 million from Medical Solutions, reflecting a fairly balanced mix across industrial motion and medical technologies, while the stock’s market value sits around US$5.3b.
"Expansion of minimally invasive and robotic surgery, together with the Riverpoint Medical acquisition that roughly doubles recurring medical consumables revenue to about US$300 million and lifts medical exposure to around 60% of sales, increases Novanta's mix of repeat consumables that can support more resilient revenue and gross margin over time."
What happens when that shift in mix meets one unresolved pressure on how efficiently each extra dollar of capital turns into profit?
That tension is exactly what makes the full narrative for Novanta worth reading, both for how Novanta’s consumables engine could decouple earnings quality from capital strain and for what risks are still masking beneath.
Rogers (ROG)
Rogers connects into the defense linked permanent magnet and motor story through the high reliability substrates and materials that sit under power electronics. However, the real interest for investors comes from how that portfolio lines up with electrification and next generation electronics.
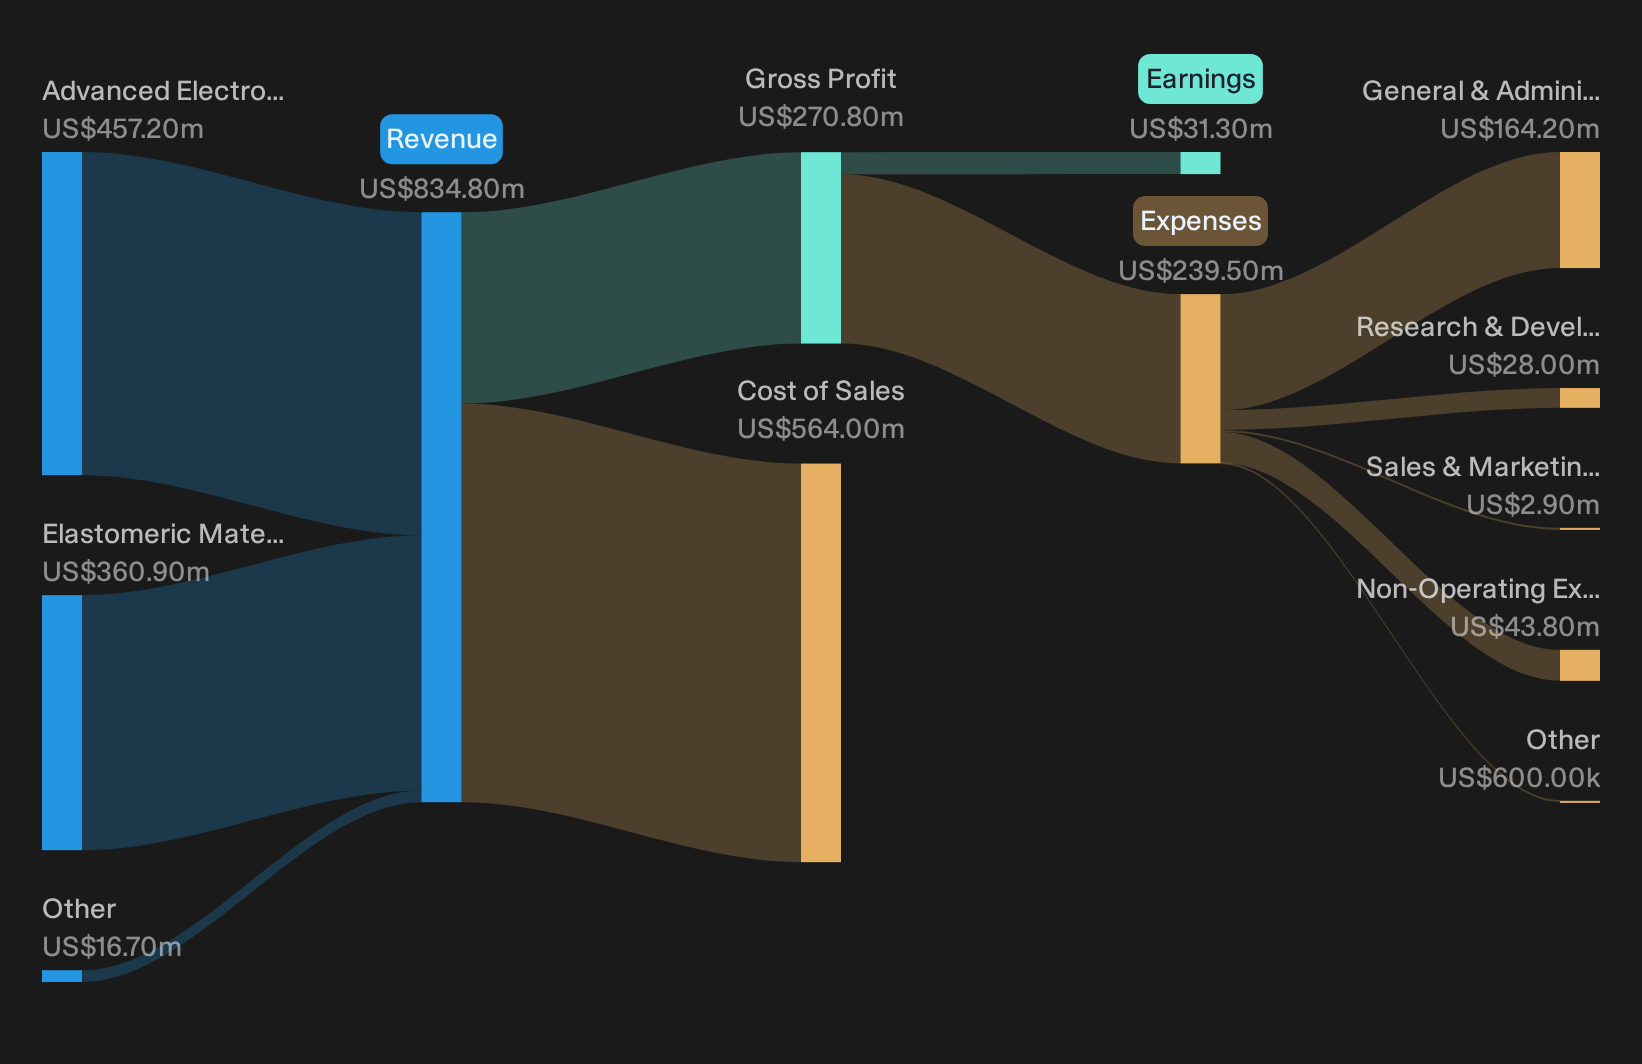
Rogers develops engineered materials and components for high performance electronics across autos, industrial systems, and aerospace, with around US$457 million from Advanced Electronics Solutions, US$361 million from Elastomeric Material Solutions, and a smaller US$17 million from Other activities, and the stock is valued at roughly US$2.5b.
"Rogers is positioned to benefit from long-term growth in electric vehicles and broader electrification trends globally, as evidenced by an expanding customer base in China's EV market and design wins with leading local power module manufacturers, which supports higher future revenue and earnings from automotive content."
The real swing factor is how one planned step change in profitability interacts with the capital and execution load required to support that electrification push.
That profitability inflection is exactly why the full narrative for Rogers digs into where returns could accelerate, what might stall them, and how investors can weigh that trade off.
CPS Technologies (CPSH)
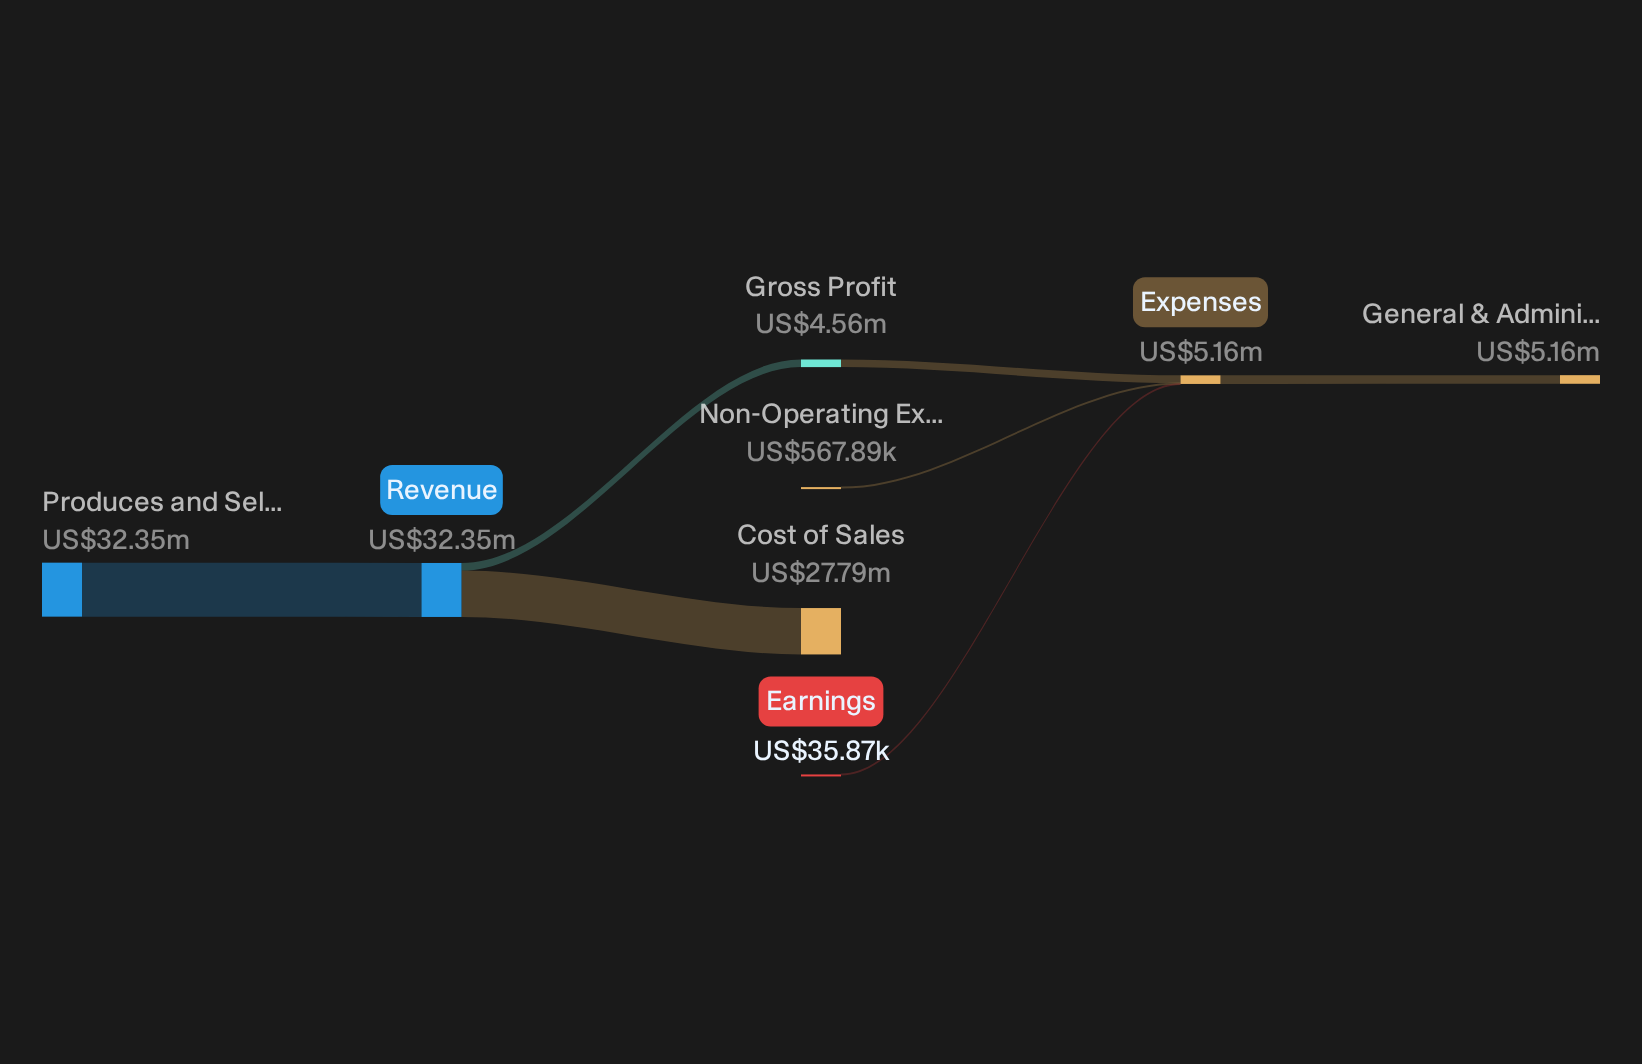
CPS Technologies plugs into the defense linked magnet and motion control theme through the advanced metal matrix composites that sit under power electronics. All of its roughly US$32 million in sales come from these material solutions and the market value sits near US$68 million.
CPS Technologies gives investors a pure play on advanced materials that help power electronics run cooler and lighter, with direct exposure to aerospace and defense systems that are likely to lean harder on secure rare earth magnet and motor supply chains.
"The planned move to a significantly larger, more efficient manufacturing facility funded by the recent capital raise should expand capacity and improve throughput. This positions CPS to leverage operating leverage and lift gross and operating margins."
What really moves the needle is how demand from one set of highly specialized defense and power electronics programs interacts with that extra capacity.
That capacity question is exactly where the full narrative for CPS Technologies pulls the story together, unpacking how CPS Technologies could turn niche defense demand into accelerating, less volatile earnings power.
Curious About What You Might Be Missing?
Fresh themes can gain momentum quickly, and some ideas may move before most investors notice. Scan these under the radar lists while they are still timely and consider them early in your research.
- Focus on steadier compounding potential by looking at companies with fortress-like finances through the list of solid balance sheet and fundamentals (26 results) before they become widely followed.
- Follow structural demand for critical materials by tracking producers highlighted in the 16 top copper producer stocks while valuations still reflect earlier-stage developments.
- Explore cash generative automation businesses by reviewing the curated 95 robotics and automation stocks before more attention turns to the most efficient operators.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com