


Oppenheimer Holdings (OPY) has drawn attention after recent share performance, with the stock down about 10% over the past month and roughly 7% over the past 3 months based on the latest returns.
Zooming out, Oppenheimer Holdings still shows strong long-term progress, with a year-to-date share price return of 40.5% and a 1-year total shareholder return of 51.61%. However, recent monthly weakness suggests momentum has cooled following a very large 3-year total shareholder return of 216.94%.
Scan 29 high quality undervalued stocks, hand picked to share Oppenheimer Holdings' mix of strong long-term returns and recent pullbacks that may interest investors watching for changing momentum.
After that pullback, Oppenheimer Holdings now trades at about $102, while the modelled intrinsic value appears much lower. Is the market too optimistic, or are the estimates too harsh on this broker dealer?
Preferred P/E of 10.6x: Is it justified?
On simple earnings terms, Oppenheimer Holdings looks cheap. The stock trades at a P/E of 10.6x against the latest close of $102.06, while the broader US market sits at 18.3x and the US Capital Markets peer group at 37.6x.
The P/E ratio compares what investors pay for each dollar of current earnings. For a broker dealer like Oppenheimer Holdings, which earns fees and commissions across wealth management and capital markets, this measure helps you see how the market is pricing its profit engine relative to other listed financial firms.
Here the gap is wide. The 10.6x P/E is well below both the overall US market and the Capital Markets industry average, and it is also lower than the peer average of 15.5x. That kind of discount suggests investors are either cautious about the business given earnings have declined by 8.9% per year over the past 5 years, or they are not willing to pay up despite OPY reporting high quality earnings and 17.5% earnings growth over the past year.
Result: Preferred multiple of 10.6x price-to-earnings (UNDERVALUED).
See what the numbers say about this price — find out in our valuation breakdown.
Still, the narrative around Oppenheimer Holdings can flip quickly if fee income softens across wealth and capital markets, or if regulatory costs climb faster than expected.
Find out about the key risks to this Oppenheimer Holdings narrative.
Another view on Oppenheimer Holdings: cash flows tell a different story
Earnings multiples present Oppenheimer Holdings as relatively inexpensive, yet the SWS DCF model indicates something different. At a share price of $102.06, the stock is trading above an estimated future cash flow value of about $70, which points to an overvalued outcome on this measure rather than a bargain.
This gap matters because it highlights how sensitive an investment thesis can be to the earnings line compared with long-term cash generation. If the P/E view is more applicable, the shares may appear to trade at a discount. If the DCF view is closer to reality, investors may be paying a higher price relative to estimated cash flows. Which lens aligns better with your approach to investing.
Look into how the SWS DCF model arrives at its fair value.
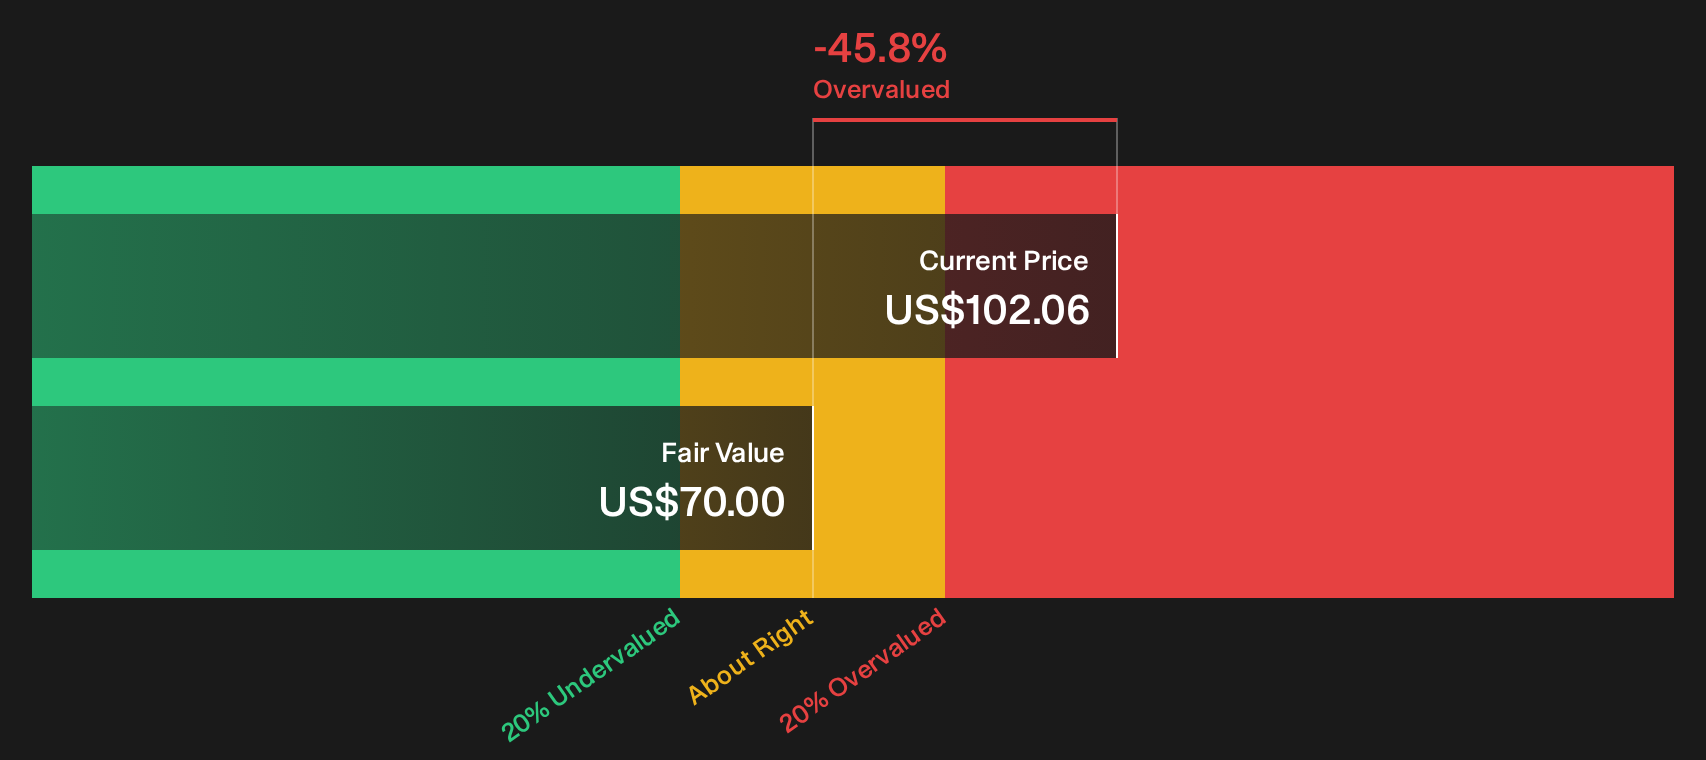
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Oppenheimer Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Oppenheimer Holdings so far. If the contrast between valuation and cash flows has you curious, move quickly, stress test the story with your own research, and then round out your view by weighing the 1 key reward and 1 important warning sign
Looking for more investment ideas beyond Oppenheimer Holdings?
If the Oppenheimer Holdings valuation debate has you thinking bigger, broaden your search now and line up a few more candidates before the next move.
- Target reliable income by reviewing a shortlist of potential high yield opportunities with the 6 dividend fortresses.
- Hunt for stronger balance sheets by scanning a list of solid balance sheet and fundamentals (26 results) that can help support resilience when conditions change.
- Get ahead of the crowd by checking a focused group of 20 high quality undiscovered gems that might not be on every investor's radar yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com