


American Express (AXP) shares slipped after the credit card giant reported mixed Q3 results and announced plans to eliminate about 3,500 jobs worldwide. The layoffs, representing about 5% of the company’s global workforce, accompany a restructuring to simplify operations and control costs.
Including the post-earnings decline, American Express stock is down roughly 17% versus the start of 2026.
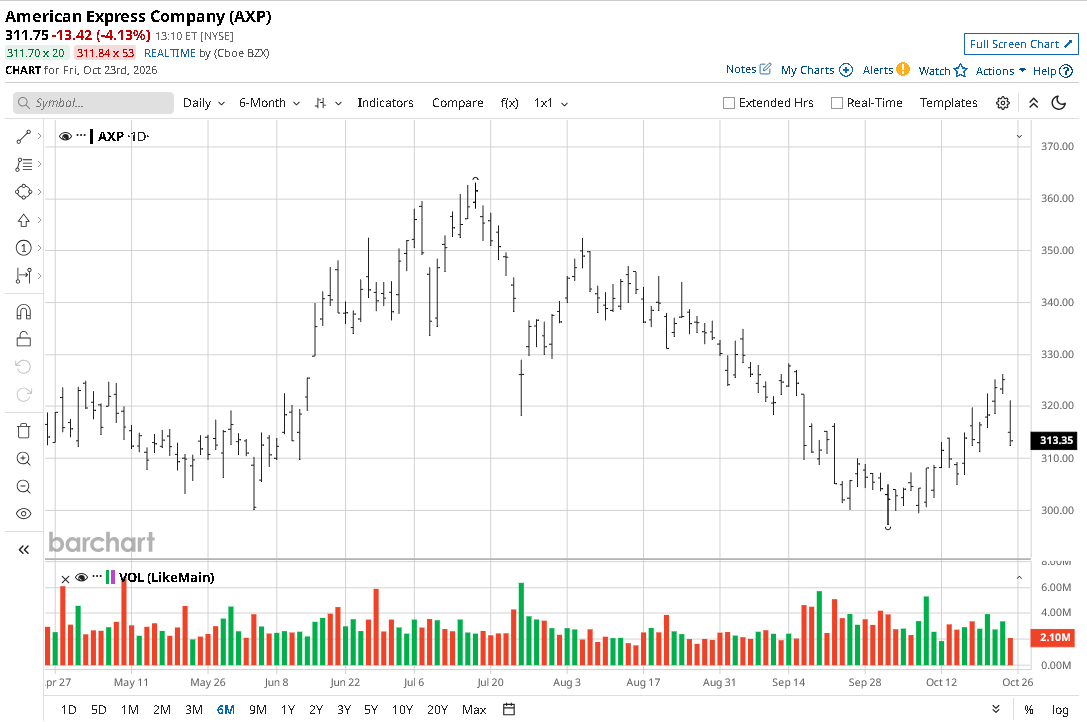
What Layoffs Mean for American Express Stock
In a statement on Friday, CEO Stephen Squeri said these layoffs will remove organizational layers and accelerate decision-making, positioning AMEX to become “more agile and prepared for AI.”
The company recorded a $336 million pretax restructuring charge, partly funded by proceeds from selling its stake in Global Business Travel Group.
As American Express commits to a “leaner operating structure,” it will likely have more money to invest in its future growth; that’s the bullish thesis for AXP shareholders.
However, savings will need to offset persistent spending pressures: Q3 expenses came in up some 9% to $14.5 billion, with rewards costs and marketing expenses up 10% and 11%, respectively.
In short, cutting jobs offers one expense lever, but retaining premium customers evidently remains costly for American Express.
What’s Hurting AMEX Shares Today?
American Express posted better-than-expected 13% year-on-year growth in adjusted earnings per share (EPS) and raised the bottom end of its full-year guidance to $17.6 per share. Yet, billed business at $454 billion came in below the $457 billion consensus, partly reflecting exit from small-business co-brand relationships.
That shortfall offers a clearer explanation for Friday’s selloff in AXP shares.
Meanwhile, earnings quality deserves attention as well. Reported EPS of $5.42 benefited from the business-travel investment sale, while credit-loss provisions declined on a year-over-year basis.
These figures make the headline profit growth much less representative of the underlying operating momentum.
Wall Street’s View on American Express
Investors should note, however, that Wall Street firms favor treating the post-earnings dip in AXP stock as a buying opportunity.
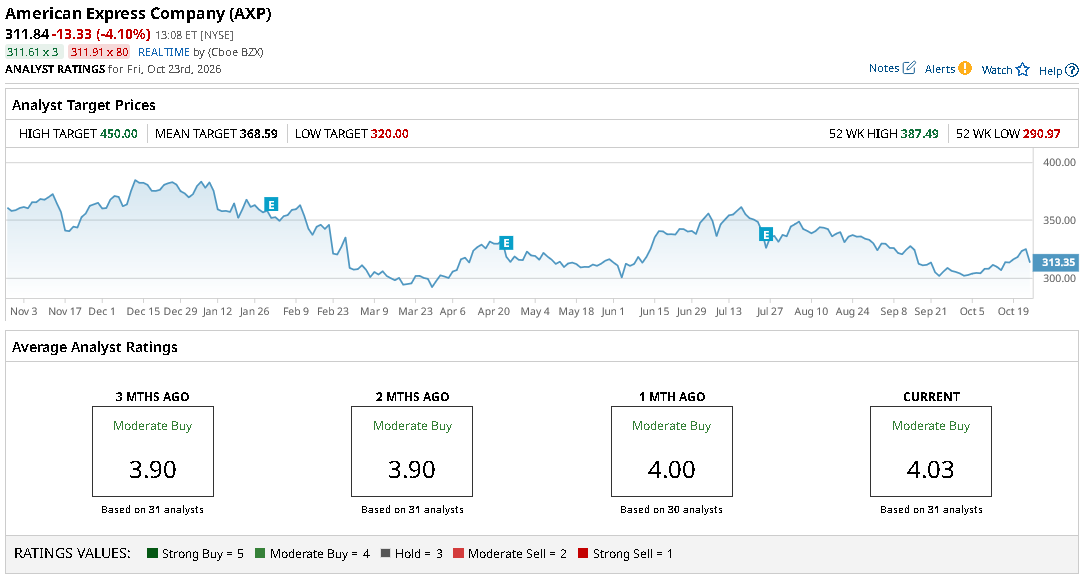
The consensus rating on American Express remains at “Moderate Buy,” with the mean price objective of about $369 indicating significant upside potential from current levels.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.