


IREN Limited has swung from a very large three year gain in its share price to a steep pullback this year, which puts an uncomfortable spotlight on whether the current US$25.51 price still lines up with the sales its expanding AI data center business can realistically support. For anyone tracking IREN, the question now is less about headlines and more about what the revenue base can carry.
- Over the past three years the stock has returned roughly 7x, so a lot of future sales growth is already in focus when you look at today’s valuation.
- Plans for multi billion dollar data center campuses in Australia and Europe, along with large AI cloud commitments, may support higher long term revenue but also point to heavy capital needs that matter for any sales based multiple.
- The analysts covering IREN have run their own numbers. See what analysts think IREN's shares could be worth.
The issue now is whether IREN's current share price is justified by the level and quality of its sales given this mix of rapid expansion and recent share price declines.
To pressure test whether IREN's sales based valuation still makes sense after a 3 year 7x gain and a steep pullback this year, it can help to compare against 55 AI infrastructure stocks.
Does IREN Look Fairly Valued on Sales?
P/S fits IREN because investors are focused on what its current and future AI data center sales might support rather than near term earnings.
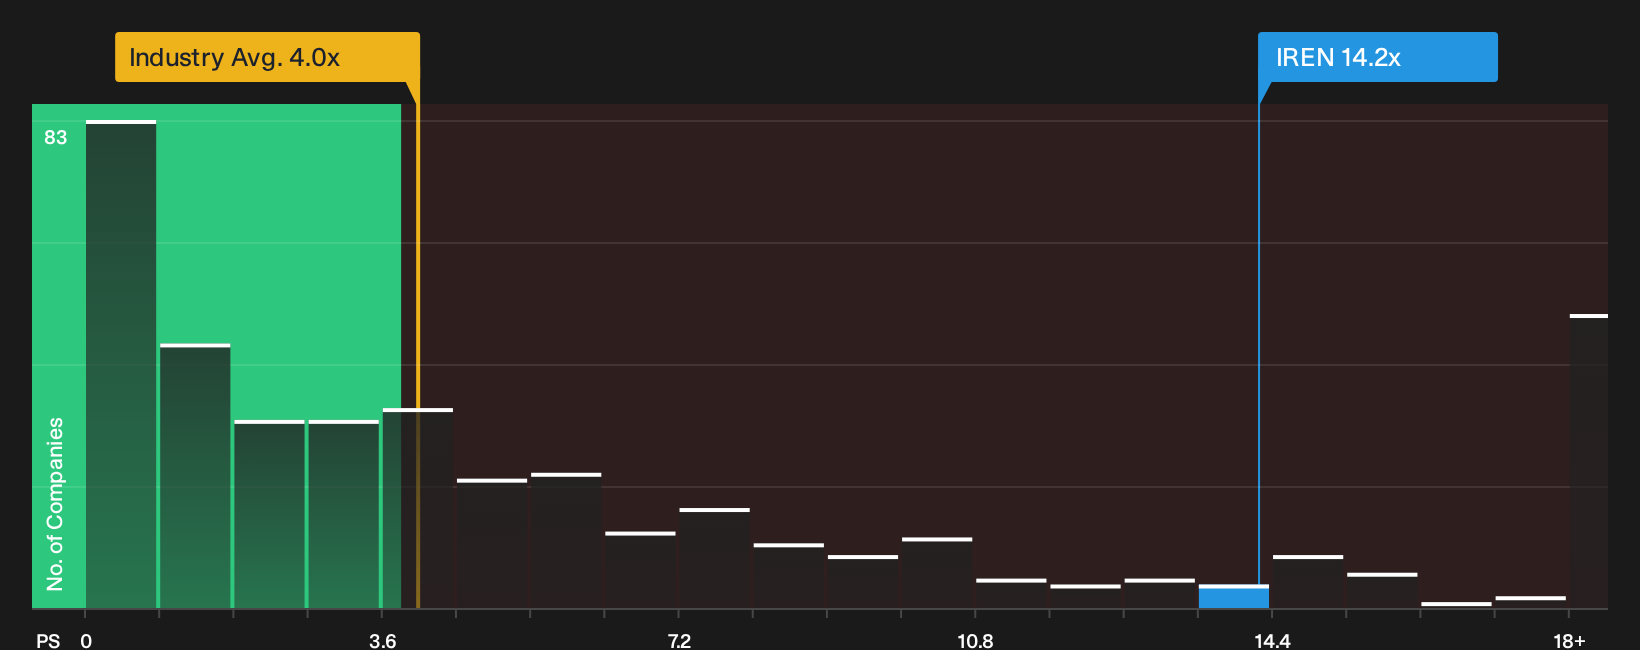
On that yardstick, IREN trades on a P/S ratio of about 14.2x, compared with roughly 4.0x for the broader Software industry and around 9.9x for closer peers. The stock therefore carries a clear premium to both sector and peer groups. Based on the modelled fair multiple, which blends the company’s growth profile, profitability potential, risk and size, the current P/S sits close to where that framework would expect it to be.
News around large AI projects like the proposed US$10b Redbank campus and the Badajoz build in Spain helps explain why investors are still willing to ascribe a higher sales multiple, even after the recent pullback. The key question for you is whether that elevated P/S ratio feels justified given the capital intensity, heavy commitments and execution risk that come with IREN’s expansion plan. Explore the numbers behind IREN's P/S valuation.
The IREN Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for IREN act as the missing link between the current P/S premium and the question of what has to go right or wrong from here. Each scenario ties IREN's valuation to a clear path for growth, margins and earnings, and assigns a fair value to a specific mix of potential catalysts and risks so you can track over time which version of IREN's story is actually unfolding.
One of the top community narratives on IREN: 64% undervalued
"IREN represents an intriguing yet risky investment opportunity in the evolving landscape of Bitcoin mining and computational services..."
Discover why this Narrative puts IREN at 64% undervalued.
Before you move on from IREN, one more check belongs next to the price tag
Headline projects and premium P/S only tell part of the story, because IREN also carries specific risk flags that could change how you view that valuation once you see them. Take a closer look at 4 warning signs (3 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com